


Redcare Pharmacy (XTRA:RDC) Could Be 16% Undervalued After Its New CEO Appointment
Why the new CEO matters for Redcare Pharmacy investors
The trigger for Redcare Pharmacy (XTRA:RDC) right now is a leadership reset. The Supervisory Board has installed Peter Schmid von Linstow as CEO and Managing Board member, effective 14 October 2026.
His background is rooted in scaling digital platforms and online marketplaces. Previous roles covered Visable, Parship, eBay, AutoScout24 and mobile.de, with a focus on turning user reach into commercially viable activity.
Investors in Redcare Pharmacy are watching because this appointment intersects with an already debated equity story. The share price has fallen 46.6% over five years while the business continues to be framed as a growth-driven online pharmacy in Europe.
The stock closed at about €74.80 on 14 October, a level that some market commentary links to expectations for future execution rather than current revenue and earnings alone. That puts extra attention on any leadership change.
Schmid von Linstow arrives with a record that combines founder experience and operational management. Company disclosures highlight his involvement in building media businesses, expanding dealer services and pushing international expansion at previous digital platforms.
Those details matter for Redcare shareholders because the investment case already leans heavily on logistics projects and automation. The new chief executive is being brought in to sharpen how digital traffic converts into revenue and, over time, how that revenue converts into profit.
Redcare Pharmacy’s share price has picked up speed recently, with a 30-day share price return of 22.8% and a 90-day gain of 9.6%, even though the 1-year total shareholder return has declined 10.5% and the 5-year total shareholder return is down 46.6%.
This short-term rebound around €74.80 coincides with the CEO change on 14 October 2026. Investors appear to treat this management transition as a potential reset of execution risk after several years of weaker total shareholder outcomes.
Scan how other high growth consumer and e-commerce stocks are priced against their fundamentals with the hand-picked 614 high quality undiscovered gems that might be facing similar execution questions as Redcare Pharmacy.
Redcare Pharmacy trades near €74.80, while analyst targets cluster around €88.80 and one model implies a much steeper discount. Which reference point looks closest to fair value after this CEO driven bounce?
Most Popular Narrative: 16% Undervalued
Against a last close of €74.80, the most followed thesis for Redcare Pharmacy points to a fair value of €88.80, which keeps the spotlight firmly on how future cash generation might bridge that gap.
Scaling of logistics investments such as the new Pilsen center and the Sevenum automation project, which target up to 70% lower labor cost per order and capacity increases from 2027, is set to improve fulfillment efficiency and support adjusted EBITDA margin and net profit.
See why 11 investors see Redcare Pharmacy as 16% undervalued.
Result: Fair Value of €88.80 (UNDERVALUED)
Still, the Redcare Pharmacy story depends heavily on German and European e prescription rollouts. Any slowdown there or tougher non Rx competition could quickly test this 16% undervalued narrative.
Find out about the key risks to this Redcare Pharmacy narrative.
Another View: What Redcare Pharmacy’s P/S Ratio Suggests
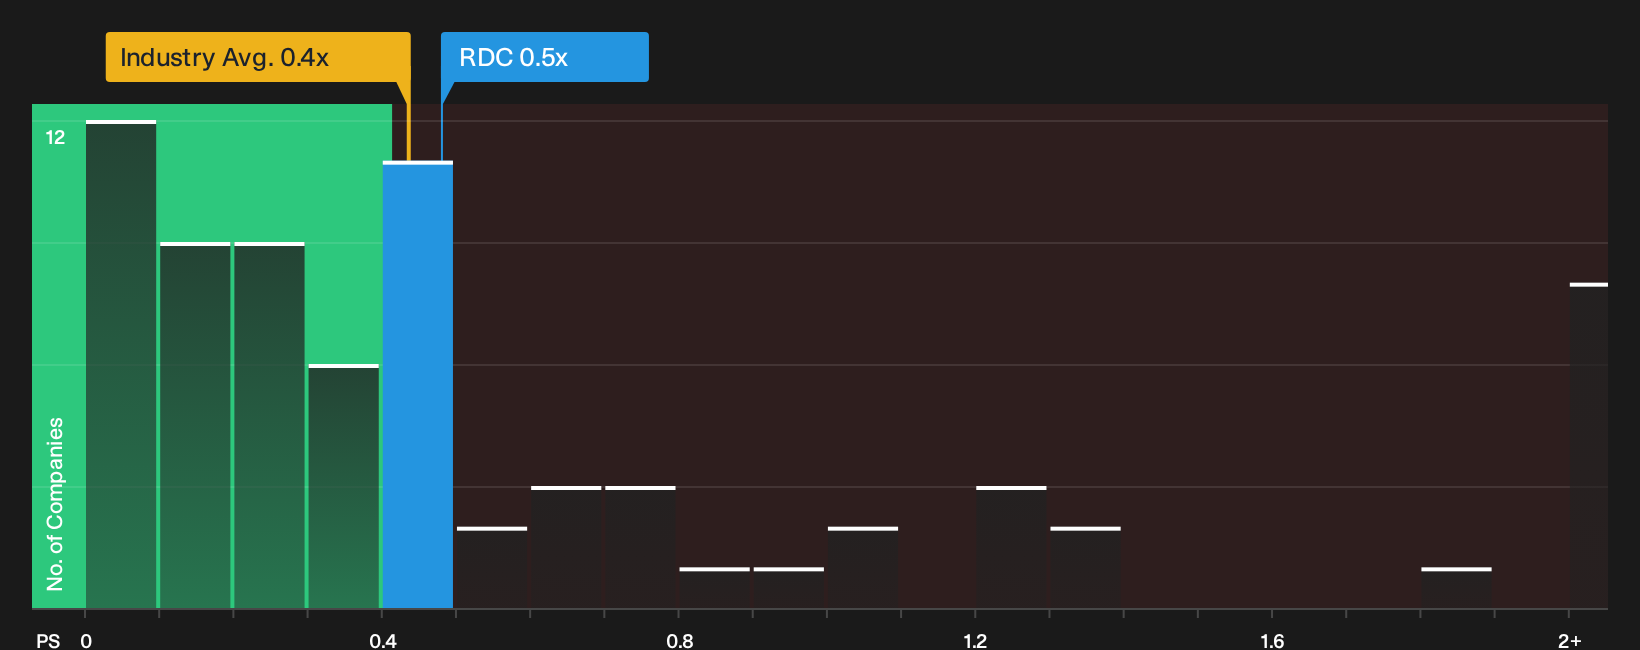
The first story frames Redcare Pharmacy as about 16% undervalued at €74.80 versus a fair value of €88.80. A different lens tells a tougher story. On a P/S of 0.5x, the share trades above both the European Consumer Retailing average of 0.4x and a fair ratio of 0.2x, which points to meaningful valuation risk if sentiment cools.
For anyone weighing that gap between upside narrative and richer sales multiple, it helps to see how the numbers stack up in detail, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Redcare Pharmacy story right now make outside data even more useful. Move quickly and frame your own take using the 2 key rewards and 1 important warning sign.
Looking for more Redcare Pharmacy investment ideas?
If you stop with Redcare Pharmacy alone, you risk missing out on other compelling setups that fit your style and might balance your overall exposure.
- Target potential value opportunities by scanning companies that the market prices cautiously but with strong underlying metrics through the 189 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by focusing on resilient balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (204 results).
- Reduce unwanted shocks by concentrating on businesses with steadier profiles through the 234 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com