


Hawkins (HWKN) Pullback Puts Its Valuation Debate Back In Focus
Hawkins (HWKN) recently drew investor attention after its shares closed at US$131.66, leaving the company valued at about US$2.75b. That price now anchors fresh discussion around performance and valuation.
Recent trading tells a mixed story. Hawkins has logged a 7.74% 1 month share price return, yet the share price is still down 9.38% year to date. The 3 year total shareholder return of 139.57% and 5 year total shareholder return of 263.97% point to long term momentum that contrasts with the weaker 1 year total shareholder return of 18.15%.
Spot emerging momentum beyond Hawkins by scanning a hand picked 33 high quality undervalued stocks with solid cash flows and balance sheets that may support more resilient long term returns.Hawkins has built a broad chemicals and water treatment platform, yet the recent share pullback muddies the picture. Are investors looking at a quality business on sale or one that already reflects its strengths in the price?
Preferred P/E of 34.1x for Hawkins: Is it justified?
On valuation, Hawkins trades on a P/E of 34.1x, which sits against a last close of $131.66 and raises questions about how much future earnings strength the market is already pricing in.
The P/E ratio compares the share price to earnings per share and gives a quick read on how much investors are paying for each dollar of profit. For a chemicals and water treatment group like Hawkins, this is a useful shorthand because earnings quality, capital intensity, and cyclical swings all feed directly into that number.
Here, the stock changes hands at a P/E of 34.1x while the US Chemicals industry averages 21x and Hawkins' own peer set averages 20.9x. That is a steep premium. The estimated fair P/E ratio of 17.8x is also far lower than the current multiple, which points to a level the valuation could move toward if expectations cool.
Explore the SWS fair ratio for Hawkins.
Result: Price-to-Earnings of 34.1x (OVERVALUED)
Still, a rich 34.1x P/E leaves Hawkins exposed if sector sentiment cools or if its chemicals and water treatment earnings trend proves less durable than expected.
Find out about the key risks to this Hawkins narrative.
Another View on Hawkins: What the DCF Says
The rich 34.1x P/E paints Hawkins as expensive, yet our DCF model lines up differently. At a share price of $131.66 and an estimated future cash flow value of $148.64, the stock screens as about 11.4% below that fair value. Does that gap flag mispricing or just ambitious cash flow assumptions?
Look into how the SWS DCF model arrives at its fair value.
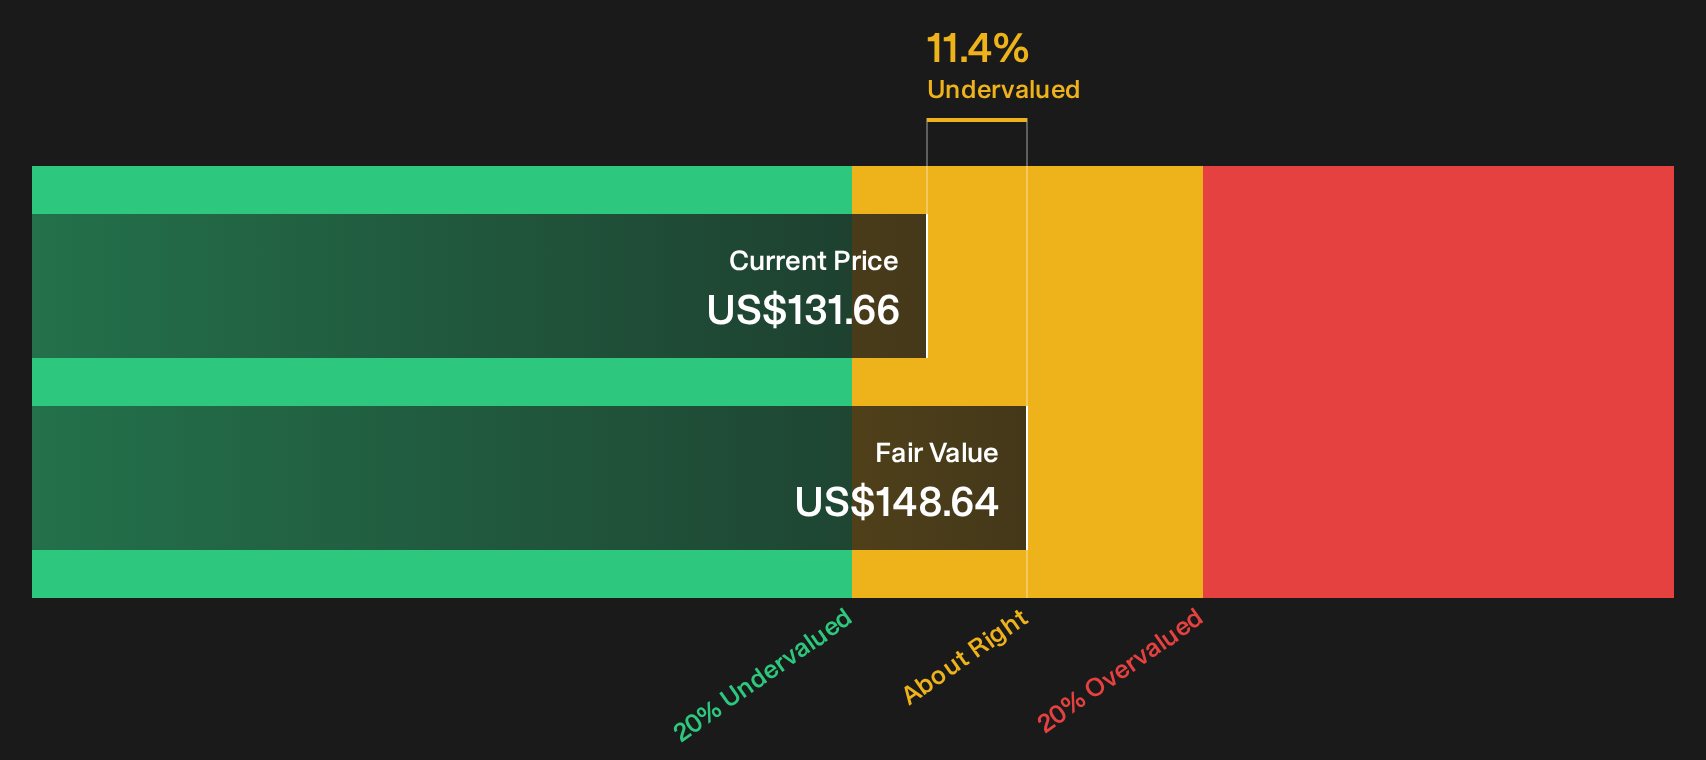
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawkins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hawkins can easily pull you in both directions, so move quickly to check the data, weigh the concerns, and see the potential rewards captured in the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Hawkins?
If Hawkins has you rethinking valuation and quality, use that momentum and widen your search. The right comparison set often sharpens your conviction.
- Target potential mispricing by reviewing companies that trade below their assessed worth through the 33 high quality undervalued stocks.
- Strengthen your focus on stability by scanning a 32 resilient stocks with low risk scores that screens for resilience when conditions turn choppy.
- Hunt for underfollowed opportunities by checking a 20 high quality undiscovered gems that filters for strong fundamentals hiding outside the usual headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com