


Is Earnings Growth Altering The Investment Case For Crown Holdings (CCK)?
- Crown Holdings is set to report quarterly earnings after the bell on Monday, with analysts expecting 6.9% year on year revenue growth, compared with a 4.2% increase in the same period a year earlier.
- The upcoming results put a spotlight on how efficiently Crown Holdings is converting strong beverage can and packaging demand into revenue, especially given its track record of outperforming consensus expectations.
- We will now consider how the anticipated acceleration in Crown Holdings' revenue affects the investment narrative built around demand, cash flow and capacity.
Scan how Crown Holdings' setup compares by sizing up 33 high quality undervalued stocks that are also turning steady demand into stronger top-line momentum ahead of earnings season.
Crown Holdings Investment Narrative Recap
Crown Holdings attracts shareholders who buy into steady demand for recyclable metal cans and a business that turns that demand into cash. The near term story hinges on how effectively new and existing capacity, especially in beverages and Transit Packaging, supports that conversion. The upcoming quarter looks more like a check in on execution than a turning point, so the headline expectations alone do not materially change the thesis.
The bigger swing factor right now sits on the cost side. Freight, energy and industrial gas expenses that run ahead of contractual recovery can eat into margins even when volumes hold up. The main near term risk is that higher input costs and softer Brazil conditions offset any benefit from top line momentum in North America and Europe.
Recent guidance around capital spending is the announcement that ties closest to this earnings setup. Crown Holdings has allocated about US$550 million of 2026 capex to capacity in Brazil, Greece, Spain and a new 2.2 billion can facility in India, where roughly 70% of volume is under long term commitments. That program frames how investors think about both current earnings and future cash generation.
Those projects matter because they interact directly with the upcoming results. Strong utilization in North America and Europe supports pricing, while new lines in faster growing regions aim to capture demand for sustainable packaging. The operational test is straightforward. Management needs to keep these plants on time and on budget, maintain the Transit Packaging cash engine, and prevent higher energy and freight costs from eroding the benefit of new capacity.
Crown Holdings' current setup reflects analysts’ expectations for 2.9% yearly revenue growth. Earnings today are $784.0 million and are projected to reach $937.0 million by 2029, a roughly $153 million increase that underpins the forecast for $14.4 billion in revenue and $937.0 million in earnings in that same year.
Uncover why Crown Holdings' fair value indicates a 20% potential upside to its current price, which could close faster than many investors expect.
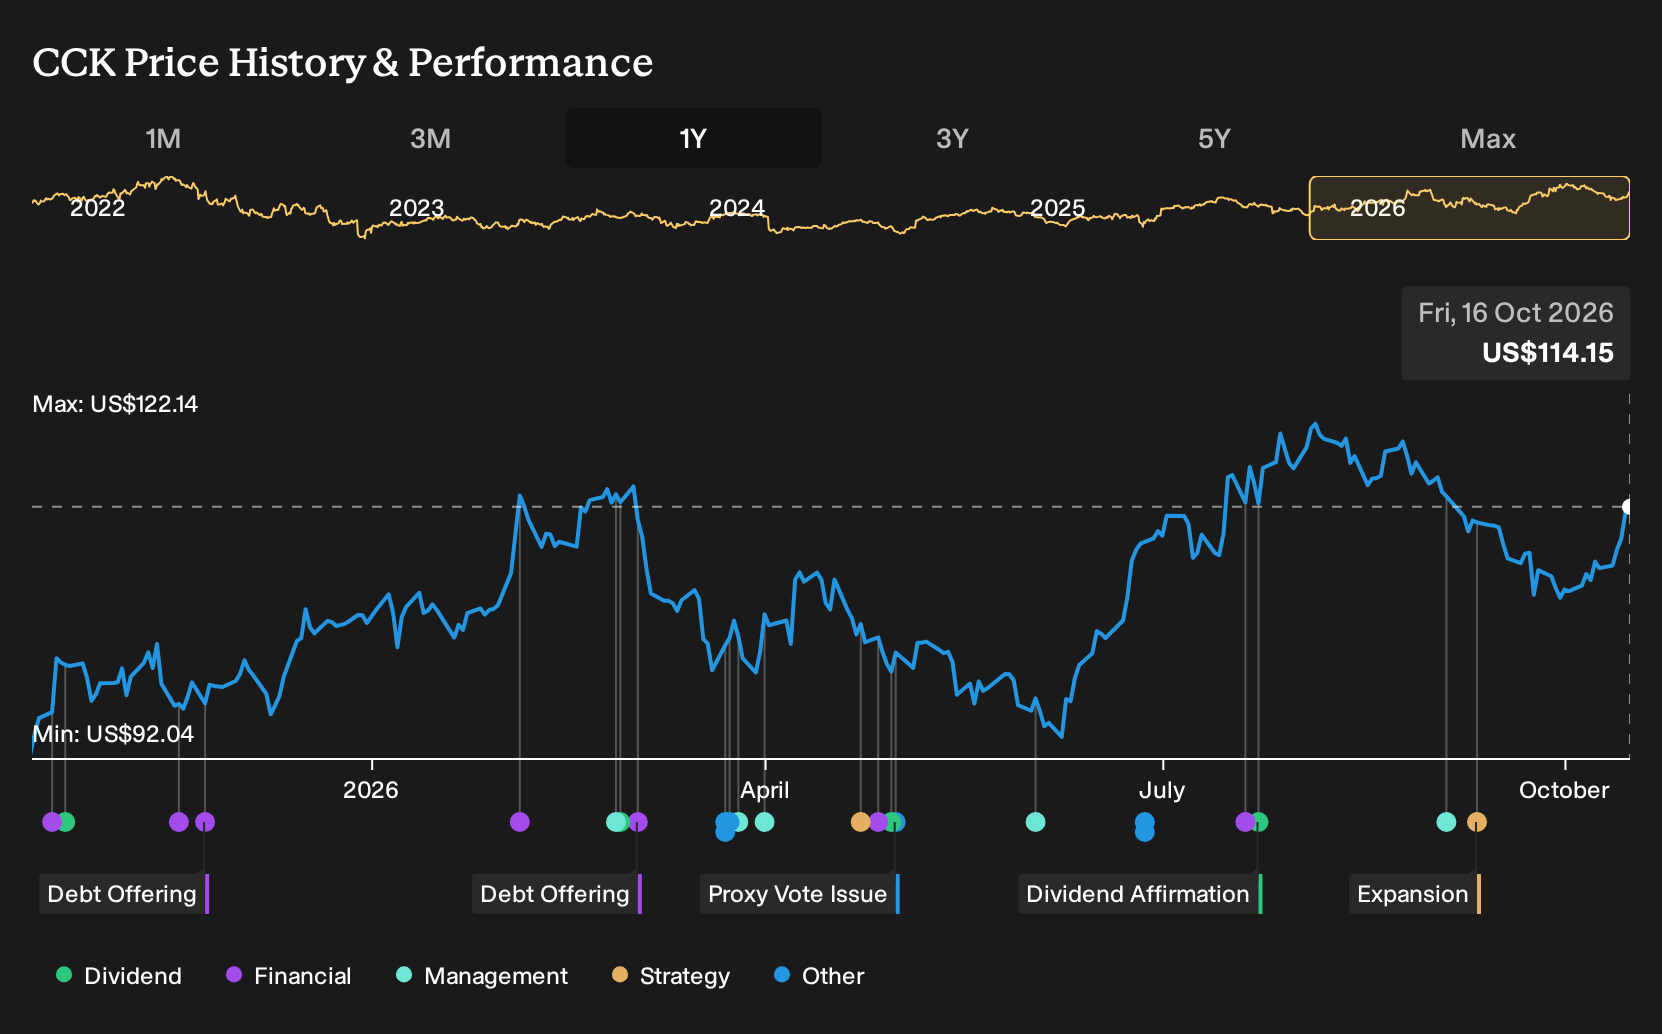
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community stretch from just US$76 up to about US$386.3b, a gap that signals how differently retail investors frame Crown Holdings. Some lean into capacity expansion, sustainability rules and free cash flow, while others focus on one off demand, higher input costs and Brazil softness. You should expect wide disagreement and use these contrasting angles to pressure test your own thesis.
Explore 3 other Crown Holdings fair value estimates, including one that suggests as much as 33% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Crown Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Crown Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Crown Holdings' overall financial health at a glance.
Looking for more ideas beyond Crown Holdings?
Once you have a view on Crown Holdings, it often helps to compare that thesis with other opportunities so you can see where the risk and reward trade off really feels worth it.
- For investors who want strong fundamentals and valuation support, start with a 33 high quality undervalued stocks that combines quality cash flows with what the model flags as discounted pricing.
- If capital protection sits high on your list, focus on a 32 resilient stocks with low risk scores that aims to keep volatility and balance sheet stress in check.
- For those hunting for potential future leaders before they are widely followed, scan a 20 high quality undiscovered gems that pairs robust metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com