


What Toast (TOST)'s AI Tools Launch Means For Shareholders
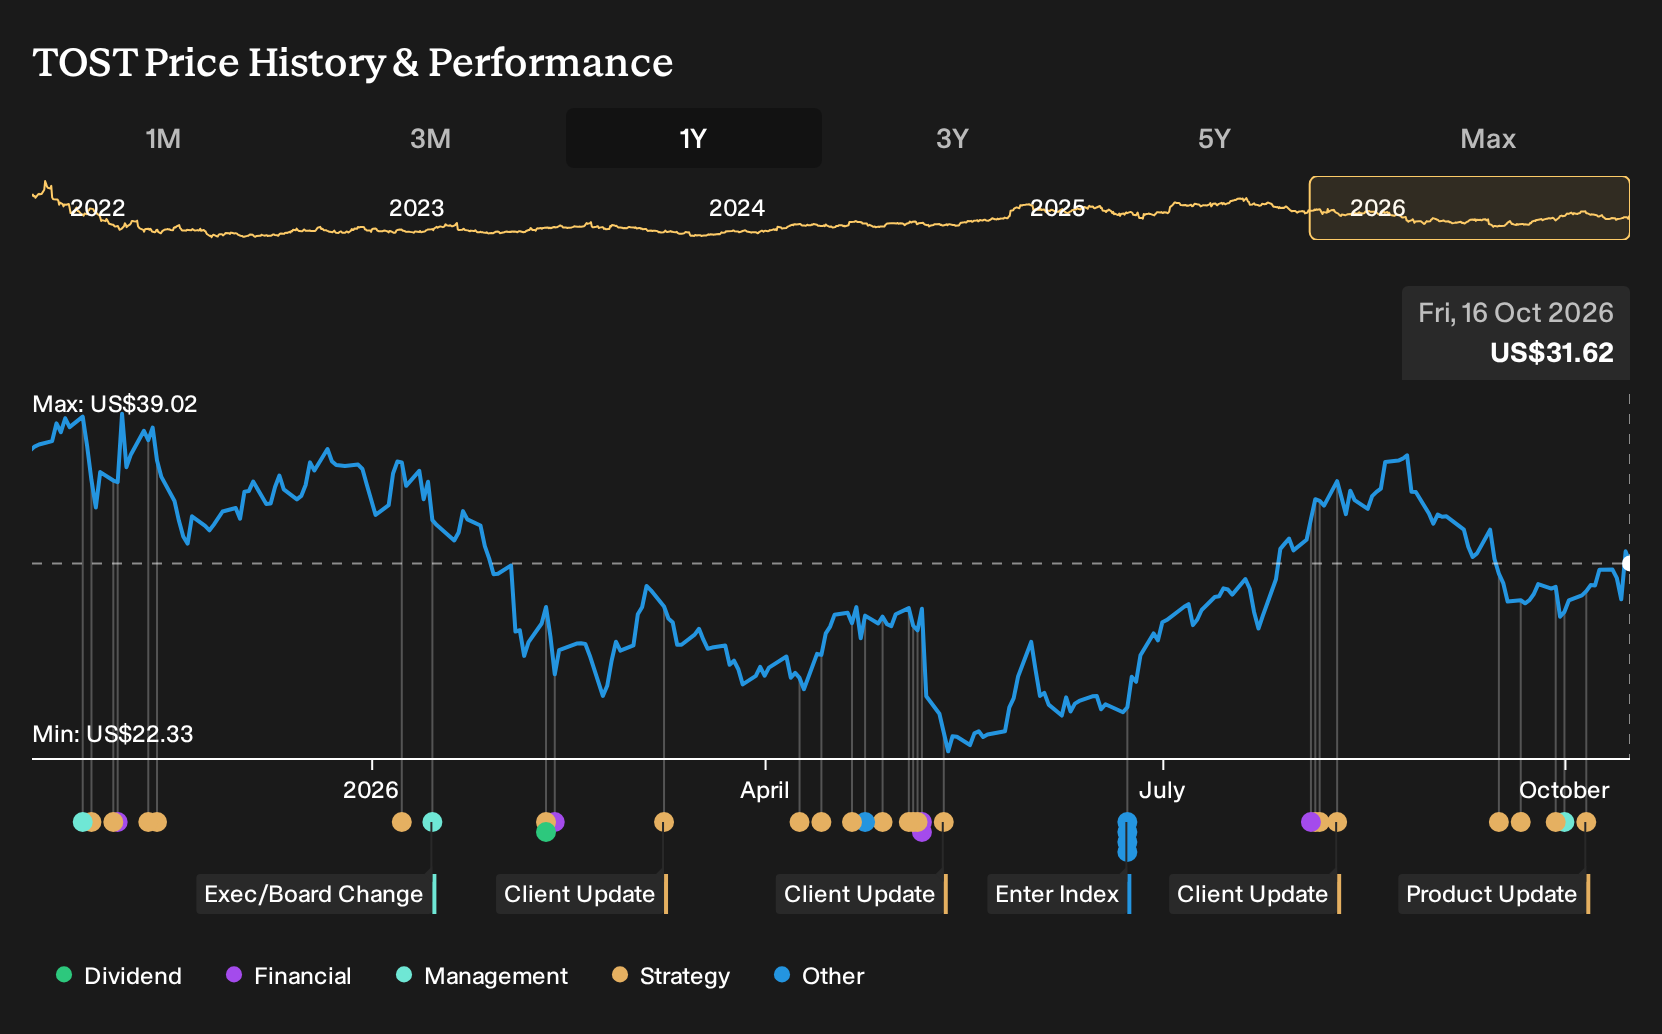
- Toast introduced Toast IQ Team and expanded Toast IQ Grow earlier in October 2026, adding AI tools for labor management, payroll, marketing, menu optimization, and call handling directly into its restaurant and retail platform.
- The move pushes Toast further toward being a full operating system for hospitality operators by tying everyday staffing, payments, and guest engagement more tightly to its software and transaction ecosystem.
- We will look at how Toast's investment narrative evolves as AI driven labor and marketing agents become central to its platform.
Toast Investment Narrative Recap
To own Toast, you need to believe it can turn its restaurant platform into an essential operating layer, with software, payments, and AI tools earning more from each location over time. The short term swing factor is whether customers actually adopt Toast IQ Team and Toast IQ Grow at scale. Recent AI launches are important, but the immediate impact on results is still unproven.
The biggest near term risk stays the same. Restaurant spending and gross payment volume per location have already shown pressure, and competitors like Square and Clover remain aggressive on product and pricing. If higher software and sales costs outpace productivity gains from these AI agents, Toast’s margin story could stall even as usage grows.
The Toast IQ Team rollout looks most relevant for the next phase. It ties sales forecasting, scheduling, timekeeping, tips, and payroll into one system. That positions Toast to be judged not just on payment volume, but also on whether it can help operators run leaner shifts and manage labor volatility without adding complexity to already stretched teams.
For you as an investor, the key question is execution. Strong tools on paper do not resolve risks around elevated sales and marketing spend, hardware costs, or international expansion. IQ Team and related AI agents give Toast a clearer operational catalyst to support software and fintech revenue, yet competitive responses and adoption rates will influence how much those products contribute to future earnings.
Toast's narrative projects US$11.2b revenue and US$1.1b earnings by 2029. This rests on 18.0% yearly revenue growth and roughly a 2.3x earnings increase from US$486.0m today.
Discover how Toast's fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on Toast leans heavily on the AI story. The most optimistic analysts were already modeling revenue growth of 20.6% a year and earnings of about US$1.2b by 2029 before this IQ Team news. That group expects faster AI adoption and higher margins, while others stay cautious. Investors can use this spread to test their own stance.
Explore 6 other Toast fair value estimates, including one that suggests as much as 47% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Toast research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Toast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toast's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toast?
Once you have a view on Toast, it can help to put that thesis in context by lining it up against other companies with very different risk and return profiles using the Simply Wall St Screener.
- If you want potential upside with tighter balance sheet risk, scan a 32 resilient stocks with low risk scores that already clear our resilience filters on debt and earnings quality.
- For investors who care most about quality at a reasonable price, review a 33 high quality undervalued stocks that combine strong fundamentals with what our models see as discounted valuations.
- If you prefer resilient cash generation and income over time, focus on a 8 dividend fortresses built around higher yields supported by underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com