


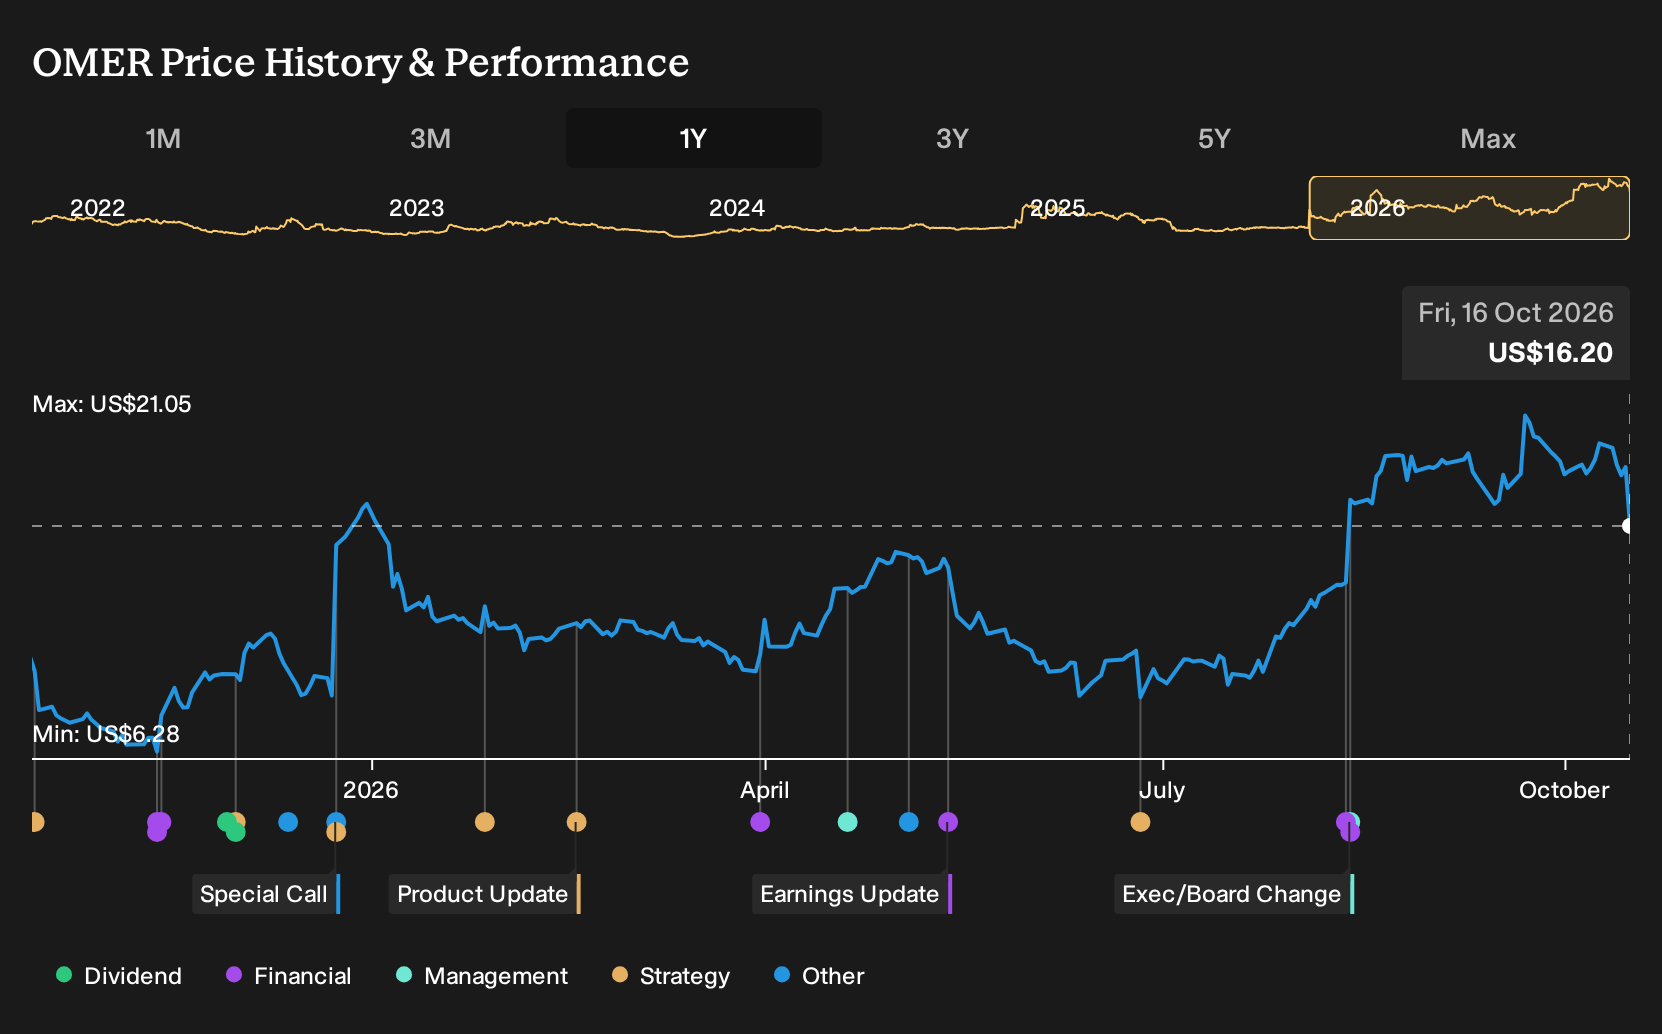
Why Omeros Stock Is Down 13.8% And What's Next After EU Drug Rejection
- Omeros reported that the European Medicines Agency’s CHMP upheld its negative opinion on the marketing authorization application for narsoplimab in TA TMA after re-examination, while the drug remains FDA approved in the U.S. as YARTEMLEA for patients aged two and older.
- The company plans to end its European compassionate use program for YARTEMLEA due to U.S. demand, which tightens near term supply options for TA TMA patients in Europe, even as Omeros pursues additional MASP 2 indications and new clinical studies.
- The focus now is on how Omeros' pre-news investment narrative holds up in light of the EMA setback on narsoplimab's European approval.
Scan how Omeros’ setback compares with other potential turnaround stories in biotech by reviewing the hand picked 20 high quality undiscovered gems now on Simply Wall St.
Omeros Investment Narrative Recap
To own Omeros, you need to believe the YARTEMLEA launch in the U.S. can support the business while the broader MASP-2 pipeline matures. The EMA rejection affects the European expansion story, but the core near term catalyst still appears to be commercial execution and patient uptake in the approved U.S. TA TMA population.
The biggest near term risk remains funding and concentration on a single commercial product, especially while Omeros carries past losses and negative shareholders equity. Any delay in expected cash inflows or slower than hoped U.S. demand for YARTEMLEA would tighten liquidity and could make external financing more likely.
The recent EMA decision matters most when viewed alongside Omeros’ plan to broaden YARTEMLEA and its MASP-2 franchise into new indications. Management has highlighted upcoming studies in acute respiratory distress syndrome and prevention of high risk TA TMA in pediatric patients as next steps for potential growth in the product family.
For you, that means the key operational question is whether the current U.S. approval and ongoing trials can offset the lack of an EU label. Progress starting those ARDS and pediatric TA TMA studies, plus any clarity on timelines and design, will likely influence how credible future MASP-2 revenue diversification appears from here.
Analysts currently build a story for Omeros around revenues of $375.5 million and earnings of $165.9 million by 2029. This implies annual revenue growth of 113.8% and an earnings increase of about $49.4 million from $116.5 million today.
Uncover why Omeros' fair value indicates a 70% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You have a very different picture if you focus on funding risk instead of new indications. The most bearish Omeros analysts were already working with 96.7% annual revenue growth and about $71.9 million of earnings by 2029 before this EMA decision. That is a far more cautious story, and it may shift again as views update.
Explore another Omeros fair value estimate, including one that suggests it could be worth just $27.50!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Omeros research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Omeros. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omeros' overall financial health at a glance.
Looking For More Ideas Beyond Omeros?
If the Omeros story has you rethinking risk, liquidity, or concentration, it can help to line it up against a broader watchlist of potential opportunities using the Simply Wall St Screener.
- If you want income resilience at the portfolio level, scan through 8 dividend fortresses that may offer substantial yields with more established payout records.
- For those aiming to tilt toward value, compare Omeros with 33 high quality undervalued stocks that pair stronger balance sheets with attractive valuation metrics.
- If capital protection matters most, focus your next round of research on 32 resilient stocks with low risk scores that our models flag as more defensively positioned.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com