


Allient (ALNT) Rides Record Bookings, Is It Still A Bargain?
Allient (ALNT) has been drawing attention after a strong year so far, with the stock up 66.7% year to date and 88.5% over the past 12 months.
Momentum has cooled in recent weeks, with the share price down 15.7% over the past week and 7.8% over the last month. Even so, Allient still shows strong momentum when you compare the recent pullback with its 1-year total shareholder return of 88.5% and 3-year total shareholder return of 231.5%.
See how Allient’s surge compares with other industrial and motion-control players by checking our hand picked list of 91 robotics and automation stocks.
Allient now trades at US$92.64 after a sharp run and a fresh pullback. Do the current fundamentals and pricing still leave more upside potential than downside risk for new buyers?
Most Popular Narrative: 21.5% Undervalued
At a last close of $92.64 versus a most followed fair value estimate of $118, the current Allient share price sits well below that narrative anchor. This puts the spotlight firmly on whether recent bookings and margins can sustain this gap.
The main thing that has to go right is that Allient converts its current record bookings, growing backlog and mix shift toward higher-margin sectors into sustained earnings quality, while managing execution risks from restructuring and the Dothan facility transition.
See why 8 investors see Allient as 21% undervalued.
Result: Fair Value of $118 (UNDERVALUED)
Still, the bullish Allient narrative depends heavily on record margins holding up, and on record bookings and backlog actually converting into revenue rather than stalling or slipping.
Find out about the key risks to this Allient narrative.
Another View: Allient Looks Expensive On Earnings
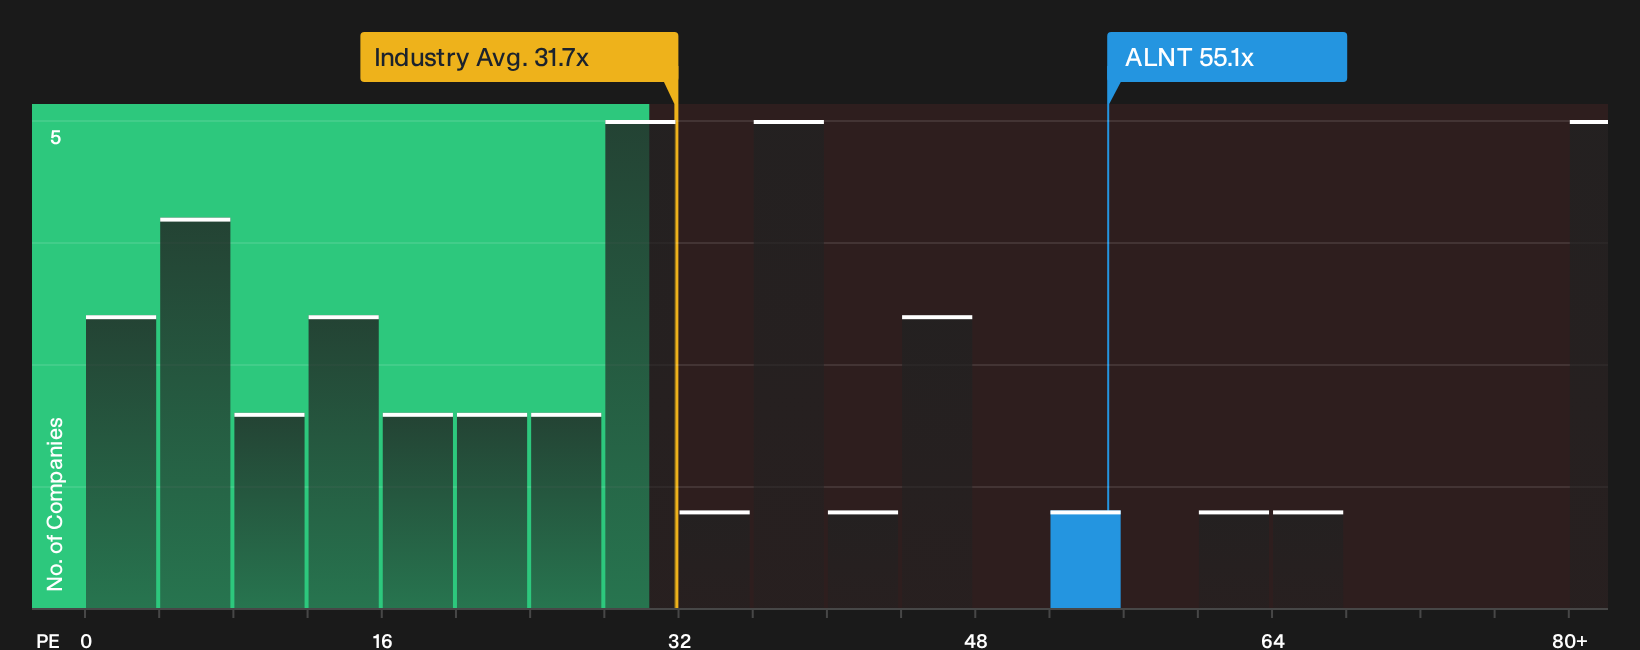
The fair value narrative pegs Allient at $118, yet the current P/E of 55.1x tells a very different story. That multiple is well above the US Electrical industry on 31.7x, the peer average on 28.5x, and even the fair ratio estimate of 24.3x.
In plain terms, investors are paying more than double the fair ratio for each dollar of Allient’s earnings, and a sizeable premium to sector and peer benchmarks. That inflates valuation risk if growth or margins do not line up with expectations. The question is which signal to trust more: the story or the sticker price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Allient's value case and risk profile can pull you in both directions, so move quickly, test the numbers yourself, and then weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Allient?
If Allient has caught your eye, do not stop there. Broader context across other opportunities can help you benchmark risk, quality, and potential fit in your portfolio.
- Target steadier compounding by scanning for companies with healthy balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for possible mispriced opportunities by checking the 33 high quality undervalued stocks that combine stronger financial profiles with appealing valuations.
- Zero in on lesser known prospects by reviewing the 20 high quality undiscovered gems that pair quality metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com