


What Telia Doubters Overlooked
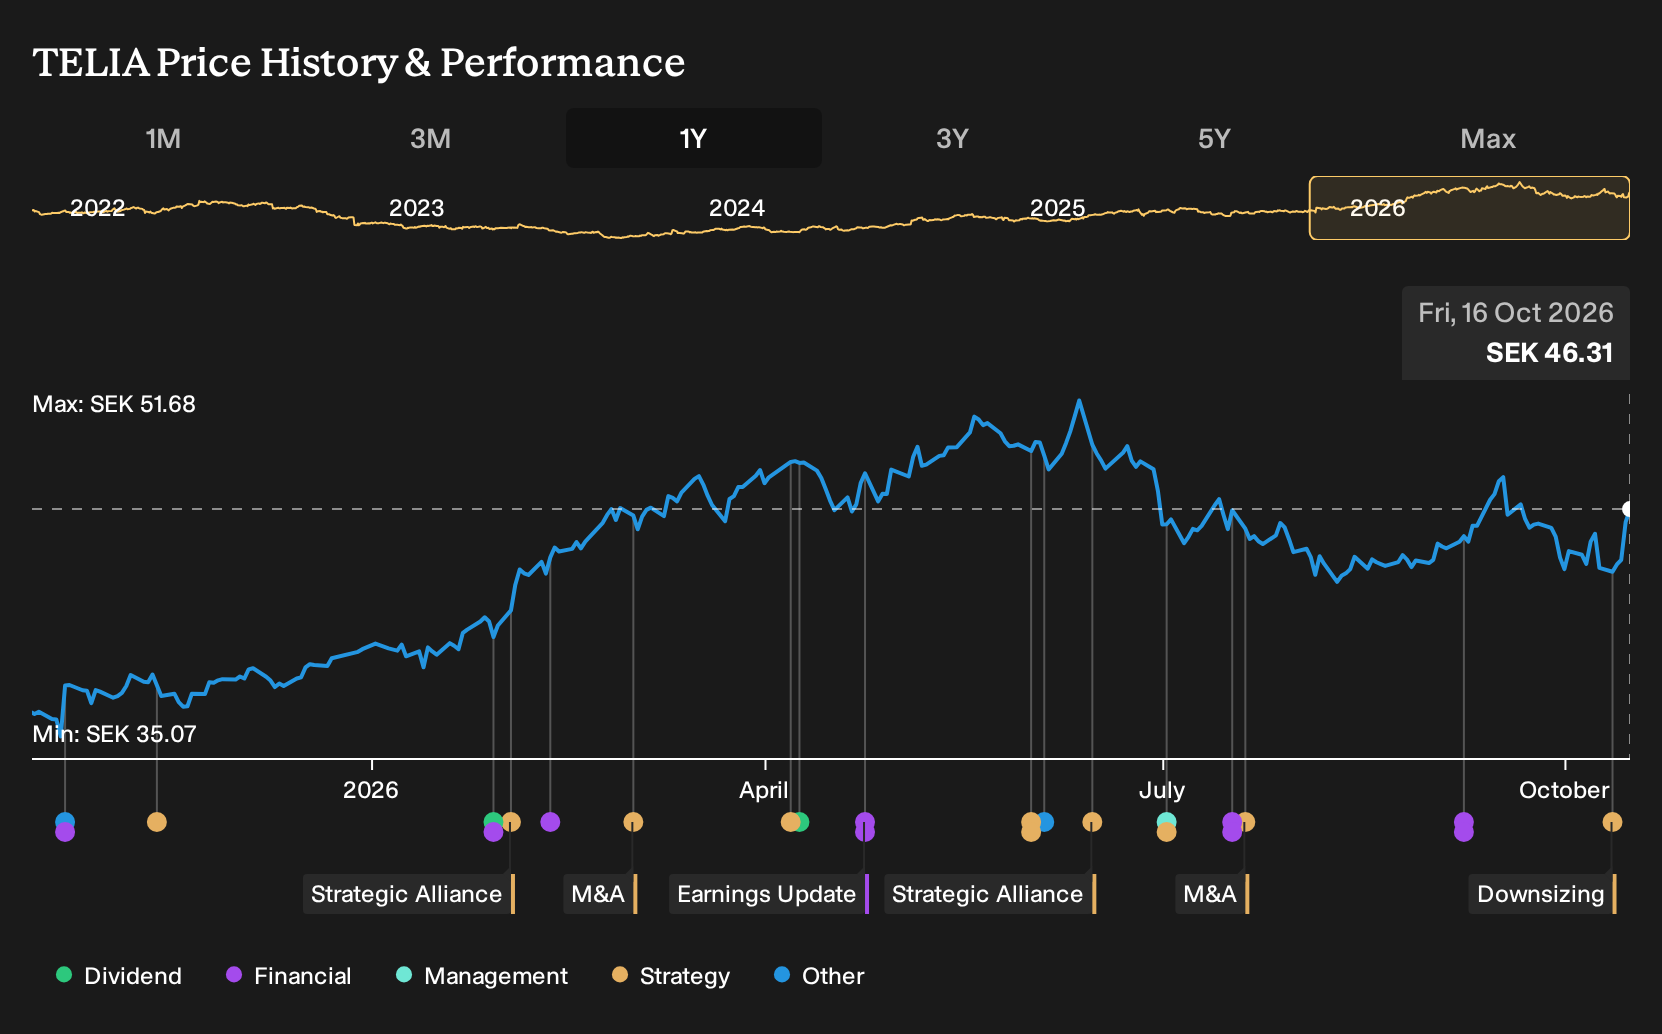
Telia’s year was defined by concrete moves rather than big promises, including the launch of Sweden’s first commercial 5G standalone IoT service tailored for critical applications. For Telia shareholders, the return over the past year was 33.8%, including dividends. If you had been deciding on 16 October 2025 whether to buy, what would you have needed to believe about this push into high value connectivity and the simultaneous asset sales in Finland?
The move put Telia in the middle of this trade. Scan 55 AI infrastructure stocks for other companies exposed to it.
The Two Telia Stories Investors Were Arguing About
The shares cost SEK36.18 at the start of the period, and Telia was being pulled between two very different stories about what came next.
On the optimistic side, the Digitalization And 5G Will Expand Nordic Connectivity narrative pointed to a Fair Value of SEK47, a price level implied by assumptions that 5G, private networks and convergence in Sweden would support higher net margins and stronger free cash flow.
The Legacy Telecom Decline And Rising Energy Expenses Will Constrain Outlook view argued for a Fair Value of SEK27, hinging on the risk that legacy service decline, rising energy costs and tight Nordic and Baltic focus would strain revenue and compress profitability.
What The Telia Evidence Actually Tested
The key test for Telia was whether higher value connectivity could show up in the numbers. Q2 2026 revenue of SEK20,705m and net income of SEK2,230m, with net margin at 10.8% versus 9.9% a year earlier, gave the bullish profitability story some backing. Planned cuts of 900 jobs and Finnish IT outsourcing showed the cost and focus trade off was still live.
The practical takeaway is simple. When a telecom talks up higher value services and restructuring, check whether net margin and absolute profit move in the same direction, and whether asset sales shrink or reinforce the core network that supposedly underpins that pitch.
What Telia's Price Is Asking You To Believe Now
Telia trades at SEK46.31 after a 33.8% gain over the past year, and the selected Narrative’s Fair Value now sits below that level. The Narrative argues that the issue is less about size and more about how much of today’s revenue truly converts into durable earnings.
A buyer at today’s price is effectively betting that Telia can keep service revenue growing and margins firm. The question is how that assumption holds up if broadband pricing pressure, Norway’s drag and capital light deals leave revenue quality thinner than the headline numbers suggest.
"The main thing that has to go right is that Telia Company converts its convergence, cost efficiency and capital-light infrastructure programs into sustained, broad-based profitability improvements that offset weak spots like Norway and lower-ARPU broadband in Sweden."
One Narrative disagrees with today's price. → See where this Narrative says Telia should trade
Looking One Step Beyond Telia
Telia is leaning hard into higher value connectivity. Your decision does not have to stop there.
Similar ambitions elsewhere rest on reliable broadband and broad 5G reach that keep customers connected.
Another large operator is pushing fixed wireless and fiber together, aiming to anchor more devices and business traffic.
It is also pursuing long term enterprise deals around private connectivity and AI heavy workloads, tying clients in.
If that approach reshapes churn, pricing influence and contract length, the payoff from connectivity demand could look very different.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 15% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com