


Dear Sandisk Stock Fans, Mark Your Calendar for October 29
Sandisk (SNDK) will release its first-quarter fiscal 2027 earnings results on Thursday, October 29. The event matters for Sandisk stock fans, as it could set the trajectory for SNDK.
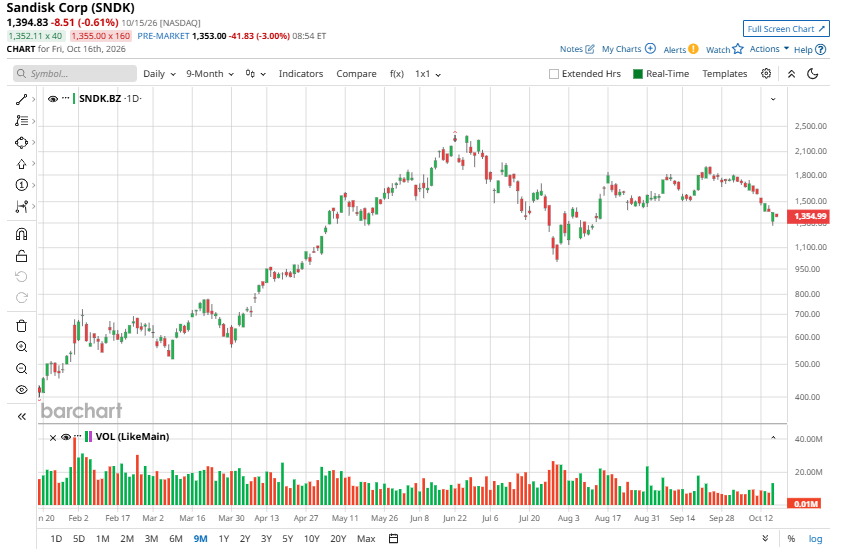
Following a substantial rally, SanDisk shares have pulled back and are trading approximately 41% below their 52-week peak. The decline reflects profit-taking after strong gains, concerns about growing competition from Chinese memory chip manufacturers, and uncertainty about whether investment in AI infrastructure can maintain its current momentum.
Despite concerns, Sandisk’s upcoming earnings report could catalyze the stock, especially as demand for data storage solutions remains high. Further, the pricing environment remains supportive, driving both revenue and margins.
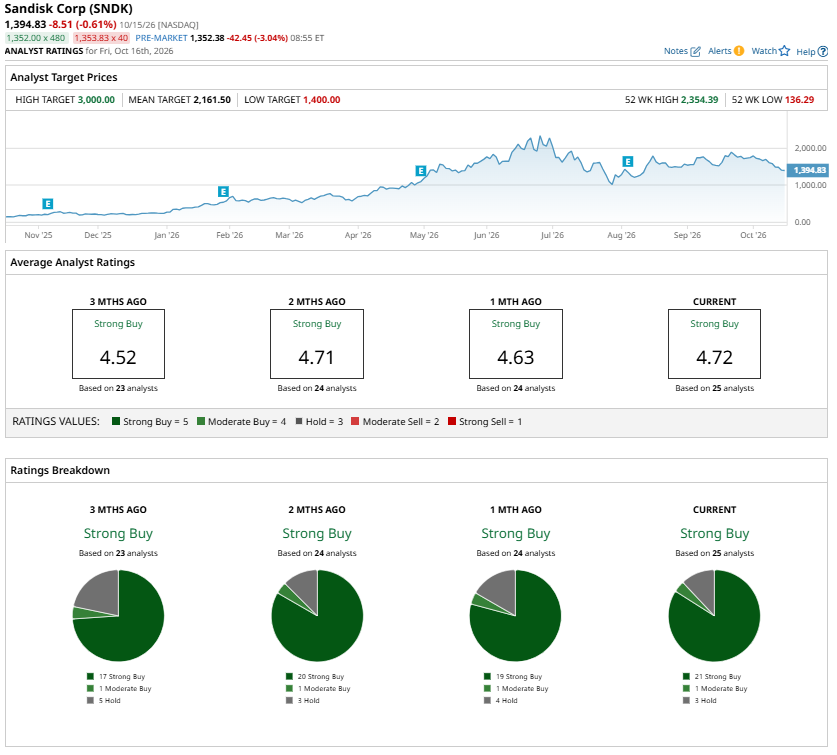
In addition, analysts’ sentiment remains bullish on SNDK stock ahead of the earnings release. The average price target also points to significant upside potential in SNDK stock.
Sandisk Stock: Q1 Outlook
Sandisk appears well-positioned for continued growth in the first quarter of fiscal 2027, supported by rising AI-driven storage demand, tight NAND supply, and higher pricing. In addition, a growing share of revenue secured through long-term agreements bodes well for growth.
Sandisk closed fiscal 2026 on a strong note, with revenue of $20.3 billion, up 175% year over year. Adjusted earnings per share (EPS) also surged from $2.99 to $70.88, highlighting strong year-over-year growth.
The outlook for fiscal 2027 remains favorable. NAND demand continues to exceed available supply, while management expects capacity to remain committed beyond calendar 2027. Persistent supply constraints could also support pricing and profitability.
For the first quarter of fiscal 2027, Sandisk forecasts revenue of $10.3 billion to $10.8 billion, up from $2.3 billion in the prior-year quarter. SNDK’s top line is likely to benefit from sequential improvements in both shipment volumes and pricing. Adjusted EPS is projected at $44 to $46, substantially above the $1.22 reported in the same quarter last year. Analysts anticipate earnings of $45.22 per share.
Notably, Sandisk has consistently outperformed analysts’ consensus EPS estimate in the past four consecutive quarters, including a 16.7% beat in Q4 of fiscal 2026.
Looking ahead, Sandisk is well positioned to keep beating estimates. Sandisk’s expanding portfolio of long-term agreements, known as NBMs for “new business model,” supports the investment case. These contracts improve revenue visibility, strengthen demand planning, and potentially reduce earnings volatility. Management expects NBMs to represent more than 50% of total bits in fiscal 2027, increasing to roughly two-thirds in fiscal 2028. Based on minimum contractual pricing, signed agreements represent at least $93.9 billion in potential revenue.
Beyond fiscal 2027, Sandisk expects revenue to grow at a mid-to-high-teens annual rate from fiscal 2028 through fiscal 2030. Management also anticipates adjusted gross margins of around 80% and adjusted free cash flow margins near 50%.
Overall, accelerating AI adoption, favorable NAND pricing, constrained supply, and stronger contractual revenue visibility support Sandisk’s growth outlook. These factors could lay the foundation for sustained earnings expansion and support a solid recovery in its share price.
Sandisk’s Valuation Looks Compelling Ahead of Earnings
Sandisk stock appears attractively valued ahead of its upcoming earnings announcement. The stock trades at approximately 7.1 times forward earnings, a valuation that offers upside potential given the company’s strong projected earnings growth. Analysts expect Sandisk’s EPS to rise roughly 201% in fiscal 2027, despite a tough year-over-year comparison. Forecasts also suggest EPS growth could remain in the double digits in fiscal 2028, supporting the stock's investment case.
Load Up on Sandisk Stock
Sandisk’s growth prospects remain strong, supported by AI-driven storage demand, tight NAND supply, favorable pricing, and expanding long-term agreements. Its attractive forward valuation and robust earnings outlook support strong upside for SNDK.
Analysts assign a “Strong Buy” consensus rating on SNDK. The average analyst price target of $2,161.50 indicates 55% potential upside from current levels.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.