


Why Northwest Natural Holding (NWN) Is Getting Attention Today
Northwest Natural Holding (NWN) has increased its dividend, with the board approving a quarterly payout of $0.50 per share and raising the indicated annual rate to $2.00.
Northwest Natural Holding’s higher dividend lands at a time when the stock has edged up in the short term, with a 7 day share price return of 2.64%. Longer term total shareholder returns of 10.97% over 1 year and 42.88% over 3 years suggest momentum building around income and stability rather than rapid price swings.
Scan for other income-focused utilities that demonstrate similar staying power by reviewing our hand-picked list of 8 dividend fortresses
Northwest Natural Holding now offers a higher yield and a long dividend streak, yet the share price has already moved. Is this still a solid utility at a fair price, or has the recent enthusiasm stretched valuation?
Most Popular Narrative: 15% Undervalued
Northwest Natural Holding closed at $48.99, while the most widely followed narrative anchors fair value at $57.40, implying a valuation gap that hinges on how its Texas growth, MX3 storage project and water platform play out over time.
Robust customer growth in Texas via the SiEnergy platform, with recent quarters showing 15% to 20% organic growth and a backlog now above 260,000 future meters, continues to point to a long pipeline of meter additions that can lift Northwest Natural Holding revenues and earnings over time.
See why 7 investors see Northwest Natural Holding as 15% undervalued.
Result: Fair Value of $57.40 (UNDERVALUED)
Still, Northwest Natural Holding faces real pressure points, including rising operating and interest costs, as well as policy driven electrification that could curb future gas demand in key regions.
Find out about the key risks to this Northwest Natural Holding narrative.
Another View: Northwest Natural Holding Through The P/E Lens
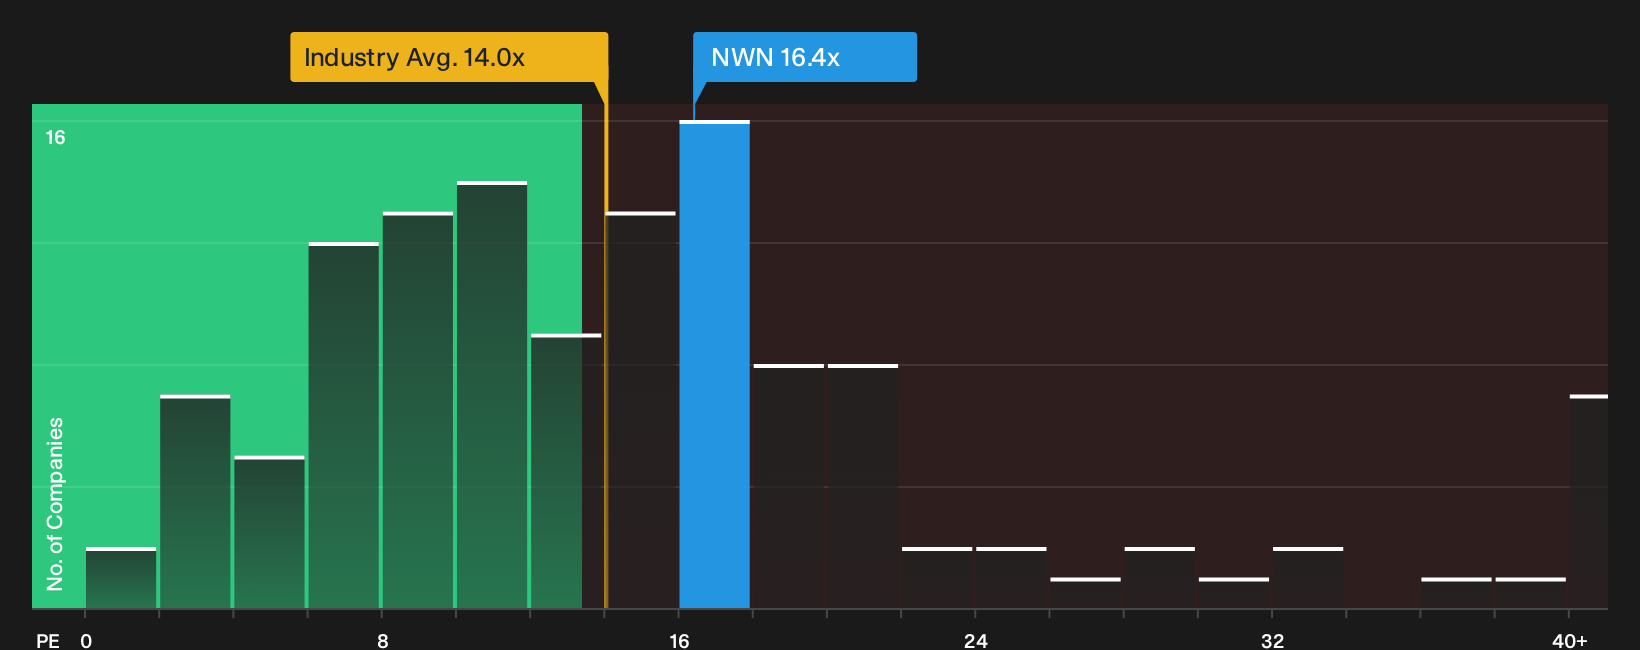
On simple P/E math, Northwest Natural Holding appears less attractive than the 15% undervalued narrative suggests. The shares trade on 16.4x earnings, above both US gas utility peers at 15.3x and the wider global group at 14x, yet only slightly below a fair ratio of 17.6x that the market could move toward. That points to limited margin for error if earnings progress slows, so it is worth considering how comfortable an investor might be paying a premium multiple for a regulated utility story built on steady rather than rapid growth.
For a closer look at what the earnings multiple implies for valuation risk and potential upside, and how it compares with similar regulated players, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Northwest Natural Holding so far. For a sharper view, weigh the income, valuation and policy questions against the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Northwest Natural Holding?
If you stop here, you only see one opportunity. Use the Simply Wall Street Screener to surface fresh ideas that match your income and risk goals.
- Target steady compounding by reviewing a curated pool of resilient businesses with strong fundamentals and low leverage through our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential bargains by scanning companies that pair quality with attractive pricing using the focused 33 high quality undervalued stocks.
- Strengthen your watchlist by spotting resilient opportunities with measured risk profiles through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com