


U.S. Business Update Might Change The Case For Investing In MS&AD Stock
- MS&AD Insurance Group Holdings recently held an Investor Relations Day focused on its U.S. business, highlighting the structure and priorities of its overseas insurance operations.
- The emphasis on U.S. activities puts more attention on how international underwriting, pricing discipline and capital allocation support the group’s broader earnings mix.
- We will now explore how MS&AD Insurance Group Holdings' investment narrative could be influenced by its renewed focus on the U.S. insurance franchise.
Compare how MS&AD Insurance Group Holdings’ renewed push in U.S. underwriting stacks up against other insurers and financials that screen well for resilient fundamentals using our curated list of solid balance sheet and fundamentals (22 results)
MS&AD Insurance Group Holdings Investment Narrative Recap
To own MS&AD Insurance Group Holdings, you need to be comfortable with a business that leans on disciplined underwriting, gradual premium rate changes and a growing overseas footprint to support earnings, while consensus points to modest revenue growth and some earnings pressure in the next few years. The near term swing factor still looks like how cleanly IFRS based results reflect underlying profitability, especially around onerous contracts.
The biggest operational risk remains pressure on loss ratios in reinsurance and U.S. specialty lines, paired with natural catastrophe exposure that can quickly alter margins. The latest IR Day focus on U.S. operations shapes understanding of these sensitivities but does not radically change the immediate risk reward skew.
The MS&AD Insurance Group Holdings IR Day on the U.S. business is the key fresh disclosure around this story. Management drilled into how overseas underwriting, particularly in the Americas, ties into group earnings diversification at a time when analysts expect earnings to ease slightly over the coming three years.
For catalysts, this matters because overseas expansion is one of the few explicit growth drivers flagged alongside domestic rate revisions and reinsurance portfolio build out. Execution on U.S. pricing, risk selection and capital allocation now connects directly to whether the group can offset forecast earnings declines and manage IFRS related volatility without eroding dividend capacity or balance sheet strength.
MS&AD Insurance Group Holdings is tied to analyst expectations that revenues reach ¥7,796.6b and earnings come in at ¥668.2b by 2029, which implies 1.2% yearly revenue growth and an earnings decrease of ¥201.3b from current earnings of ¥869.5b.
Uncover why MS&AD Insurance Group Holdings' fair value indicates that it is in line with its current price.
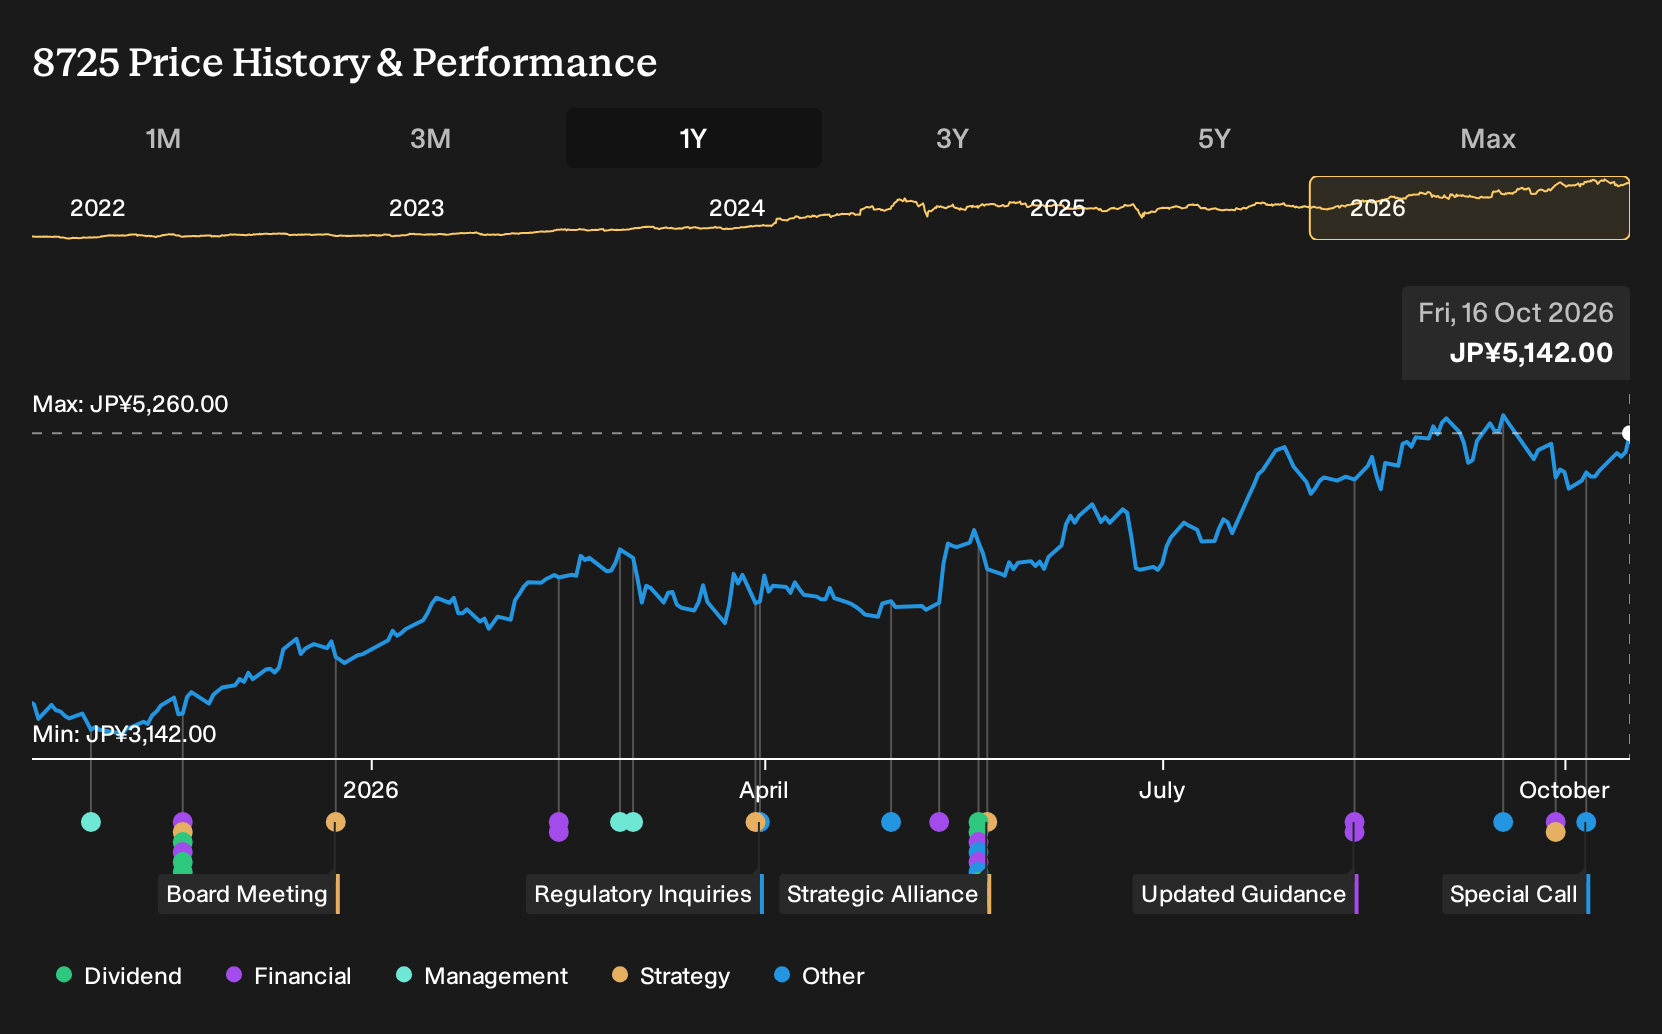
Exploring Other Perspectives
One alternate view puts far more weight on MS&AD Insurance Group Holdings’ exposure to natural catastrophe losses. The most cautious analysts were pencilling in revenue of about ¥7,343.0b and earnings near ¥547.7b by 2029, well below consensus. Those forecasts came before this U.S. focused IR Day, so some opinions may shift.
Explore 2 other MS&AD Insurance Group Holdings fair value estimates, including one that suggests it could be worth just ¥5178.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your MS&AD Insurance Group Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MS&AD Insurance Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MS&AD Insurance Group Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond MS&AD Insurance Group Holdings?
Once you have formed a view on MS&AD Insurance Group Holdings, it can help to compare that thesis with other businesses that share similar qualities or offer a very different risk profile. The Simply Wall St Screener makes that process faster by letting you filter for traits that match the kind of portfolio you are trying to build.
- If you care most about financial resilience and balance sheet strength, start by scanning our 23 resilient stocks with low risk scores that aim to keep drawdowns contained when conditions turn difficult.
- If you are hunting for potential mispricings, review our 73 high quality undiscovered gems that combine solid fundamentals with relatively limited market attention.
- If you prefer dependable income, focus on our 29 dividend fortresses that target higher yielding payouts backed by underlying cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com