


Aircraft And Defense Demand Could Be A Game Changer For Magellan Aerospace Stock
- Magellan Aerospace has seen fresh investor attention after recent commentary linked the business to stronger aircraft production programs and defence procurement, putting its capital intensive operations and long duration contracts back in focus.
- The key thread is whether Magellan Aerospace can translate this expected program demand into reliable free cash flow, given its bigger working capital needs, automation projects and the long cycle nature of its aerospace and defence work.
- We will now look at how Magellan Aerospace's investment narrative could be shaped by optimism around aircraft production and defence demand.
Scan for other aerospace and defence suppliers with similar long cycle cash flow stories by checking the hand picked list of solid balance sheet and fundamentals (8 results) that may be better positioned to withstand capital intensive programs and order swings.
Magellan Aerospace Investment Narrative Recap
To own Magellan Aerospace, you need to believe its long cycle contracts in engines, aerostructures and defence can be turned into steady free cash flow, despite heavy capital spending and higher inventory. The recent share price pop on aircraft and defence optimism does not change that core question. It simply raises the bar on execution.
In the near term, the key catalyst is how cleanly the business converts that strong order backdrop into cash, given elevated working capital and the ongoing automation and facility projects. The biggest risk is that inventory and capex stay high while program margins or volumes lag, which could leave free cash flow tight.
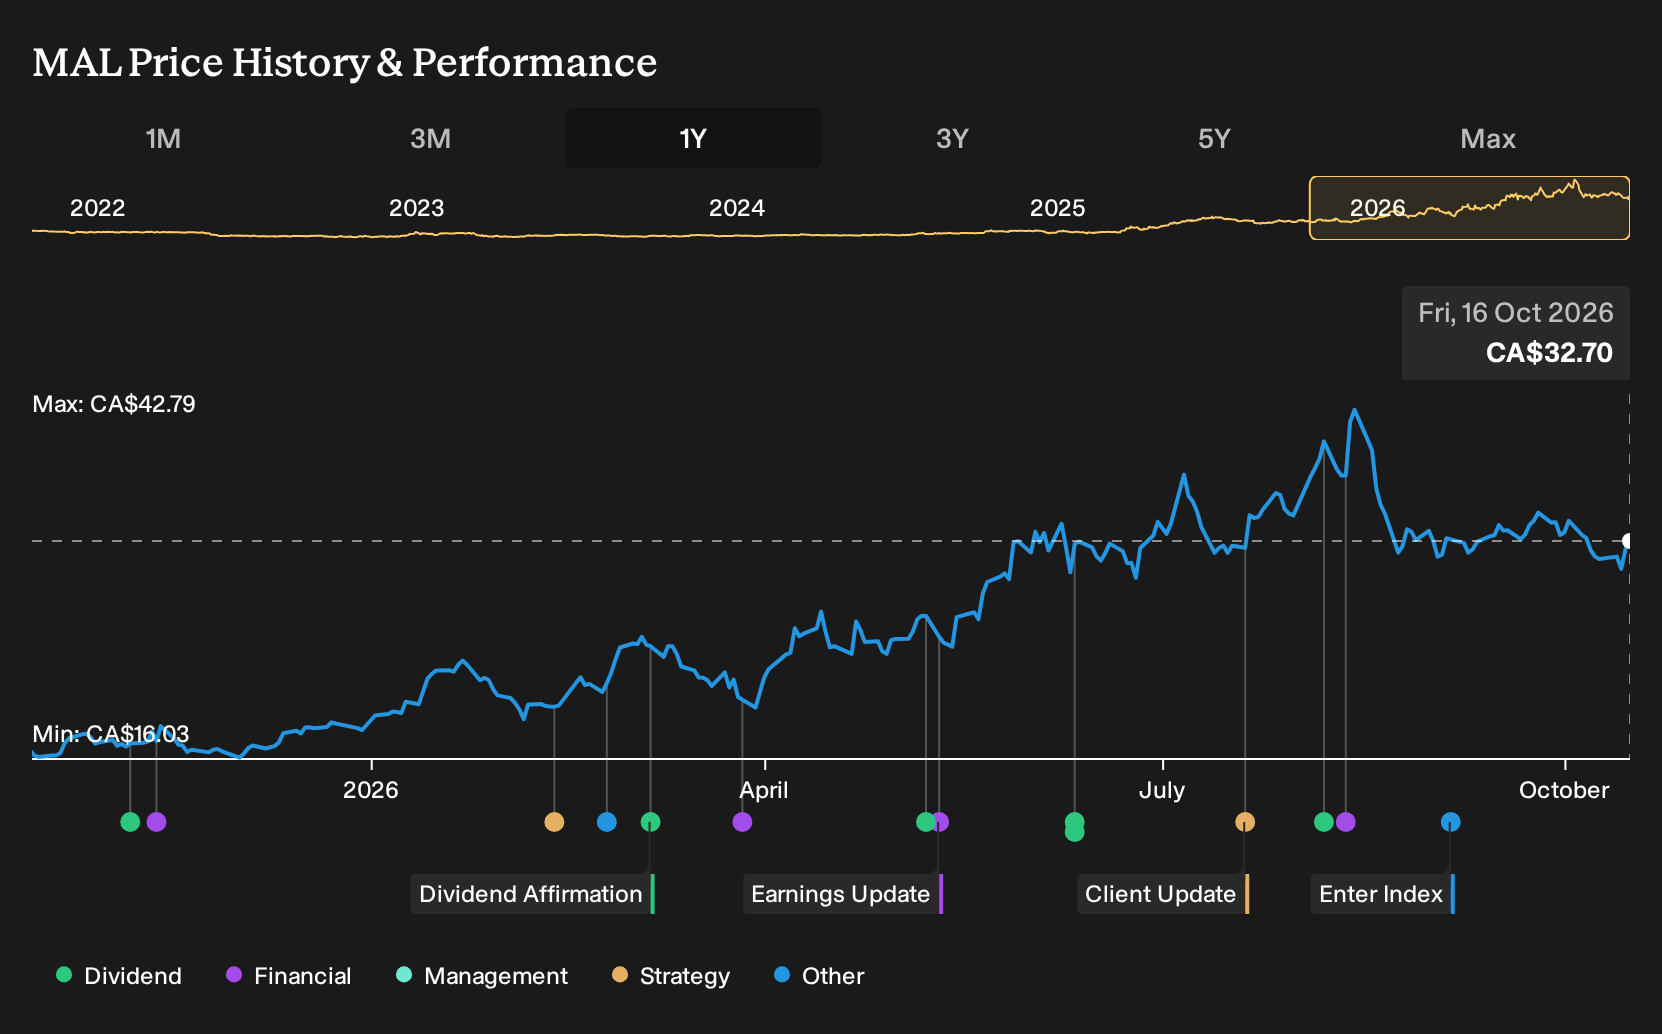
The recent 5.07% move on 15 October 2026 matters mainly because it ties directly to that operational test. Stronger aircraft build rates and defence procurement only help Magellan Aerospace if the higher volumes flow through its CAD 1.3b of contracts into better capacity utilization, disciplined pricing and fewer schedule hiccups.
Without fresh formal announcements, the most relevant context is the planned CA$51m of 2025 capital projects across automation, technology and facilities. Those investments sit at the intersection of the current optimism and the main risk. If execution keeps disruption controlled and unit costs in check, they can support the cash conversion story investors are watching.
Magellan Aerospace's current earnings of CA$59.6 million are forecast to reach CA$126.8 million by 2029, with analysts assuming yearly revenue growth of 7.3% and projecting revenues of CA$1.4 billion and earnings of CA$126.8 million in that same year. This implies roughly a 2.1x increase in earnings from today.
Discover why Magellan Aerospace's fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between CA$37.88 and CA$45.67, which already suggests some investors saw Magellan Aerospace as materially mispriced before the mid October share move. Consider those opinions in light of execution risks around inventory, Chapter 11 uncertainty and the scale of 2025 capex, then explore several alternative viewpoints.
Explore 2 other Magellan Aerospace fair value estimates, including one that suggests potential upside of up to 40% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Magellan Aerospace research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Magellan Aerospace. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magellan Aerospace's overall financial health at a glance.
Looking For More Investment Ideas Beyond Magellan Aerospace?
If the Magellan Aerospace story has sharpened your focus on cash generation and balance sheet strength, it can help to widen the lens and compare it with other listed businesses that share similar financial traits, but with different risk profiles and income angles.
- For investors who want potential upside backed by fundamentals rather than hype, consider scanning a curated set of 10 high quality undiscovered gems that pair solid financial quality with lower market attention.
- If stability and capital preservation sit high on your list, filter for companies with stronger finances and lower risk scores through a focused 8 resilient stocks with low risk scores that emphasises resilience over excitement.
- For readers who care most about robust balance sheets and the capacity to handle heavy investment cycles, compare Magellan Aerospace with a broader list of solid balance sheet and fundamentals (8 results) that highlights businesses with cleaner leverage and funding positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com