


WillScot Holdings (WSC) Could Be 39% Below Fair Value As Q3 Beat Expectations Build
Board refresh and earnings expectations converge at WillScot Holdings
WillScot Holdings (WSC) just paired a boardroom refresh with market expectations for a modest Q3 earnings beat, giving investors fresh governance context as they weigh the stock’s recent share price weakness.
Recent performance has been tough for WillScot Holdings, with the share price down 39.13% over the past 90 days and 18.44% year to date, while the 1-year total shareholder return declined 23.89%. This points to fading momentum despite raised guidance and expectations for a modest Q3 earnings beat.
Compare WillScot Holdings with other beaten-down industrials that still screen well on quality and balance sheet strength by scanning our hand-picked 32 resilient stocks with low risk scores today.
After a drop of almost 40% in three months, the question around WillScot Holdings has flipped. Is most of the pain now priced in, or has much of the upside already been pulled forward by earlier enthusiasm on guidance and earnings beats?
Most Popular Narrative: 39% Undervalued
On the most followed view, WillScot Holdings is priced well below an implied fair value of $26.20, with that gap depending on whether margin repair and large modular projects translate into stronger earnings than the current share price implies.
Growing modular pending orders, up in a 13% to 17% range year over year with a large and mega project pipeline that extends into 2027 and includes data centers, power generation and manufacturing, point to future leasing revenue that the market may not be fully pricing into WillScot Holdings yet.
See why 5 investors see WillScot Holdings as 39% undervalued.
Result: Fair Value of $26.20 (UNDERVALUED)
Still, WillScot Holdings faces real pressure if portable storage weakness and compressed adjusted EBITDA margins persist longer than expected and continue to weigh on earnings power.
Find out about the key risks to this WillScot Holdings narrative.
Another View: What WillScot’s P/S Ratio Is Signalling
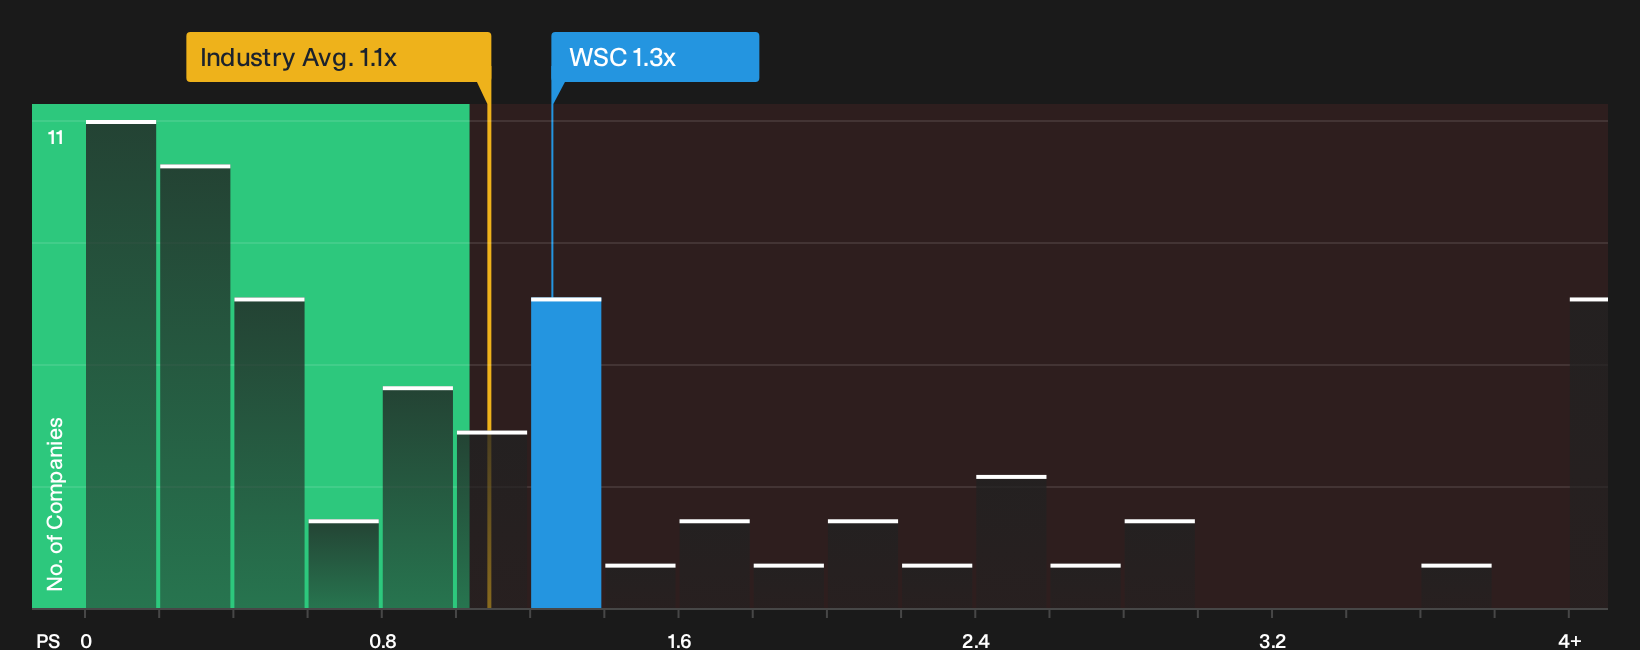
The discounted cash flow output points to WillScot Holdings trading below an estimated future cash flow value of $24.14, which aligns with the idea of undervaluation. The P/S picture is less comfortable. At 1.3x sales, the shares trade above both peers at 0.9x and the US Construction average of 1.1x, yet below an estimated fair ratio of 2.3x. That mix of downside risk if sentiment stays weak and potential upside if the market moves toward the fair ratio leaves you asking which scenario feels more realistic.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on WillScot Holdings after all that? Take a close look at the full data set, pressure test both sides of the story, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WillScot Holdings?
If WillScot Holdings has your attention but you want a wider watchlist, use the Simply Wall St Screener to surface fresh, data-backed ideas before others do.
- Target rock-solid balance sheets and fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that can help anchor a more resilient portfolio.
- Hunt for potential mispricings by tracking companies in our 33 high quality undervalued stocks that pair quality metrics with valuations that still look compressed.
- Spot under-the-radar opportunities early through our 20 high quality undiscovered gems before they attract broader market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com