


Paylocity Holding (PCTY) Could Be 3% Undervalued After Insider Stock Sales
Insider activity has moved into focus at Paylocity Holding (PCTY) after two senior insiders reported multi million dollar stock sales on October 15, 2026, in newly filed SEC disclosures.
At a share price of US$166.32, Paylocity Holding has shown strong short term momentum, with a 30 day share price return of 15.7% and a 90 day move of 30.7%, even though the 5 year total shareholder return is down 43.5%. This points to sentiment improving recently, but from a weak longer term base.
Spot fresh momentum stories like Paylocity Holding by scanning our hand picked list of 33 high quality undervalued stocks with improving sentiment and solid underlying fundamentals.Paylocity Holding now looks like a resilient software business whose shares have suddenly caught a second wind. After that rebound and fresh insider sales, an important question for investors is whether the current price still lines up with what the cash flows suggest.
Most Popular Narrative: 3% Undervalued
The most followed narrative on Paylocity Holding pegs fair value at $172.00, slightly above the last close at $166.32. This frames insider selling against a model that still sees some upside based on future cash flows.
Expansion of Paylocity Holding’s unified HR, finance and IT platform with embedded AI agents such as Ignite AI and the AI assistant, along with planned premium SKUs tied to tools like Grayscale and Aidora, is set up to convert rising AI usage into higher recurring revenue and average revenue per client over time, which can support earnings growth.
See why 11 investors see Paylocity Holding as 3% undervalued.
Result: Fair Value of $172.00 (UNDERVALUED)
Still, the narrative around Paylocity Holding can crack if slower projected revenue growth near 7% and softer recurring revenue momentum continue to pressure how investors value the stock.
Find out about the key risks to this Paylocity Holding narrative.
Another View: Paylocity Holding Through Earnings Multiples
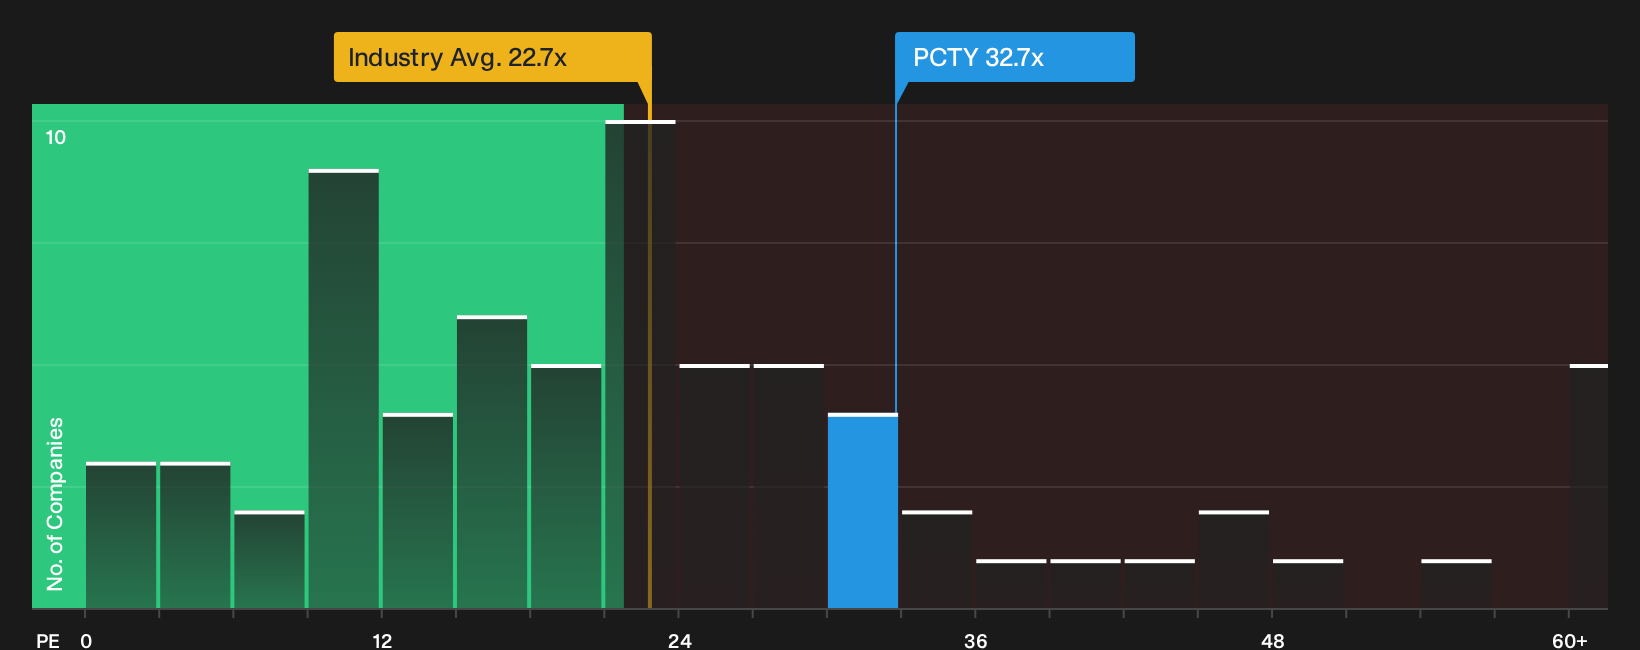
The DCF narrative paints Paylocity Holding as undervalued, yet the P/E picture is far less forgiving. At 32.7x earnings versus a fair ratio of 20.5x, the stock trades on a much richer multiple than both the US Professional Services industry at 22.7x and peers at 16.7x. That gap can compress if expectations cool, so how comfortable are you with paying this kind of premium for the story on future cash flows?
For a closer look at how this earnings multiple stacks up against the market and peers, and what that might mean for valuation risk if sentiment changes, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Paylocity Holding so far. If you want to move quicker than the next headline and build your own view from the ground up, start by weighing its 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paylocity Holding?
Do not stop with Paylocity Holding alone. Fresh watchlist candidates can sharpen your thinking, stress test your thesis, and help you spot better risk reward setups early.
- Target resilient balance sheets and steadier cash profiles by reviewing our list of solid balance sheet and fundamentals (25 results) and see which businesses may better match your risk tolerance.
- Hunt for mispriced opportunities by scanning the 33 high quality undervalued stocks that pair stronger fundamentals with what our models flag as discounted valuations.
- Prioritise steady income potential and cash returns by checking the 8 dividend fortresses that combine higher yields with a focus on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com