


Sonic Automotive (SAH) Draws Fresh Valuation Focus, Is The Stock Cheap Or Pricey?
Sonic Automotive (SAH) has attracted fresh attention after its share price moved to US$63.61, with recent returns mixed over the month and the past 3 months. Investors are reassessing what this level implies.
Recent share price moves hint at a shift in sentiment, with Sonic Automotive posting a 5.0% 7-day share price return but a much weaker 90-day share price return that is down 34%. However, the 3-year total shareholder return of 49.3% still reflects a stronger longer-run outcome.
Scan how Sonic Automotive stacks up against other car retail players by running through our hand picked list of solid balance sheet and fundamentals (25 results) before you decide where the real opportunity sits.
Sonic Automotive now trades at US$63.61 while analyst targets and intrinsic value estimates point higher and lower. Does this recent swing leave the stock stretched, cheap, or somewhere in between on fair value?
Most Popular Narrative: 28% Undervalued
The most followed narrative puts Sonic Automotive's fair value at $88.91, well above the last close at $63.61, which pulls attention straight to what is driving that gap.
The focus on growing fixed operations and F&I, which together accounted for more than 75% of total gross profit in Q1 and Q2 2026 and delivered record fixed operations gross profit of US$263.8 million in Q2, underpins a mix shift toward higher-margin, recurring revenue that can support net margins and earnings.
See why 3 investors see Sonic Automotive as 28% undervalued.
Result: Fair Value of $88.91 (UNDERVALUED)
Still, Sonic Automotive's story is not bulletproof, with affordability pressures and EchoPark gross profit per unit compression both potential spoilers for the bullish narrative.
Find out about the key risks to this Sonic Automotive narrative.
Another View: Our DCF Model Says Overvalued
The analyst narrative suggests Sonic Automotive is 28% undervalued at $88.91, yet the Simply Wall St DCF model indicates a different outcome. On that cash flow view, fair value sits at $54.46, which would place the current $63.61 price above intrinsic value and alter the risk reward balance.
The gap between the analyst target and a lower DCF estimate leaves you with a simple question: which set of assumptions on margins, reinvestment and discount rate appears closer to how Sonic Automotive will actually run its business over time?
To see how that cash flow view is built line by line, and how sensitive it is to different assumptions, Look into how the SWS DCF model arrives at its fair value.
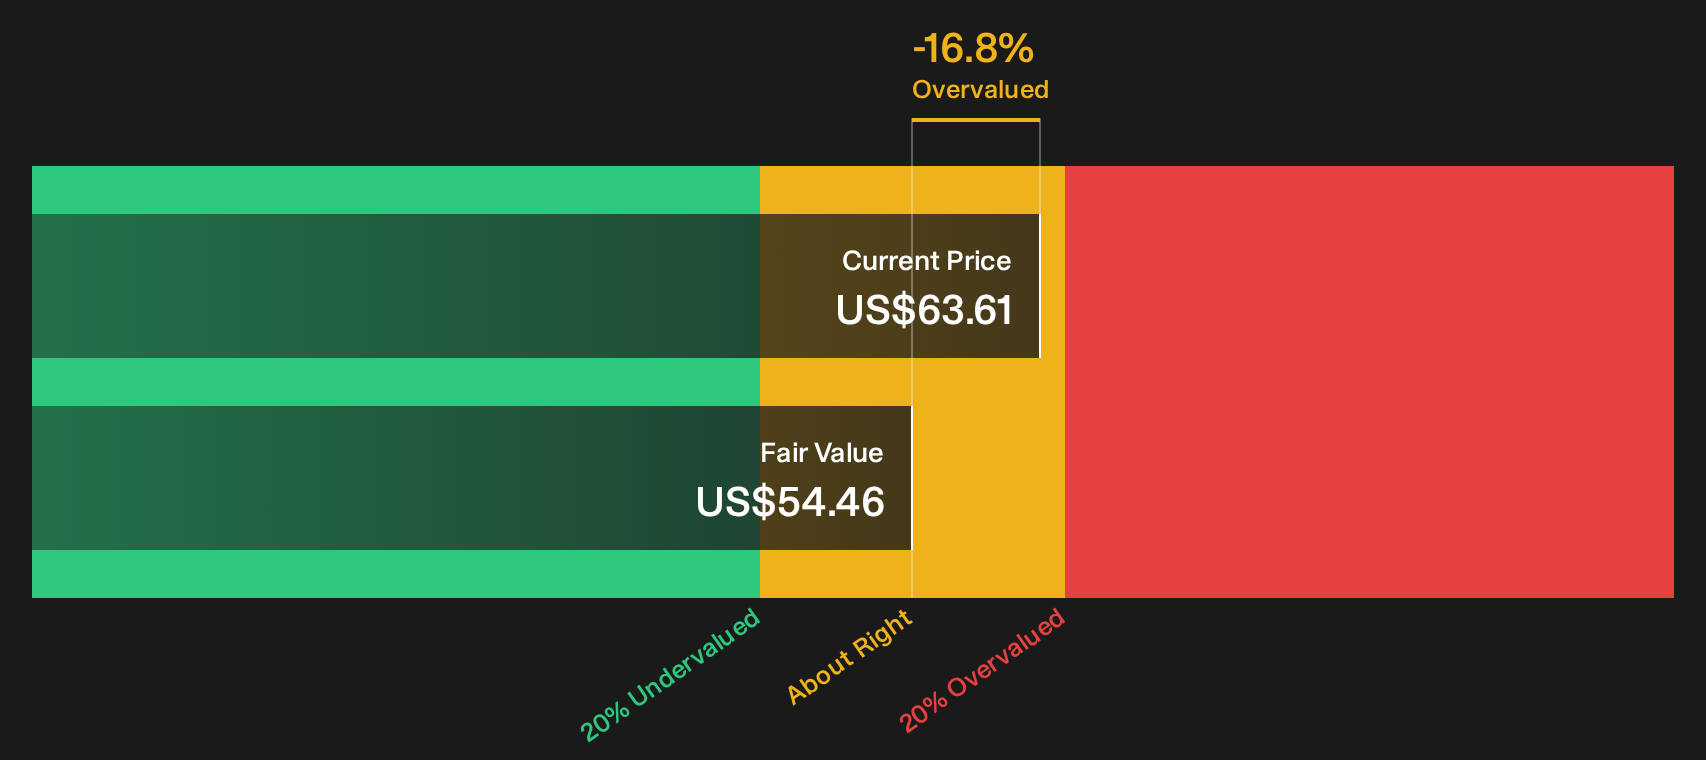
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sonic Automotive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sonic Automotive's value can pull sentiment in opposite directions, so it may be useful to act in a timely manner, review the full picture yourself, and weigh up the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Sonic Automotive?
If Sonic Automotive has sharpened your view on value, do not stop here. Use focused screeners to spot other opportunities that fit your checklist.
- Target potential upside in quality businesses trading below implied worth by running a focused search with the 33 high quality undervalued stocks.
- Prioritise resilience and capital protection by scanning companies that clear strict risk filters using the 32 resilient stocks with low risk scores.
- Hunt for emerging opportunities with solid fundamentals before wider attention catches up by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com