


Does Veracyte (VCYT) Trade At A Discount To Future Cash Flow?
Veracyte has produced a strong multi year share price run, and recent Medicare reimbursement news has sharpened the question of whether the current valuation still lines up with the cash the business can generate. With the stock last closing at US$43.12, investors are asking how much of the company’s future cash flows are already reflected in that price.
- Over the past three years, Veracyte has delivered a total return of about 106.0%, which puts real pressure on the cash flow outlook to justify the journey so far.
- The recent Medicare coverage decision for the Prosigna Breast Risk of Recurrence test may support expectations for broader test adoption and could influence how steadily Veracyte converts its genomics platform into future cash flows.
- What if you looked at Veracyte through its earnings instead? See why Veracyte's 30.3x P/E tells a different valuation story.
For investors, the discussion is whether Veracyte's current share price is appropriately grounded in the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you are weighing Veracyte against other genomics and healthcare cash flow stories, a simple next step is to line it up beside 33 healthcare AI stocks
Does Veracyte Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Veracyte can return to shareholders over time rather than near term earnings swings. On this view, the group generated last twelve month free cash flow of about $165.9 million, and the projections assume that free cash flow grows further into the next decade rather than shrinking or flatlining.
Analysts supplying the inputs expect Veracyte to lift annual free cash flow into the low to mid $200 million range by 2030, with growth easing into a steadier phase after that. The DCF outcome sits substantially above the current share price of US$43.12, which indicates the market price does not fully mirror those long range cash flow estimates. Because Medicare has now agreed to reimburse the Prosigna Breast Risk of Recurrence test, that new coverage helps explain why some investors may see more support behind the longer term cash generation story than the price currently implies. Find out what Veracyte could be worth using our Discounted Cash Flow (DCF) estimate.
The Veracyte Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Veracyte pick up where the DCF puzzle leaves off and explain what kind of future for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than today's price. All of this is available on the Community page. Rather than a single output from one model, each narrative lays out the assumptions that support its view of fair value so you can compare those assumptions with actual results as they are reported.
One of the top community narratives on Veracyte: 24% undervalued
"Expanding cancer diagnostics portfolio and clinical evidence are driving greater physician adoption, market penetration, and long-term top-line growth..."
Discover why this Narrative puts Veracyte at 24% undervalued.
One more Veracyte question the valuation does not answer
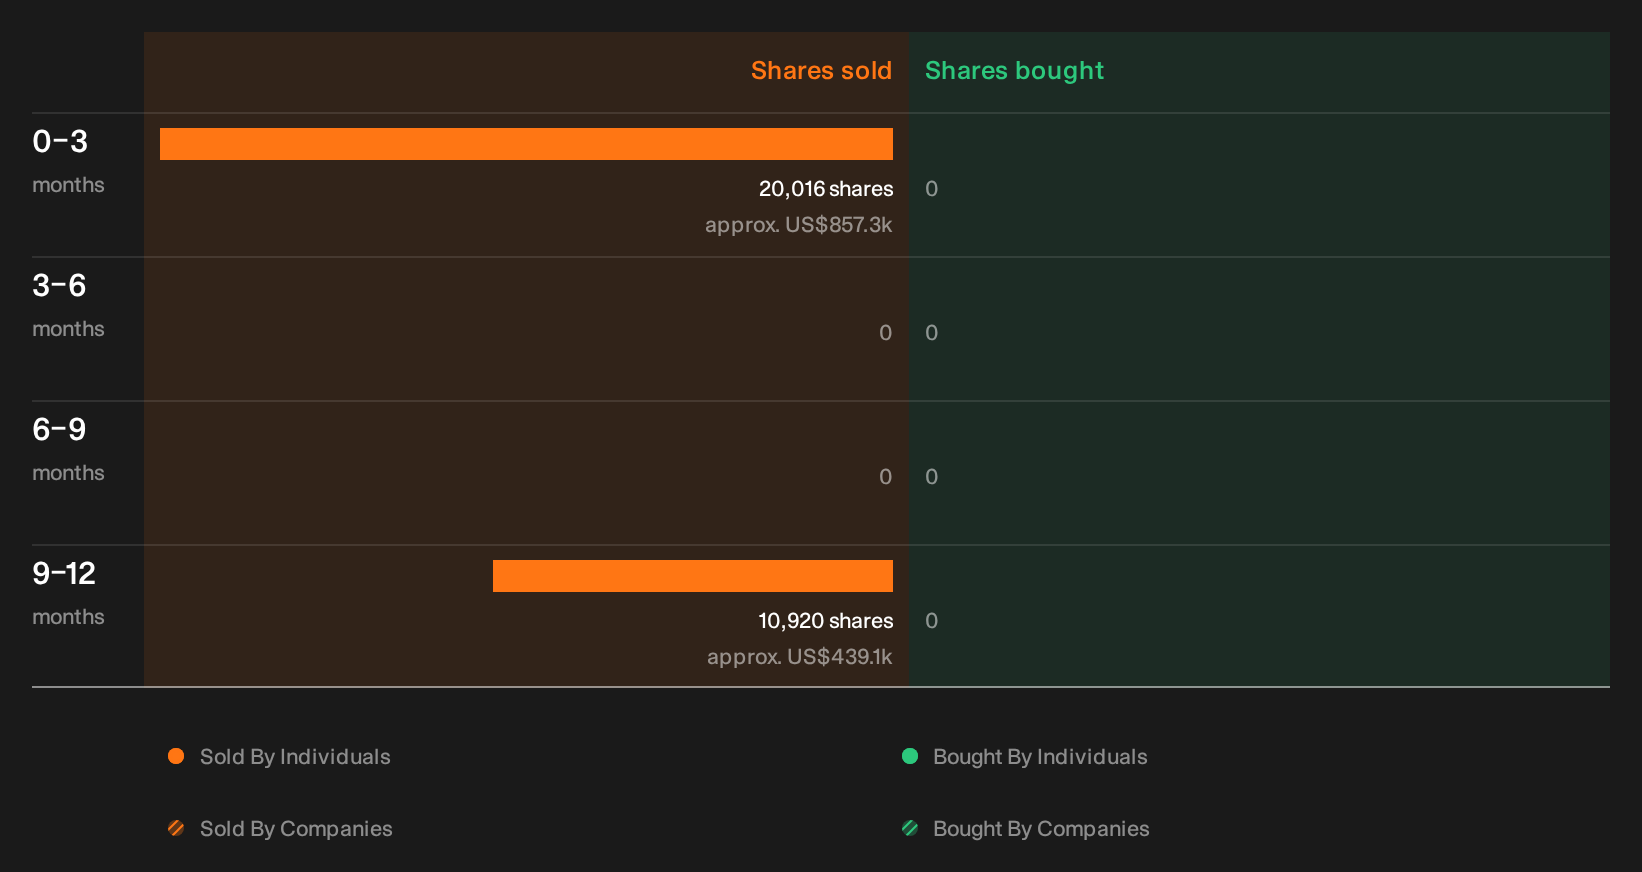
Price targets and cash flow models only tell part of the story for Veracyte, because recent trades by people inside the business add a separate line of inquiry that readers may want to unpack for themselves. See the recent insider selling flagged for Veracyte.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com