


Cohen & Steers (CNS) Could Be 9% Undervalued After Inflows And Revenue Beat
Cohen & Steers (CNS) just logged a fifth straight quarter of organic net inflows, with Q3 revenue topping expectations as 74% of assets under management outperformed and active ETF products gained traction.
Cohen & Steers’ share price has slipped 5.6% over the past month and 15.6% over the past quarter, even as the year-to-date share price return sits at 9.5% and the 3-year total shareholder return of 48.2% points to longer term momentum that contrasts with the recent pullback.
Compare Cohen & Steers’ real assets focus with other potential opportunities by scanning our hand-picked list of 33 high quality undervalued stocks that combine stronger balance sheets with disciplined cash generation.
Cohen & Steers is putting up solid flow and earnings numbers while the share price has stepped back sharply in recent months. That raises a key question for investors: Is a strong franchise now offered at a reasonable valuation?
Most Popular Narrative: 9% Undervalued
Cohen & Steers last closed at $69.63, compared with a widely followed narrative fair value of about $76.33 that is built from detailed earnings and cash flow assumptions.
The current valuation implies that Cohen & Steers is priced for a fairly valued but bullish outcome in which fee rates remain solid, real assets performance holds up, and the business continues to convert growing AUM into stable profitability.
See why 4 investors see Cohen & Steers as 9% undervalued.
Result: Fair Value of $76.33 (UNDERVALUED)
Still, this hinges on real assets staying in favor and on Cohen & Steers keeping institutional inflows intact, since weaker demand or renewed outflows could quickly challenge that story.
Find out about the key risks to this Cohen & Steers narrative.
Another View: Cohen & Steers On Earnings Multiples
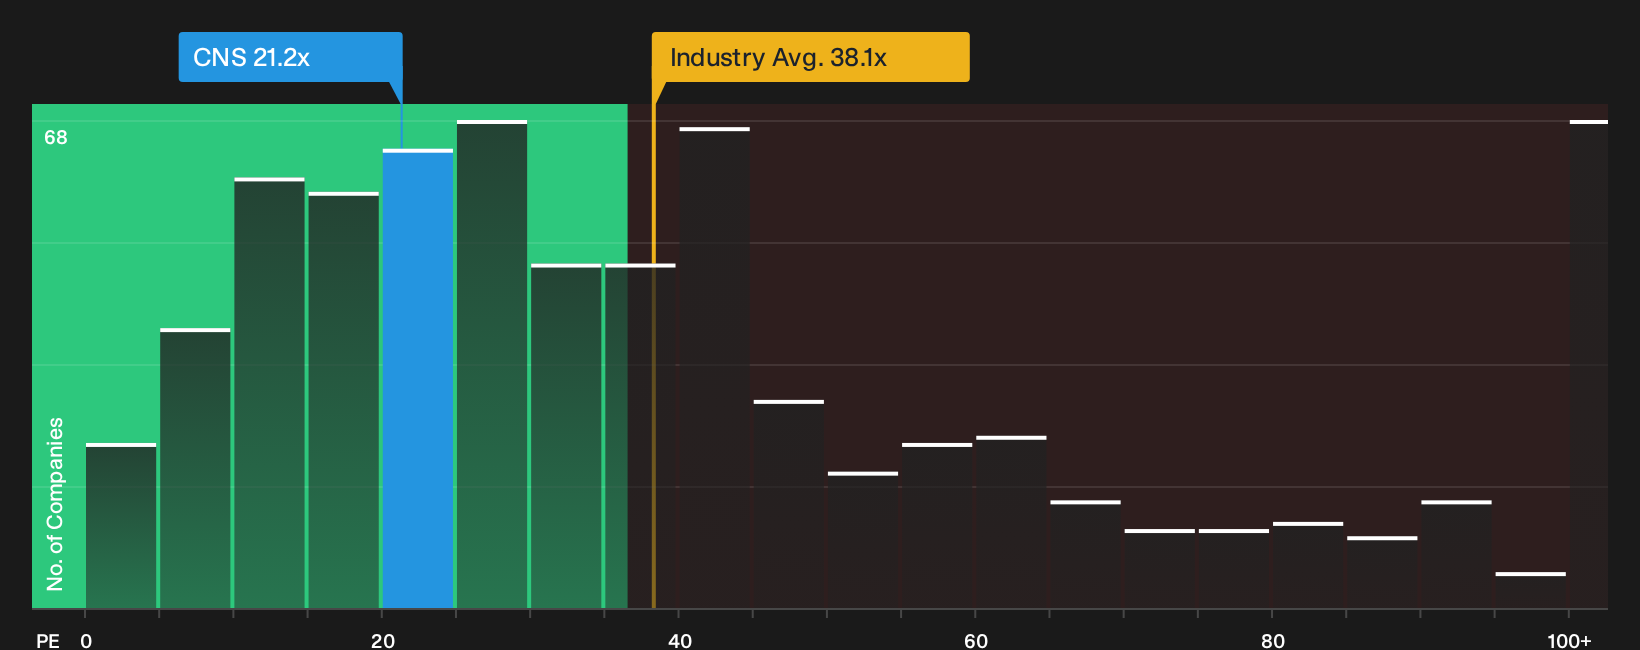
The DCF based fair value narrative suggests Cohen & Steers is about 9% undervalued at $76.33. A simple P/E check tells a more cautious story. The stock trades on 21.2x earnings, which is well above its own fair ratio of 11.6x and ahead of a 15.2x peer average.
Compared with the wider US Capital Markets group at 38.1x, CNS appears cheaper; however, the gap to its fair ratio points to valuation risk if sentiment cools. That raises a practical question: is the main story a modest discount to DCF fair value, or a premium earnings multiple relative to closer peers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on Cohen & Steers so far. If you want to move quickly and ground your own stance in the details, start by weighing 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Cohen & Steers?
If Cohen & Steers has sharpened your focus, do not stop here. Broaden your watchlist now so you are not chasing the next move after it already happens.
- Target reliable income by scanning 8 dividend fortresses that aim to pair robust yields with more durable payout histories.
- Hunt for quality at a discount through our hand picked 20 high quality undiscovered gems that blend solid fundamentals with lighter market attention.
- Reduce portfolio stress by reviewing a 32 resilient stocks with low risk scores that screens for sturdier balance sheets and milder volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com