


Did Executive Succession Plans Just Shift Byline Bancorp Stock's Investment Narrative?
- Byline Bancorp announced that long-serving executives Brogan Ptacin and Mark Fucinato will retire at the end of 2026, with Sean McGuire, Scott Hawthorne and Darrin Bacon promoted to executive leadership roles from January 2027.
- The creation of a Chief Commercial Banking Officer role and internal promotions highlight a focus on continuity in credit discipline and commercial client coverage as Byline Bancorp prepares for its next phase of growth.
- We will now examine how Byline Bancorp's leadership succession, including the new Chief Commercial Banking Officer role, could influence its investment narrative.
Byline Bancorp Investment Narrative Recap
To own Byline Bancorp, you need to be comfortable with a Midwest focused commercial lender that leans heavily on cost efficiency, disciplined credit and core deposits to support earnings. The short term swing factor is still how cleanly it manages growth around the US$10b asset threshold, where higher regulatory costs and Durbin limits start to bite.
The leadership shuffle into 2027 looks more evolutionary than disruptive, so it does not materially change that near term catalyst. The bigger risk remains a tougher Chicago or regional economy combined with intense competition for loans and deposits, which could pressure net interest income and dilute the current efficiency story.
The creation of the Chief Commercial Banking Officer position is the announcement that ties most directly to this leadership news. Sean McGuire will oversee a broader commercial platform that includes C&I lending, leasing and treasury services, areas analysts already link to loan growth and fee based income as key earnings drivers for Byline Bancorp.
Execution in this expanded role will matter if management wants to support organic loan production while keeping funding anchored in relationship deposits. That same structure also needs to absorb any future M&A and the step up in compliance costs as assets move above US$10b, without letting the efficiency ratio drift away from the recent mid 40% level.
Byline Bancorp's current analyst narrative points to revenue of US$523.8 million and earnings of US$159.5 million by 2029, based on forecast revenue growth of 6.4% per year and an earnings increase of about US$10 million from US$149.5 million today.
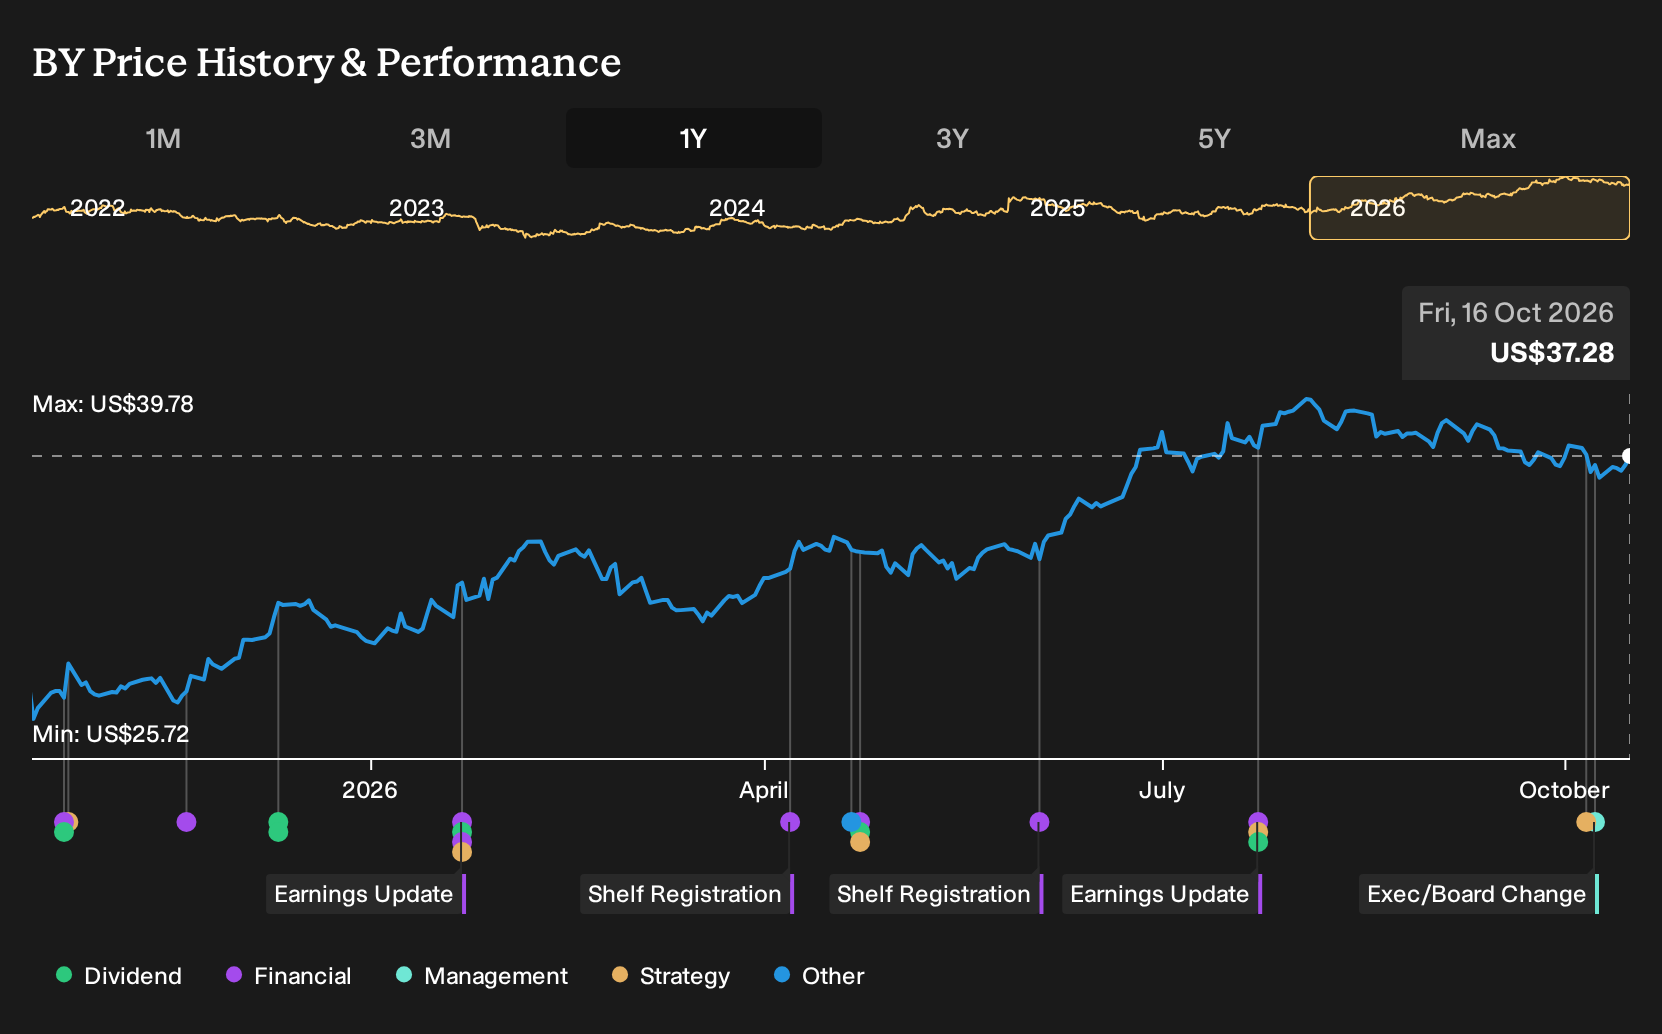
Uncover why Byline Bancorp's fair value indicates a 16% potential upside to its current price, a discount that could close relatively quickly.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Byline Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Byline Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Byline Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond Byline Bancorp?
If the Byline Bancorp story has you thinking about portfolio upgrades, use the Simply Wall St Screener to find other companies with qualities that fit your own checklist rather than someone else’s.
- For investors who want income to be front and center, focus on businesses offering durable cash returns by scanning 8 dividend fortresses.
- If capital preservation and consistency matter most to you, begin with companies that score well on stability metrics by checking out 32 resilient stocks with low risk scores.
- When you are looking for quality that has not yet drawn broad attention, broaden your research with 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com