


What Comes Next For OMV After An 80% Gain
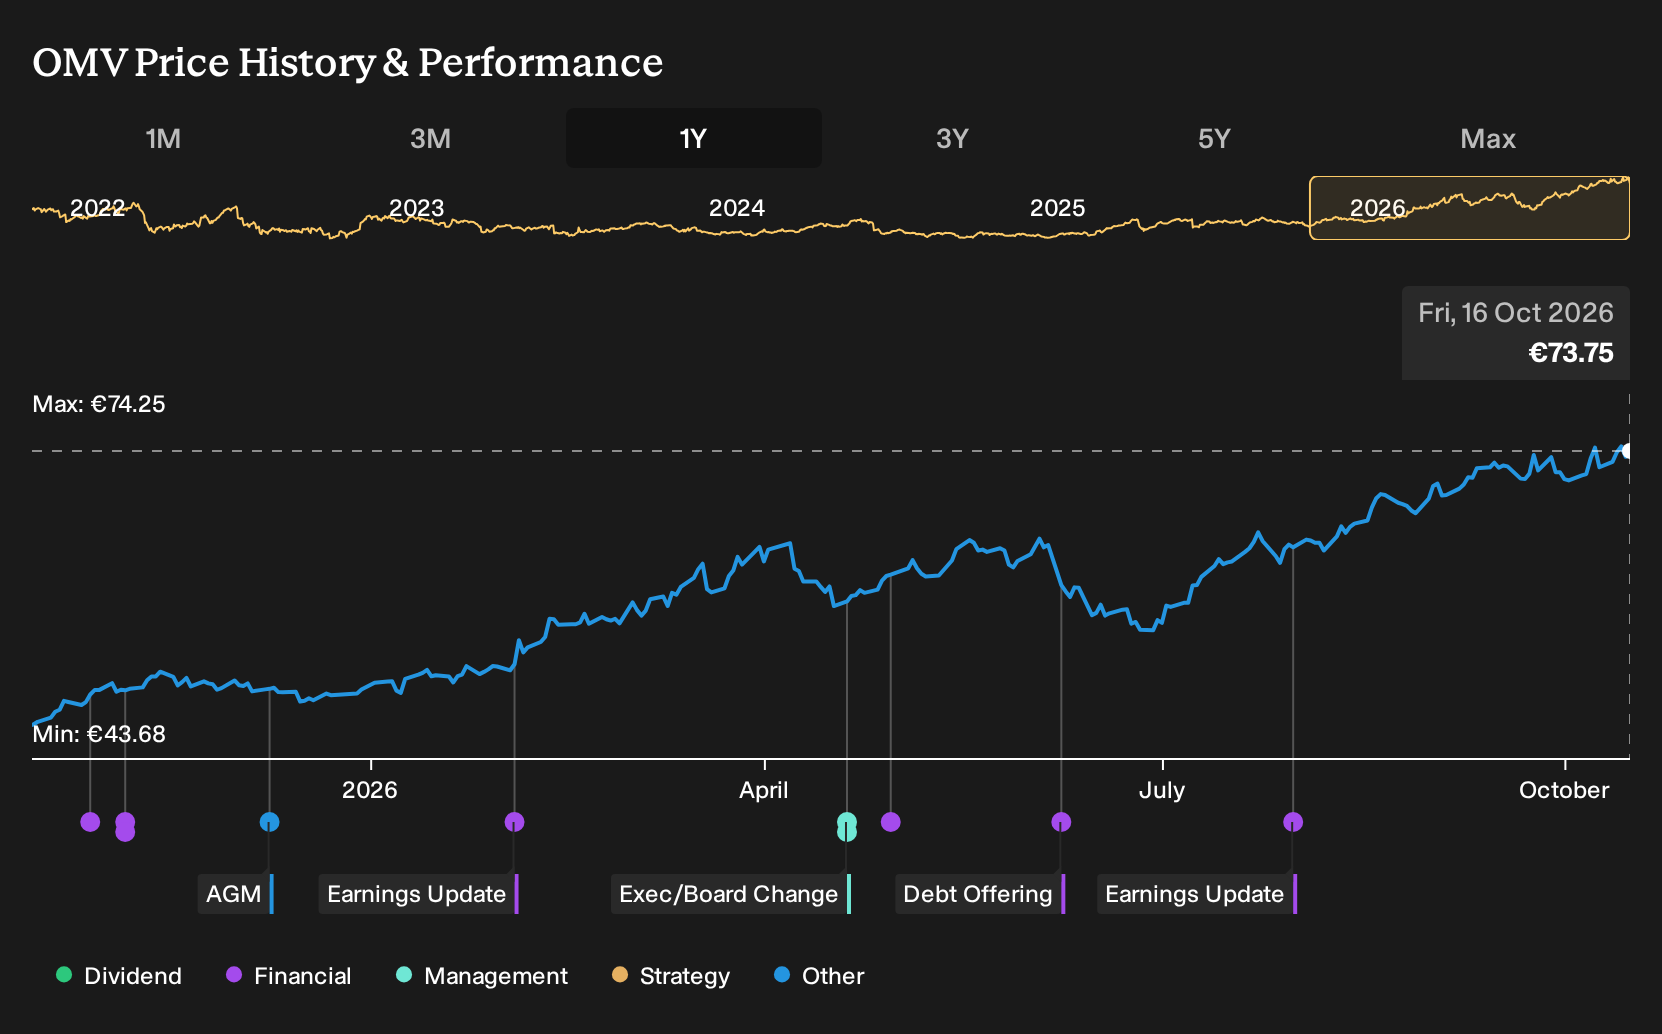
If you only skimmed headlines about OMV’s decarbonization push and production cuts, the past year might look like a coin toss between green hydrogen ambition and fossil fuel risk. Holding OMV over the past year would have returned 80.2%, including dividends. If you had been weighing that decision back in October 2025, what did the clash between bullish expansion plans and decarbonization headwinds really signal about the potential direction of this business?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
OMV has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On OMV
The shares cost €43.68 at the start of the period, and OMV sat between two sharply different stories about where decarbonization might leave a traditional energy and chemicals group.
On the bullish side, the Fair Value sat at €62.5, based on the idea that green hydrogen, the 140 megawatt electrolyzer project, and the BGI merger synergies could influence revenue, margins, and long term earnings power.
The bearish view put Fair Value at €40, emphasizing that faster decarbonization policies could affect long run oil and gas demand and leave OMV with pressured core revenue streams and potential stranded assets.
What The Evidence Around OMV Actually Tested
The €450 million EIB loan for OMV’s 140 MW green hydrogen plant backed the optimistic case that decarbonization projects could matter for long term earnings power. At the same time, OMV cut its 2026 production forecast as Middle East conflict affected crude supply, which supported the cautious view on hydrocarbon risk. Overall, the evidence cut both ways.
The core assumption here was not just “energy transition” but whether low carbon projects would offset fossil exposure. For any other integrated producer, track how new hydrogen, SAF or geothermal capacity aligns with production guidance and net margin in reported results.
What OMV’s 80% Run-Up Already Prices In
OMV now trades at €73.75. The selected Narrative sees Fair Value below that level, arguing that the current quote already bakes in meaningful progress on cleaner fuels, recycling, and a broader petrochemicals mix alongside traditional hydrocarbons.
To justify paying today’s price, a buyer needs confidence that transition projects deliver on time and on budget despite execution, cost, and regulatory risks.
"OMV's diversified expansion in gas, petrochemicals, and specialty products strengthens revenue stability and cushions earnings from energy market volatility. Investments in renewables, recycling, and international partnerships support long-term profitability and reduce exposure to regulatory and market risks."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where OMV’s Question Leads Next
OMV works on cleaner fuels. Your attention can also follow the power those fuels support.
Every refinery, cracker, and chemical plant needs steady electricity to stay online. AI data centers and electrified transport require similar stability at different grid points.
One specialist manufacturer concentrates on making that electricity dependable. It builds and services hardware that keeps large gas units operating and grids tuned for heavy digital loads.
Long service contracts and grid upgrades can turn old equipment sales into recurring energy infrastructure work. That shift in how power is maintained might matter as OMV’s transition unfolds.
One Narrative has put that dependency into a written case. → See the power-grid company one Narrative values 38% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com