


Why Equinor Doubters Were Wrong Before A 95% Gain
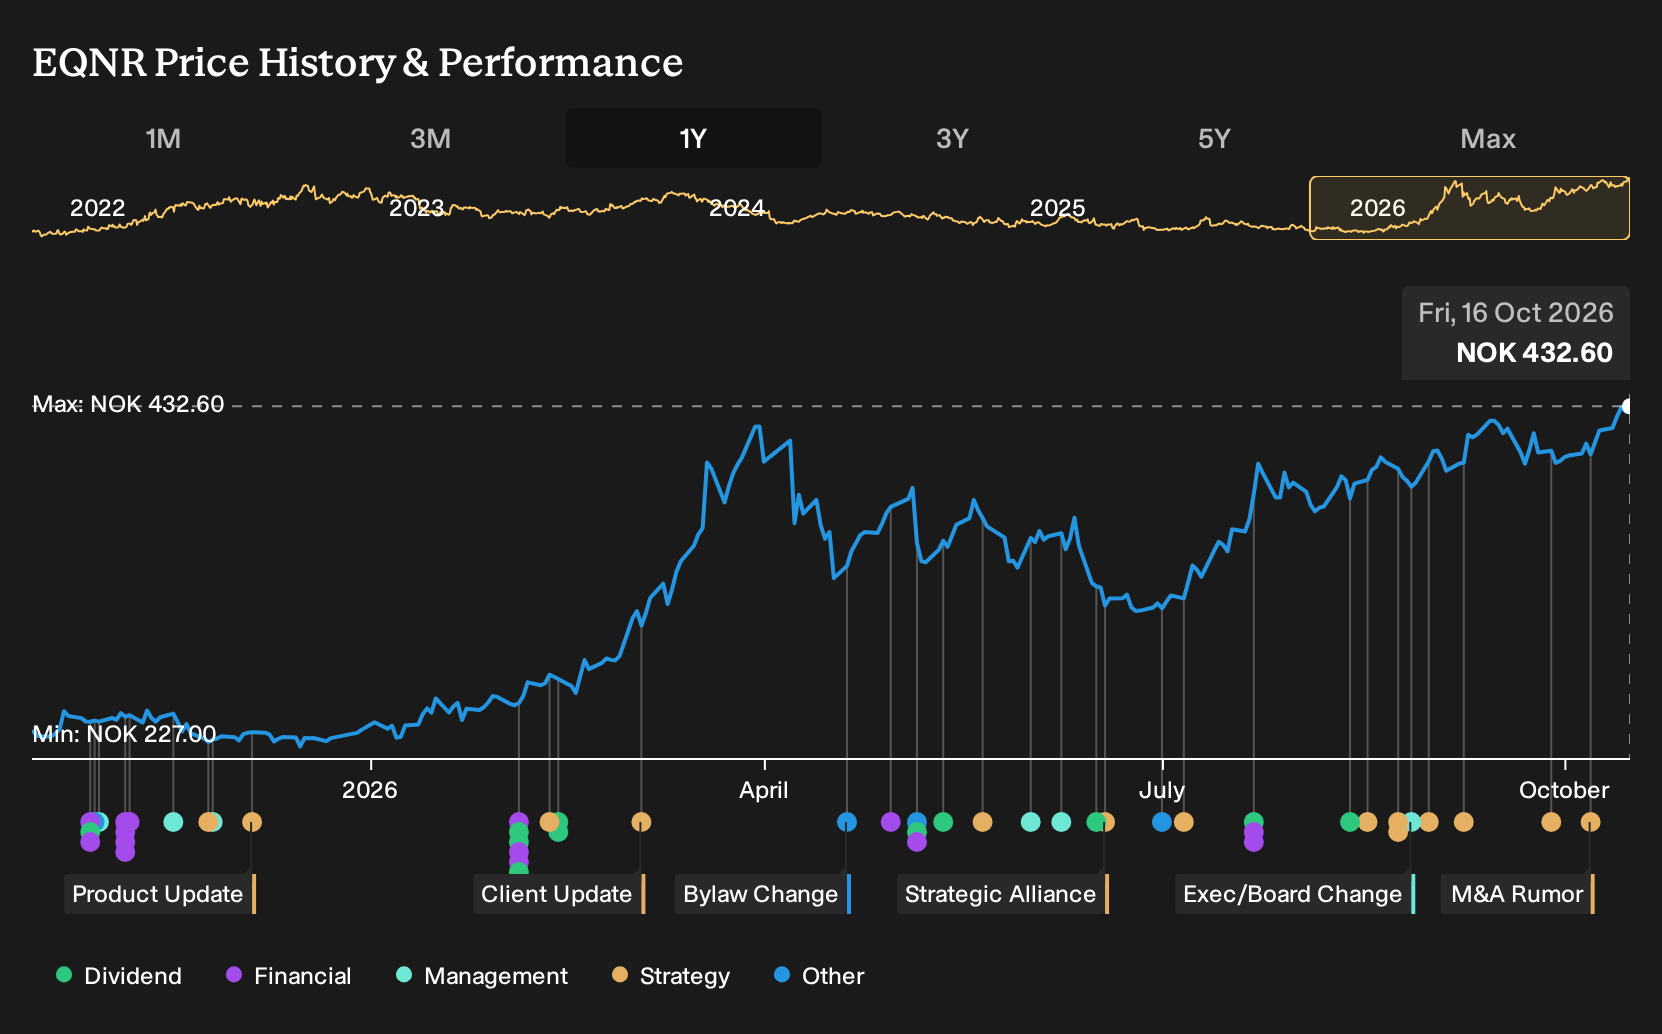
Holding Equinor over the past year would have returned 94.6%, including dividends. That result invites a simple question with a harder answer. If you had been weighing Equinor on 16 October 2025, with one camp arguing that rapid decarbonization would erode oil and gas cash flows and another emphasizing long-term gas contracts, Norwegian shelf projects and rising buybacks, which side of that split would have felt more convincing before any of this played out?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind Equinor. Zero in on 191 high quality undervalued stocks for companies trading below our estimates.
The Two Equinor Stories Investors Had To Weigh
The shares cost NOK236 at the start of the period, and anyone looking at Equinor then had to choose between two sharply different stories that both sounded plausible.
The bullish Narrative put Fair Value at NOK250, only 6% above the start price. It assumed revenue would decline 5.5% a year with profit margins settling near 8.5%, supported by long-term gas contracts, Norwegian shelf projects and ongoing buybacks.
The bearish Narrative set Fair Value at NOK184, which was 22% below the start price. It focused on the risk that faster climate policy and renewables adoption would reduce oil and gas demand and leave legacy upstream assets exposed.
What The Results Put To The Test For Equinor
Equinor reported Q2 2026 revenue of US$34,523m and net income of US$4,848m, with net margin rising to 14.0%. That outcome leaned toward the bullish case built on resilient cash generation from oil and gas projects and long-term contracts, rather than the bearish view that decarbonization would quickly erode profitability.
The lesson is simple. When a thesis hangs on whether legacy assets will throw off cash for years, track net margin and absolute profit in each report and test if they line up with the story you are buying.
What Equinor’s 1 Year Run Already Prices In
Equinor now trades at NOK433 after a 94.6% gain over the past year. The selected Narrative’s Fair Value sits below that level, which frames today’s quote as demanding rather than cheap.
The Narrative leans on stable gas contracts, project delivery and renewables returns. Investors would need to judge whether large offshore wind projects can be executed without persistent cost surprises.
"Equinor faces heightened execution risks and potential cost overruns in its offshore wind and renewables projects, as evidenced by the large impairment and regulatory changes impacting Empire Wind in the US, which could lead to lower-than-expected returns and further write-downs, directly pressuring future earnings and asset values."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 19% below our estimate - targets everyday supplement users and scales output via automation and logistics upgrades.
- Company 2 - 33% below our estimate - wins subsea tieback work using integrated engineering models and long-duration service contracts.
- Company 3 - 46% below our estimate - shifts toward higher grade ore feed while advancing underground projects to extend reserves.
That is three of the list. See the full list of 204 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com