


How Borrowing Costs And Deal Pipeline At Getty Realty Stock Have Changed Its Investment Story
- Getty Realty continues to run a rate sensitive net lease model focused on long contracts with convenience and automotive tenants, along with an active pipeline of acquisitions and development fundings that can add rental income over time.
- The key tension for Getty Realty is how much incremental rental revenue its sale leaseback and development deals can generate relative to the borrowing costs that fund them.
- The next area of focus will be how Getty Realty's interest rate sensitivity and acquisition pipeline could reshape its broader investment narrative.
Getty Realty Investment Narrative Recap
For a shareholder in Getty Realty, the core belief is that long term, net lease cash flows from convenience and automotive tenants stay resilient enough to cover funding costs and support a steady acquisition program. The recent focus on rate sensitivity does not alter that basic idea, but it does put more attention on how efficiently management can match new deals to its cost of capital.
The near term swing factor is whether the current US$95 million to US$125 million pipeline actually lands on yields that keep AFFO moving in the right direction. The biggest risk is that debt remains expensive relative to mid to high 7% deal yields, which would leave less room for accretive growth and could pressure earnings if rent coverage weakens at newer concepts like car washes.
With no new filings tied directly to this rate discussion, the existing disclosure on the Refuel sale leaseback and the Now and Forever program in Texas remains the most useful reference point. Those transactions show how Getty Realty leans on larger, programmatic deals to put capital to work at scale, rather than chasing one off properties.
For you as an investor, the question is how repeatable that pattern really is while funding costs stay elevated. If the pipeline continues to look like Refuel in terms of long lease tenure, coverage near 2.5x and yields in the mid to high 7% range, the core external growth story stays intact. If credit quality or coverage slips as newer concepts season, risk around rent collection and future AFFO increases.
Getty Realty's current analyst narrative points to revenue of US$306.9 million and earnings of US$108.1 million by 2029, based on an assumed 9.6% yearly revenue growth rate and an earnings increase of about US$11.8 million from US$96.3 million today.
Uncover why Getty Realty's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
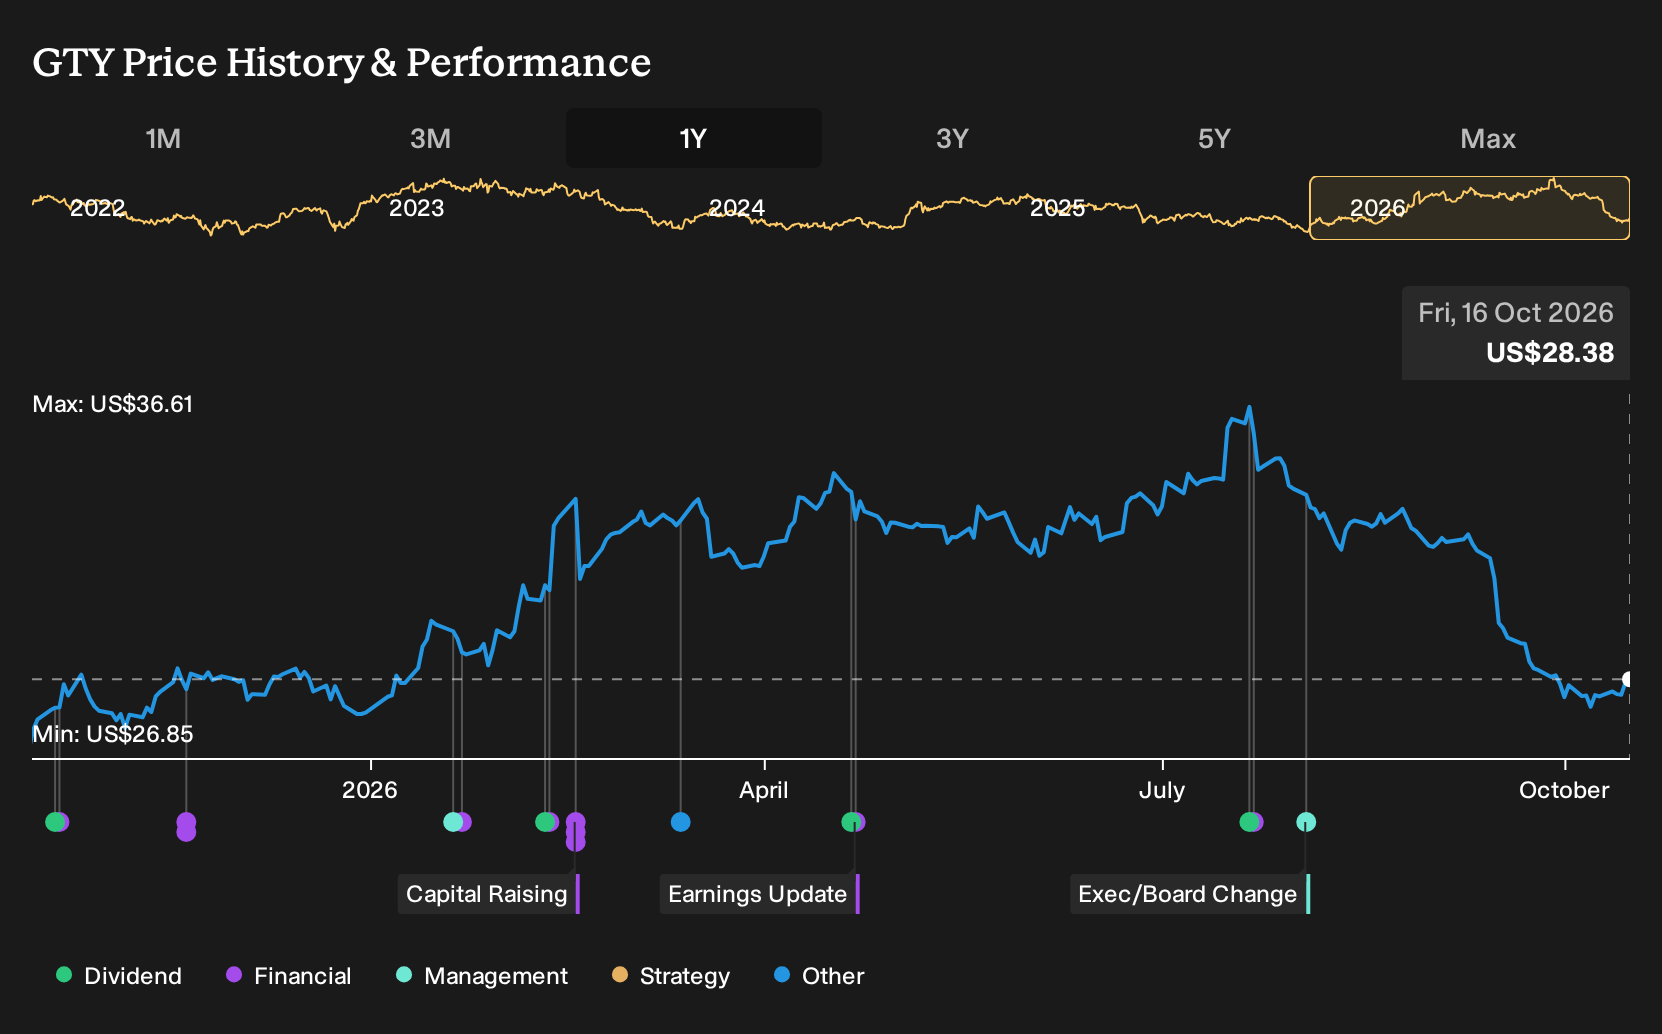
The three fair value estimates from the Simply Wall St Community cluster between about US$35.57 and US$78.60 per share, which shows how far opinions on Getty Realty can stretch. Some members focus on the US$95 million to US$125 million acquisition pipeline as a growth catalyst, while others worry more about fuel demand shifts and tenant consolidation. Use that spread to stress test your own view and explore alternative assumptions before committing fresh capital.
Explore 2 other Getty Realty fair value estimates, including one that suggests potential upside of up to 177% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Getty Realty research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Getty Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getty Realty's overall financial health at a glance.
Looking for more investment ideas beyond Getty Realty?
If Getty Realty has sharpened your thinking on income, risk, and balance sheets, use that momentum to scan a broader watchlist of possible additions. The Simply Wall St Screener lets you line up other stocks against the same filters you care about, from durability of cash flows to balance sheet strength and income potential.
- If capital preservation sits high on your list, start with companies that score well on resilience and risk. Use the 32 resilient stocks with low risk scores as your jumping off point.
- For investors who want quality at a reasonable entry price, line up candidates that pair solid fundamentals with appealing valuations and see what surfaces in the 20 high quality undiscovered gems.
- Income focused readers who like the dividend angle behind Getty Realty can widen the search to other high yield payers by scanning the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com