


How Strong Trading Volume Growth At Tradeweb Markets Stock Has Changed Its Investment Story
- Tradeweb Markets reported September 2026 trading volume of $81.6 trillion and third quarter volume of $210.3 trillion, with average daily volume up 29% YoY for the month and 22.4% YoY for the quarter.
- The sharp rise in activity across Tradeweb Markets' platforms highlights how higher throughput can support revenue tied to electronic trading and data services, while also testing the efficiency of the firm's cost base and technology spend.
- We will now look at how Tradeweb Markets' strong September and third quarter average daily volume figures could influence its investment narrative.
Tradeweb Markets Investment Narrative Recap
Owning Tradeweb Markets usually means believing that electronic fixed income and derivatives trading can keep taking share from voice and manual workflows, and that the firm can convert higher volumes into attractive profitability over time. The latest September and third quarter ADV figures support the idea that usage of its platforms remains healthy in the near term.
The short term swing factor is whether this volume strength flows through to revenue fast enough to keep up with rising technology and data costs. The biggest risk is that elevated expense growth, kept near the top of guidance, squeezes margins if trading activity or pricing does not keep pace.
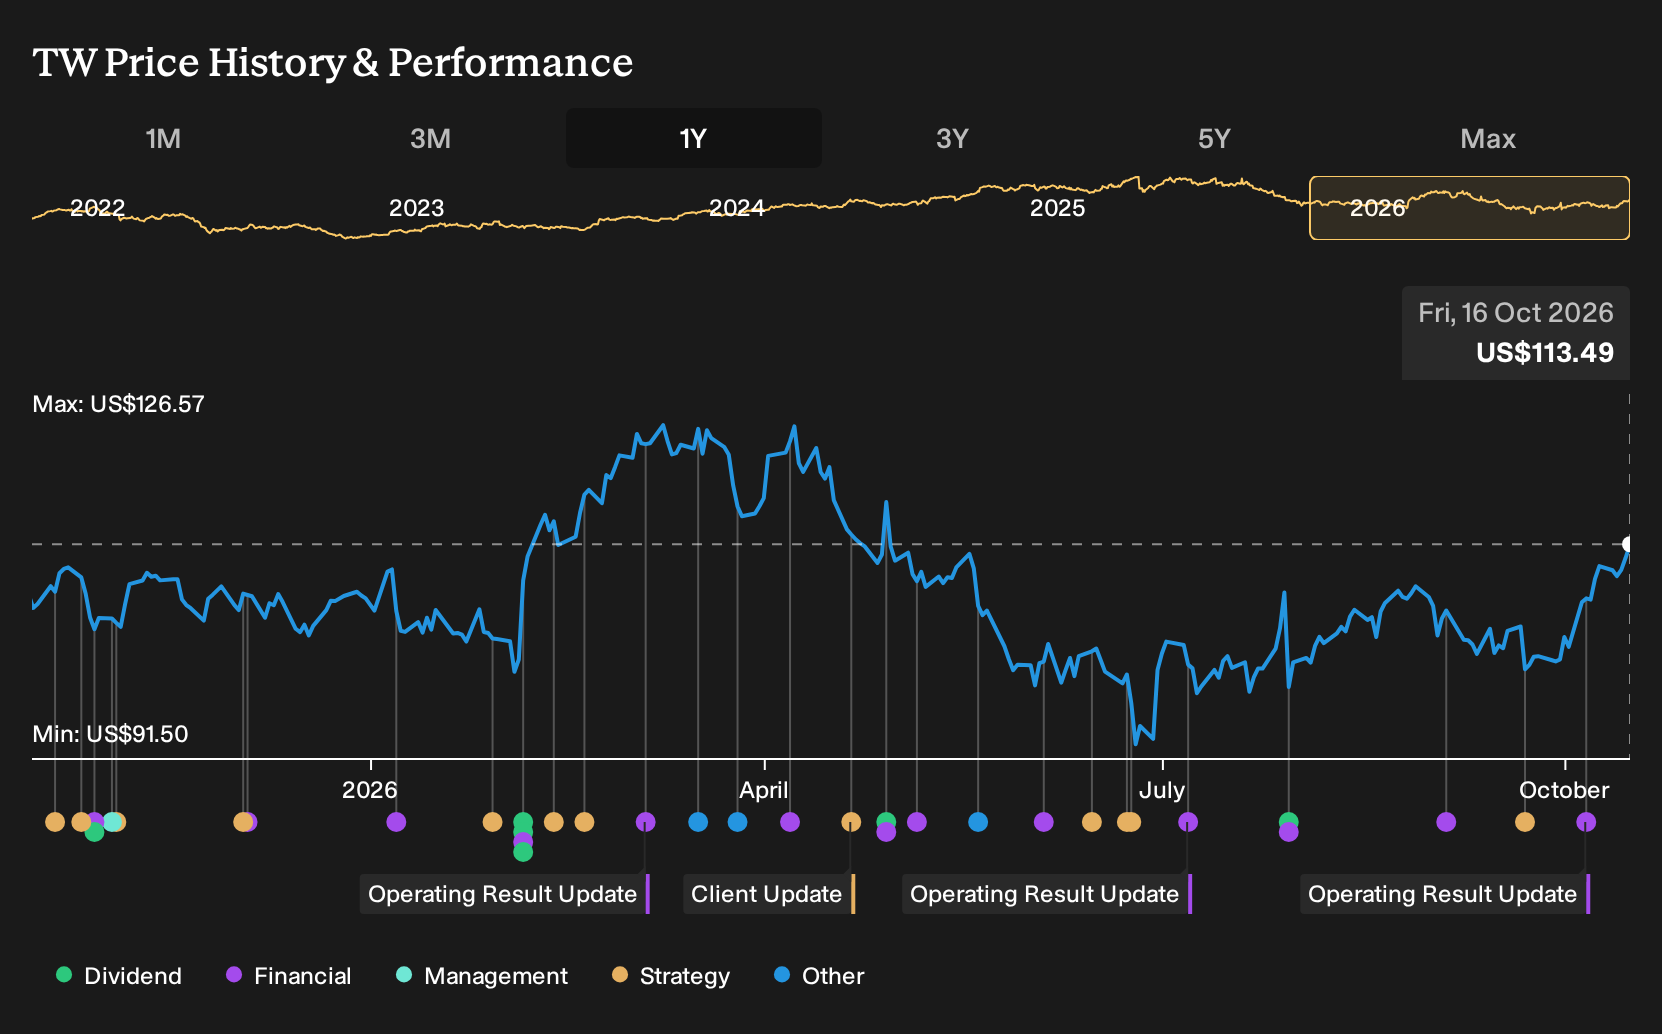
Recent production data for September and the third quarter is the clearest confirmation of how Tradeweb Markets is positioned operationally after earlier revenue disappointment versus forecasts. With US$81.6 tn of volume in September and US$210.3 tn in the quarter, the group is handling substantial flow across its marketplaces.
Those figures sit directly against two key questions. Can the business translate strong ADV into fee growth while keeping adjusted expenses, including higher technology and communication spend, from eroding earnings quality? And can continued electronification in rates, credit and swaps, supported by tools like AiEX and TARA, offset investor concern about expense discipline and valuation sensitivity?
Tradeweb Markets' current analyst narrative points to revenues of US$3.0b and earnings of US$1.2b by 2029, based on a forecast 10.3% yearly revenue growth rate and a move from US$896.7m of earnings today. This implies an increase of about US$303m in earnings over that period.
Uncover why Tradeweb Markets' fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Tradeweb Markets leans heavily on margin risk. Bearish analysts worry that higher technology and communication costs swamp fee growth, so they model revenue of about US$2.9b and earnings near US$1.0b by 2029. That is far below the US$3.0b and US$1.2b that the optimistic group used before this latest volume news. Both camps may revisit those assumptions after such strong September and third quarter trading statistics, which is why you may want to compare several narratives before deciding how these new numbers fit your own view.
Explore 3 other Tradeweb Markets fair value estimates, including one that suggests as much as 27% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Tradeweb Markets research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tradeweb Markets. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tradeweb Markets' overall financial health at a glance.
Looking For More Ideas Beyond Tradeweb Markets?
If you want to stress test your view on Tradeweb Markets, it can help to line it up against other businesses with different risk and return profiles using the Simply Wall St screener.
- For investors comfortable with higher volatility in search of outsized moves, review a focused set of early-stage opportunities through the 14 elite penny stocks with strong financials.
- If valuation discipline is your priority, scan for companies that pair stronger fundamentals with what may be more appealing entry prices using the 32 high quality undervalued stocks.
- For a portfolio tilt toward resilience and balance sheet strength, filter for businesses with sturdier financial footing via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com