


China Resources Land (SEHK:1109) Recurring Income Holds Firm, Is The Upside Already Priced In?
China Resources Land (SEHK:1109) has put fresh numbers on the table, with its latest sales update showing weaker contracted volumes while recurring revenue and rental income continued to climb.
At a share price of HK$31.06, China Resources Land has seen a 1-month share price return of 8.98% and a year to date share price gain of 12.05%. However, the 90-day share price return is down 7.89% as investors reassess development risk against a firmer recurring income base.
See how China Resources Land compares with other Hong Kong developers that rely on recurring income by reviewing our curated list of solid balance sheet and fundamentals (204 results) for ideas that emphasize funding resilience.
China Resources Land has already rerated on its recurring income story, yet the stock is still trading below many analysts’ targets. Has most of the easy upside been used up, or does the valuation still leave room?
Preferred P/E of 8.1x: Is it justified for China Resources Land?
On a simple earnings multiple, China Resources Land trades on a P/E of 8.1x, which is anchored to a last close of HK$31.06 and sits below several reference points that many investors watch closely.
The P/E ratio compares the current share price to earnings per share, so it effectively tells you how many dollars of price the market is willing to pay for one dollar of profit. For a large Hong Kong developer with both development projects and a growing recurring rental base, that lens helps you see what investors are paying for current earnings in a sector where balance sheet strength and cash generation matter a lot.
At 8.1x earnings, the stock is priced at a discount to the Hong Kong market average of 10.6x and well below the peer group average of 16x. It is also under the estimated fair P/E of 14x. This points to a gap between where the ratio sits today and a level the market could move toward if sentiment or earnings quality shift. Relative to the Hong Kong real estate industry average P/E of 8.9x, China Resources Land is still lower, so the market is assigning a cheaper earnings tag despite the forecast 6.5% annual profit growth and a 4.4% dividend yield.
Explore the SWS fair ratio for China Resources Land.
Result: Price-to-earnings of 8.1x (UNDERVALUED)
Still, the story for China Resources Land can shift quickly if contracted sales soften further or if rental growth slows and weakens the recurring income pitch.
Find out about the key risks to this China Resources Land narrative.
Another view on China Resources Land’s valuation
The P/E story paints China Resources Land as cheap, yet the SWS DCF model tells a different tale. At HK$31.06, the share price sits well above an estimated future cash flow value of HK$17.61. This points to an overvalued result on this method and a smaller margin for error.
For investors, that split view raises a simple question: Is the stronger recurring income worth paying ahead of the cash flow math, or is patience the better ally when the modeled fair value sits lower on our DCF workup, guided by assumptions on future profit and discount rates that may not play out as expected?
Look into how the SWS DCF model arrives at its fair value.
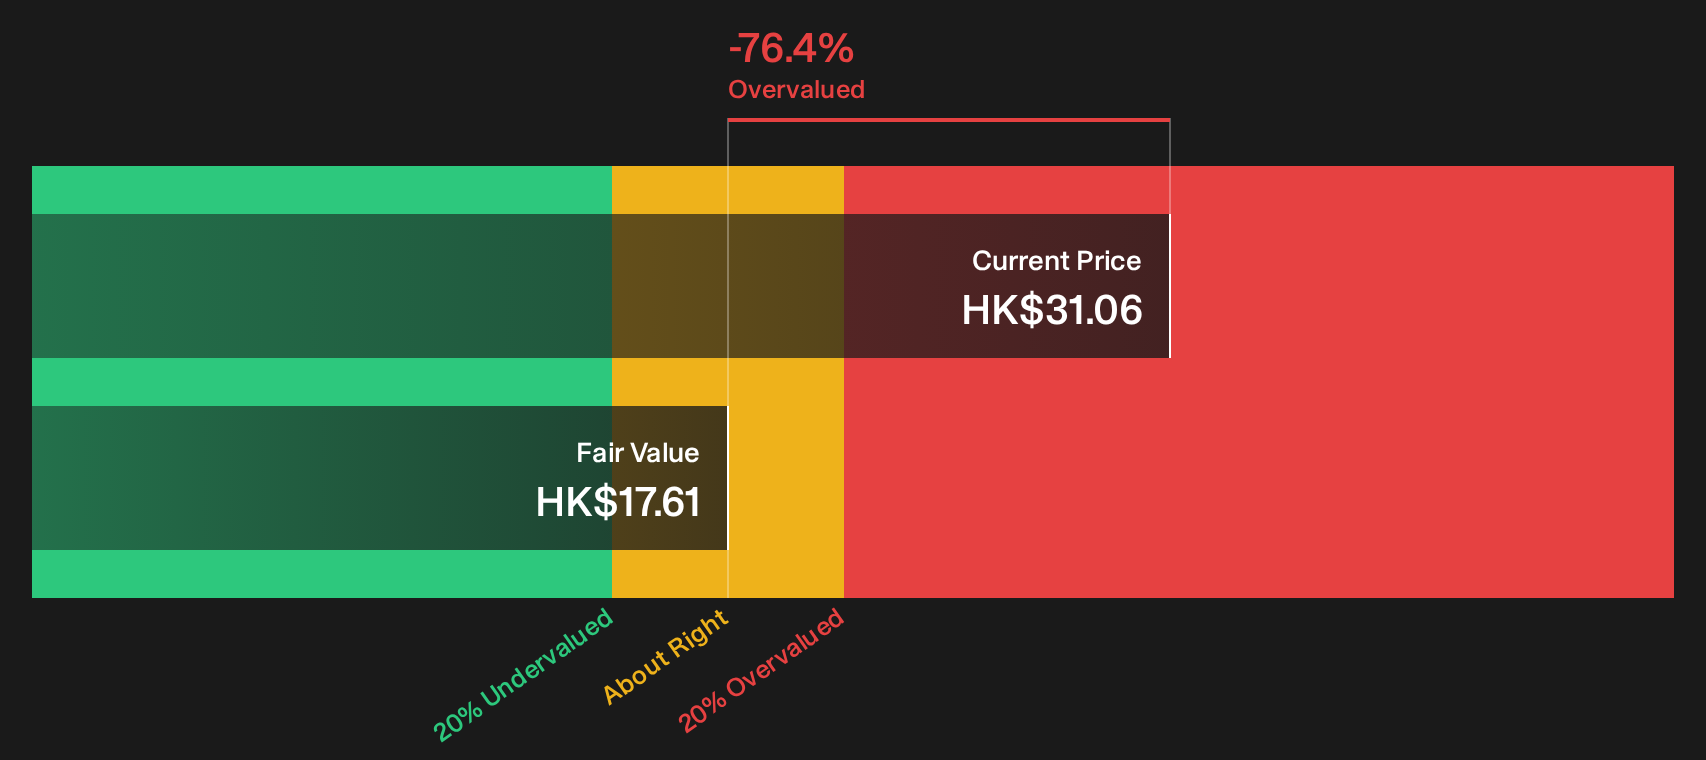
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Land for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 186 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China Resources Land’s valuation and cash flows make this a moment to move past headlines and test the numbers yourself. Weigh the recurring income against the development risk, then pressure test your view using the 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Resources Land?
If China Resources Land has sharpened your focus on valuation and balance sheet strength, do not stop here. Fresh ideas often emerge where few investors are looking.
- Target strong quality at sensible prices by scanning a focused set of 186 high quality undervalued stocks that pair solid fundamentals with compressed multiples.
- Build a steadier income stream by reviewing 216 dividend fortresses that combine higher yields with more resilient cash generation.
- Sleep easier through market swings by concentrating on 233 resilient stocks with low risk scores that score well on financial health and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com