


Builders FirstSource (BLDR), What Is Drawing Fresh Attention To The Stock?
Builders FirstSource (BLDR) moved higher by 2.16%, outpacing the broader market even after recent weakness, as investors focused on the upcoming October 29 earnings release and recently lowered consensus expectations.
That move comes after a tougher stretch for Builders FirstSource, with the share price down 5.97% over the past month and 24.83% over 90 days, while the year to date share price return has fallen 47.77% and the 1 year total shareholder return is down 55.40%. This points to fading momentum as investors reassess earnings risk and longer term prospects around the upcoming results.
Stress test your exposure to Builders FirstSource by comparing it with our hand picked 33 high quality undervalued stocks that combine earnings support with more resilient recent share price trends.
Builders FirstSource now trades at a sizeable discount to both analyst targets and one intrinsic value estimate, even after the sharp pullback. Is this caution grounded in earnings risk or is it overdone relative to fair value?
Most Popular Narrative: 26% Undervalued
Builders FirstSource last closed at $54.65, while the most followed narrative pegs fair value at about $73.36 using a 10.8% discount rate. That gap puts the spotlight on whether execution on higher margin products, cost savings and digital tools can support the valuation case.
Builders FirstSource is still investing heavily in digital transformation and value-added solutions such as digital tools, ERP integration and prefabricated components. This positions the company to improve operating efficiency and customer stickiness as housing activity recovers, supporting future revenue and net margins. The five year commercial partnership and $25.3 million investment in Digs to embed AI powered workflows into Builders FirstSource’s digital ecosystem is expected to improve quoting, design and construction productivity for customers. This can support higher value added revenue and better margins as these tools are rolled out and adopted.
See why 27 investors see Builders FirstSource as 26% undervalued.
Result: Fair Value of $73.36 (UNDERVALUED)
Still, if housing demand stays weak or competitive pricing further pressures margins, the current Builders FirstSource valuation gap could easily close for the wrong reasons.
Find out about the key risks to this Builders FirstSource narrative.
Another View: What Multiples Say About Builders FirstSource
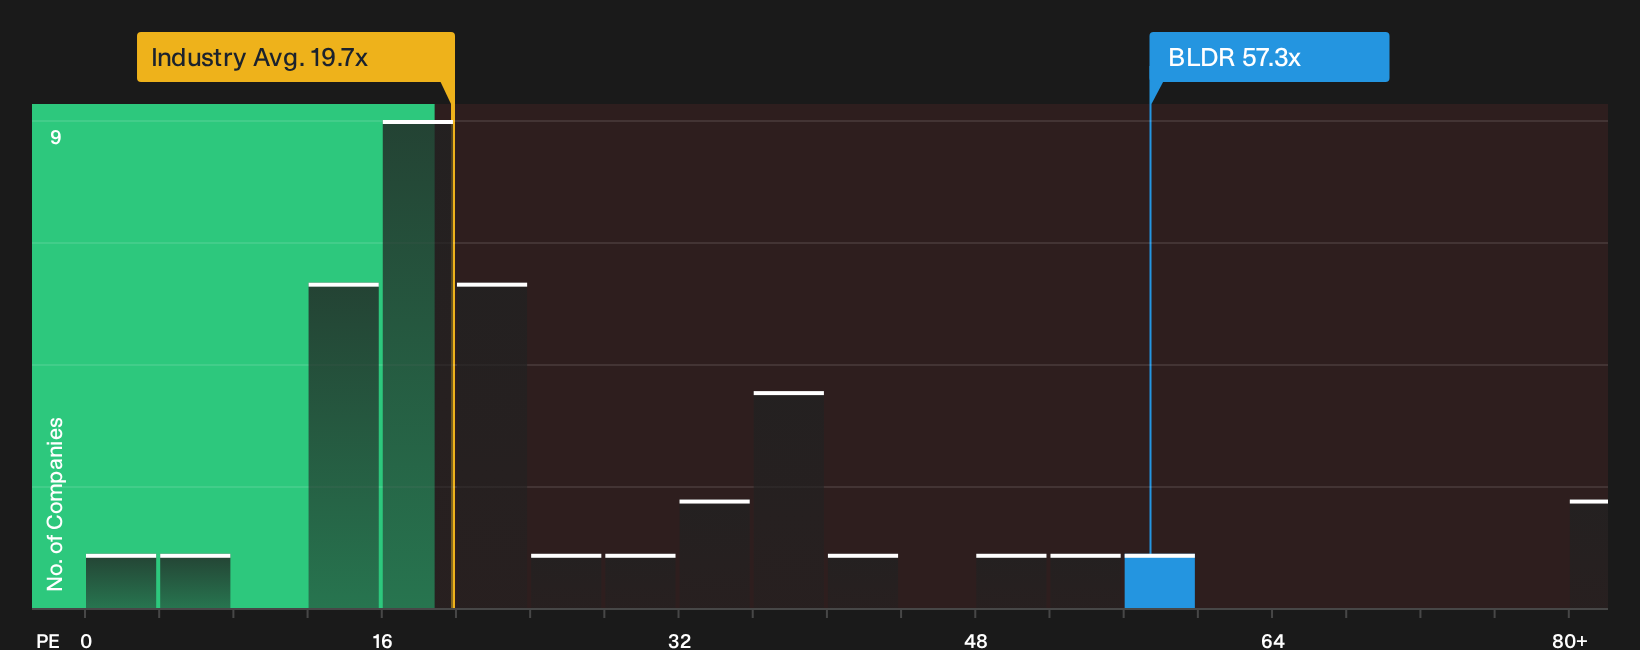
There is a catch. While the SWS DCF model flags Builders FirstSource as undervalued versus an estimated future cash flow value of $78.63, the stock trades on a P/E of 57.3x compared with a 40x peer average and a fair ratio of 58.4x. That mix of apparent discount on cash flows and rich earnings multiple raises a simple question for you as an investor: Is the market mispricing the cash generation, or just slow to reset earnings expectations?
See what the numbers say about this price in our valuation breakdown, then compare it with your own assumptions and risk tolerance before making any decision. See what the numbers say about this price — find out in our valuation breakdown.
For a clearer view of how Builders FirstSource stacks up on earnings relative to its sector, review the industry comparison chart.
Next Steps
Mixed signals around Builders FirstSource rarely stay mixed for long, so check the charts, valuation and narrative data yourself and decide where you stand. To weigh the potential upside against the concerns raised by other investors, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Builders FirstSource?
If Builders FirstSource has your attention, do not stop there. Broadening your watchlist with other focused ideas can sharpen your overall risk and opportunity mix.
- Target specific upside potential by scanning focused pockets of the market with the 13 elite penny stocks with strong financials that meet your risk appetite.
- Anchor your research in value by reviewing a curated 33 high quality undervalued stocks that balances quality fundamentals with pricing support.
- Support portfolio resilience by using a 32 resilient stocks with low risk scores built around balance sheet durability and more measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com