


Terumo (TSE:4543) Just Gave Investors A Bigger Question
Event overview and why Terumo matters now
Terumo (TSE:4543) has moved into focus after it agreed with CSL Plasma to end a source plasma collection supply deal and cut full-year earnings guidance, tied to roughly US$610 million in related charges.
For context, Terumo shares last closed at ¥2,337, with a 90‑day share price return of 3.06% and a year to date gain of 3.29%, while the total shareholder return is down 4.23% over one year but up 25.04% over three years. This points to longer term holders still sitting on gains even as recent news on the CSL Plasma termination and guidance cut has cooled shorter term momentum.
Scan how other healthcare stocks with resilient balance sheets are handling contract shocks like Terumo by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) now shaping investor watchlists.
Terumo now trades in the shadow of a one off ¥97.5b hit and a reset profit outlook. Is the recent share reaction about business fundamentals, sentiment overshooting the shock, or both, and what does the current valuation imply?
Most Popular Narrative: 24% Undervalued
Terumo last closed at ¥2,337, while the most widely followed narrative pegs fair value at about ¥3,075. That gap reflects a view that the plasma exit and one off charges sit on top of an earnings profile that still supports higher long term cash generation when discounted at 5.56%.
Broad-based deployment and ramp-up of high-margin consumables, such as Rika in Global Blood Solutions, are driving improved production efficiency and a more favorable revenue mix. This recurring consumable revenue base is likely to further enhance profitability and cash flow.
See why 3 investors see Terumo as 24% undervalued.
Analysts linking this story to valuation work with a fair value estimate of roughly ¥3,075 based on projected revenue of ¥1,443.8b, profit margins rising from 13.9% to about 15.2%, and a future P/E of 24.4x that sits above the current JP Medical Equipment sector level of 16.2x. That framework also leans on earnings forecasts of ¥218.9b by around October 2029 and a discount rate of 5.56%, which together help explain why the consensus target of ¥3,075.38 remains well above the current share price even after incorporating the CSL Plasma related reset.
For readers cross checking this against their own view, the same narrative flags risks around tariffs, China volume based procurement and an R&D profile that may trail peers, which could all chip away at those margin and earnings assumptions. The gap between bullish and cautious analyst targets, from ¥2,600 up to ¥3,800, underlines how much depends on Terumo converting its high margin consumables and cardiovascular strengths into durable earnings without giving too much back through pricing pressure or higher operating costs.
Result: Fair Value of ¥3,075 (UNDERVALUED)
Still, the Terumo story hinges on tariff pass through and China procurement risk. Either of these could squeeze margins enough to challenge that ¥3,075 view.
Find out about the key risks to this Terumo narrative.
Another View: Terumo through the P/E lens
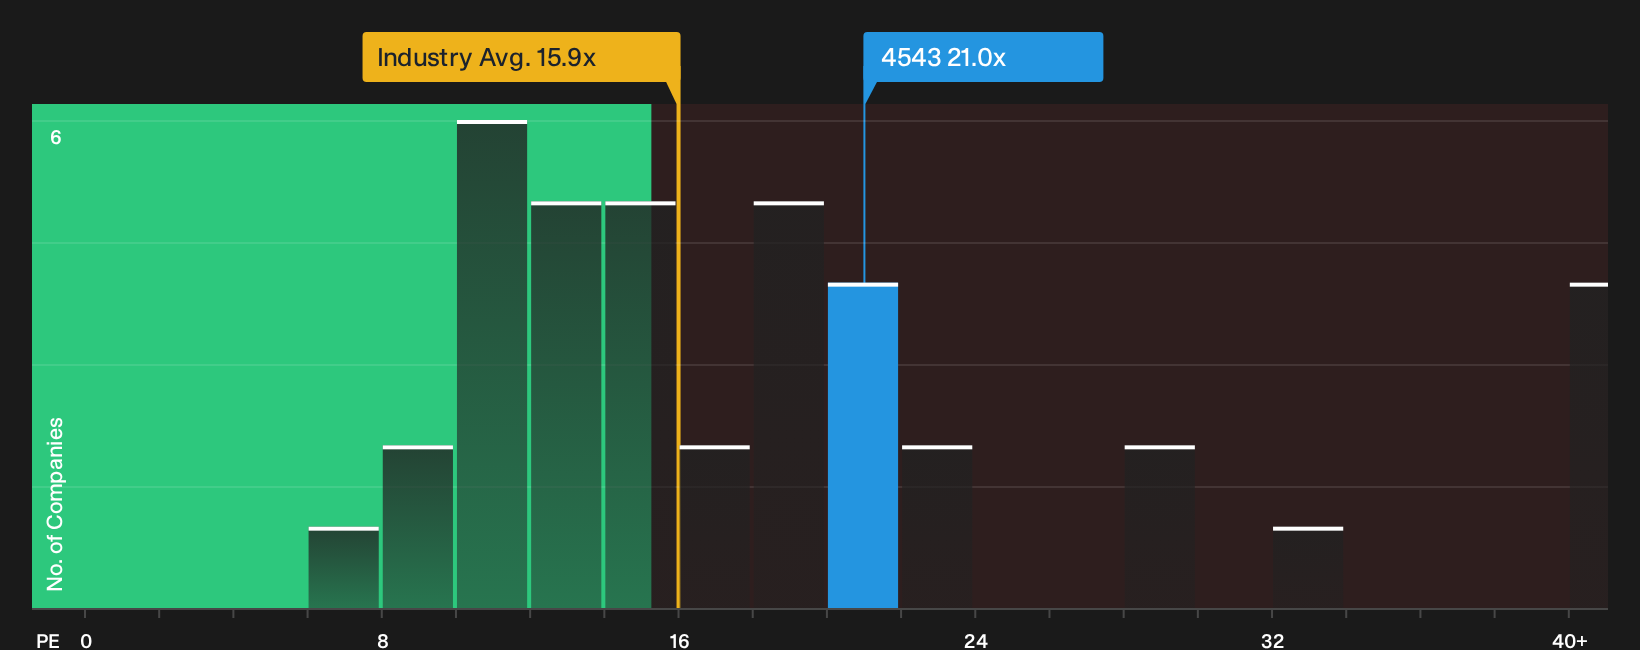
Terumo might look cheap against analyst fair value, yet its current P/E of about 21x is higher than the JP Medical Equipment industry at 15.9x and close to the peer average of 21.6x. The fair ratio sits higher again at 25.5x. Is that premium a source of comfort, or does it represent extra valuation risk if expectations slip?
For readers weighing that gap between current P/E, peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Terumo is divided between caution about risks and interest in potential upside. Act while the data is fresh and form your own view by weighing the 4 key rewards
Looking for more investment ideas beyond Terumo?
Terumo gives you one angle on healthcare, but broader opportunities sit across sectors, risk levels, and income profiles. Consider exploring those as well.
- Target potential mispricing by checking companies that screen as high quality yet possibly underappreciated through the 13 high quality undervalued stocks.
- Strengthen your income playbook by reviewing a focused lineup of higher yielding payers via the 29 dividend fortresses.
- Dial back portfolio stress by scanning for sturdier balance sheets and lower risk profiles using the 23 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com