


Is Freeport-McMoRan (FCX) Undervalued As Q3 Earnings Put Copper And Gold In Focus?
Freeport-McMoRan (FCX) is back in focus as investors brace for its third quarter 2026 earnings release on October 27, with attention on copper pricing, sales volumes and deferred gold shipments.
Freeport-McMoRan’s recent pullback, with the share price down 5.63% over the past week to US$69.54, comes after a strong 90-day share price return of 18.29% and a 1-year total shareholder return of 70.44%. This suggests momentum has cooled in the short term, even as longer term performance remains strong.
Spot fresh momentum plays around copper and materials by scanning our hand picked 17 top copper producer stocks alongside the latest action in Freeport-McMoRan.So is Freeport-McMoRan’s recent slide just sentiment cooling after a strong run, or is the share price finally catching up with what the underlying business is actually worth as earnings approach?
Most Popular Narrative: 24% Undervalued
Freeport-McMoRan’s most followed valuation story pegs fair value at $92 per share, well above the last close at $69.54. This puts the focus squarely on whether copper projects and cost control can bridge that gap.
Freeport-McMoRan is pushing its leach program toward a modeled 800 million pounds of annual copper from existing stockpiles using additives and heat. If this throughput and low sub US$1 per pound incremental operating cost profile carries through to full scale, the uplift in high margin volumes could materially widen future net margins and operating cash flow beyond what typical project capex would imply.
See why 15 investors see Freeport-McMoRan as 24% undervalued.
Result: Fair Value of $92 (UNDERVALUED)
Still, higher capital spending forecasts and rising input costs on energy and labor could squeeze Freeport-McMoRan’s cash flow and weaken the bullish margin narrative.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View: What Multiples Say About Freeport-McMoRan
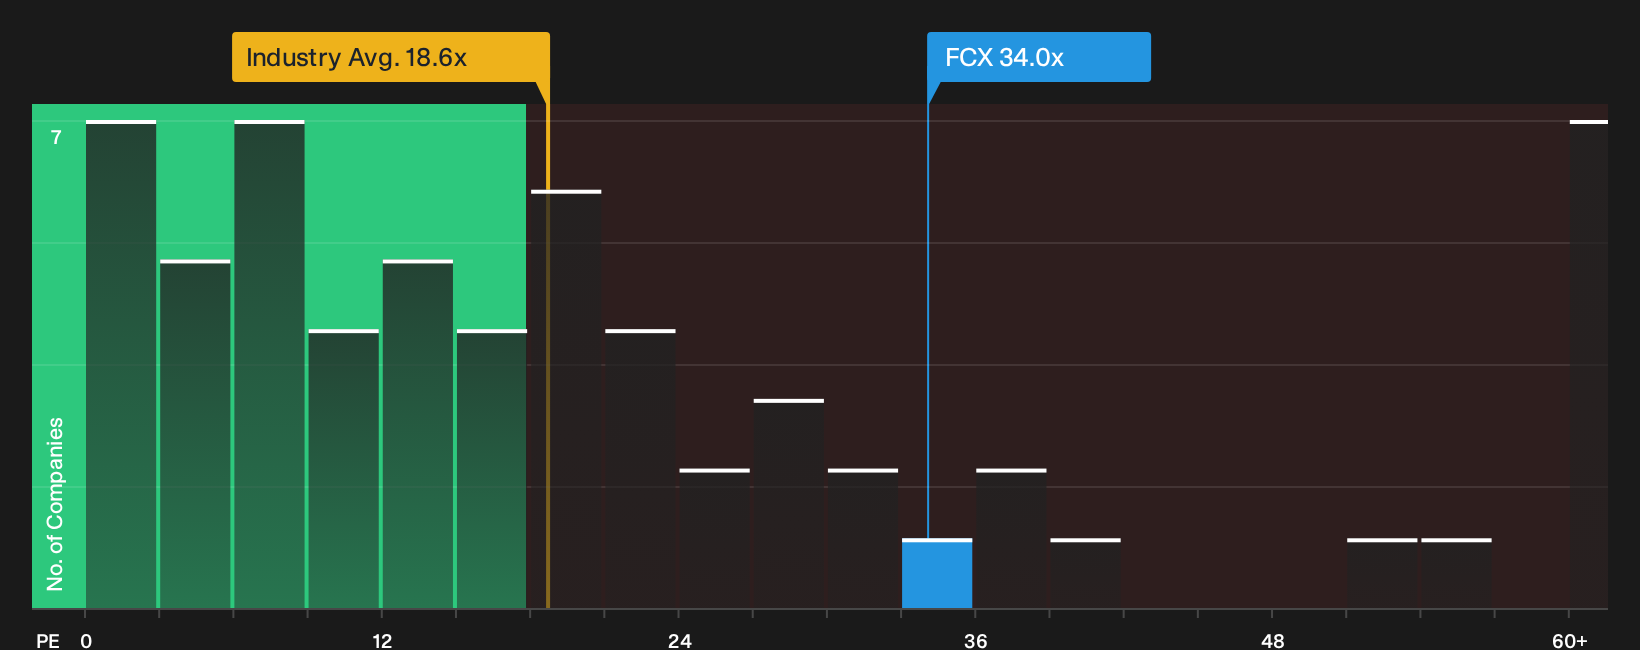
The story looks different when you switch from fair value models to simple P/E math. Freeport-McMoRan trades around 34x earnings, while the fair ratio sits at 28.3x and the US Metals and Mining group is closer to 18.6x to 20.2x. That gap points to valuation risk rather than a clear bargain. The key question is whether your conviction on future cash generation justifies paying that premium today.
For a closer look at how these earnings ratios stack up against the market and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on sentiment can be useful. Use the full set of numbers and commentary to stress test your own thesis, including the 2 key rewards and 1 important warning sign
Looking for more Freeport-McMoRan sized ideas?
If you stop with Freeport-McMoRan, you leave a lot on the table. Broaden your watchlist now using focused screeners built around fundamentals and quality.
- Target income first and hunt for potential cash generators with the 8 dividend fortresses that could complement a copper focused holding like Freeport-McMoRan.
- Sharpen your value radar and search for quality businesses on the 33 high quality undervalued stocks that might offer a more attractive entry point than headline favourites.
- Dial back portfolio stress and look for steadier candidates through the 32 resilient stocks with low risk scores that prioritises balance sheet strength and more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com