


Is Fukuyama Transporting (TSE:9075) Expensive On Its Expected Securities Sale Gain?
Fukuyama Transporting (TSE:9075) has called a board meeting for 6 October 2026 to address an expected gain from selling investment securities, a move that could reshape how investors view upcoming earnings quality.
Recent trading hints at growing interest in Fukuyama Transporting, with a 1-day share price return of 4.21% helping extend strong year-to-date share price gains of 43.85%. The 1-year total shareholder return of 67.55% points to momentum that has been building rather than fading.
Scan for other logistics and industrial stocks showing similar earnings catalysts by reviewing our curated list of 13 high quality undervalued stocks together with Fukuyama Transporting.
After a sharp move on the back of the expected securities gain, Fukuyama Transporting now poses a simple tension: Do you accept today’s price, or wait and hope the valuation gives you another chance?
Price-to-Earnings of 14.7x: Is it justified?
On traditional valuation, Fukuyama Transporting trades on a P/E of 14.7x, which sits above the JP Transportation industry average of 11.7x and lines up with a share price of ¥6,430 that has moved ahead of the analyst price target of ¥6,112.5.
The P/E ratio links what you pay today to the earnings the business generates per share. For a logistics group like Fukuyama Transporting, investors often look at P/E because profit trends can reflect freight demand, pricing power and cost discipline more directly than balance sheet metrics.
Revenue is forecast to grow at 3.3% a year and earnings at 0.4% a year, both slower than the wider JP market. A premium P/E in this context suggests buyers are comfortable paying up despite modest growth forecasts. At the same time, the firm carries a Return on Equity of 5.4% that is flagged as low, and the estimated fair P/E of 12x points to a level the market could move toward if sentiment cools.
Against peers, the picture is mixed. Fukuyama Transporting screens as expensive against the JP Transportation industry average on P/E, yet looks cheaper than its direct peer group where the average multiple is 18.9x. This implies the stock trades in between broad sector pricing and closer comparable companies.
Explore the SWS fair ratio for Fukuyama Transporting.
Result: Price-to-Earnings of 14.7x (OVERVALUED)
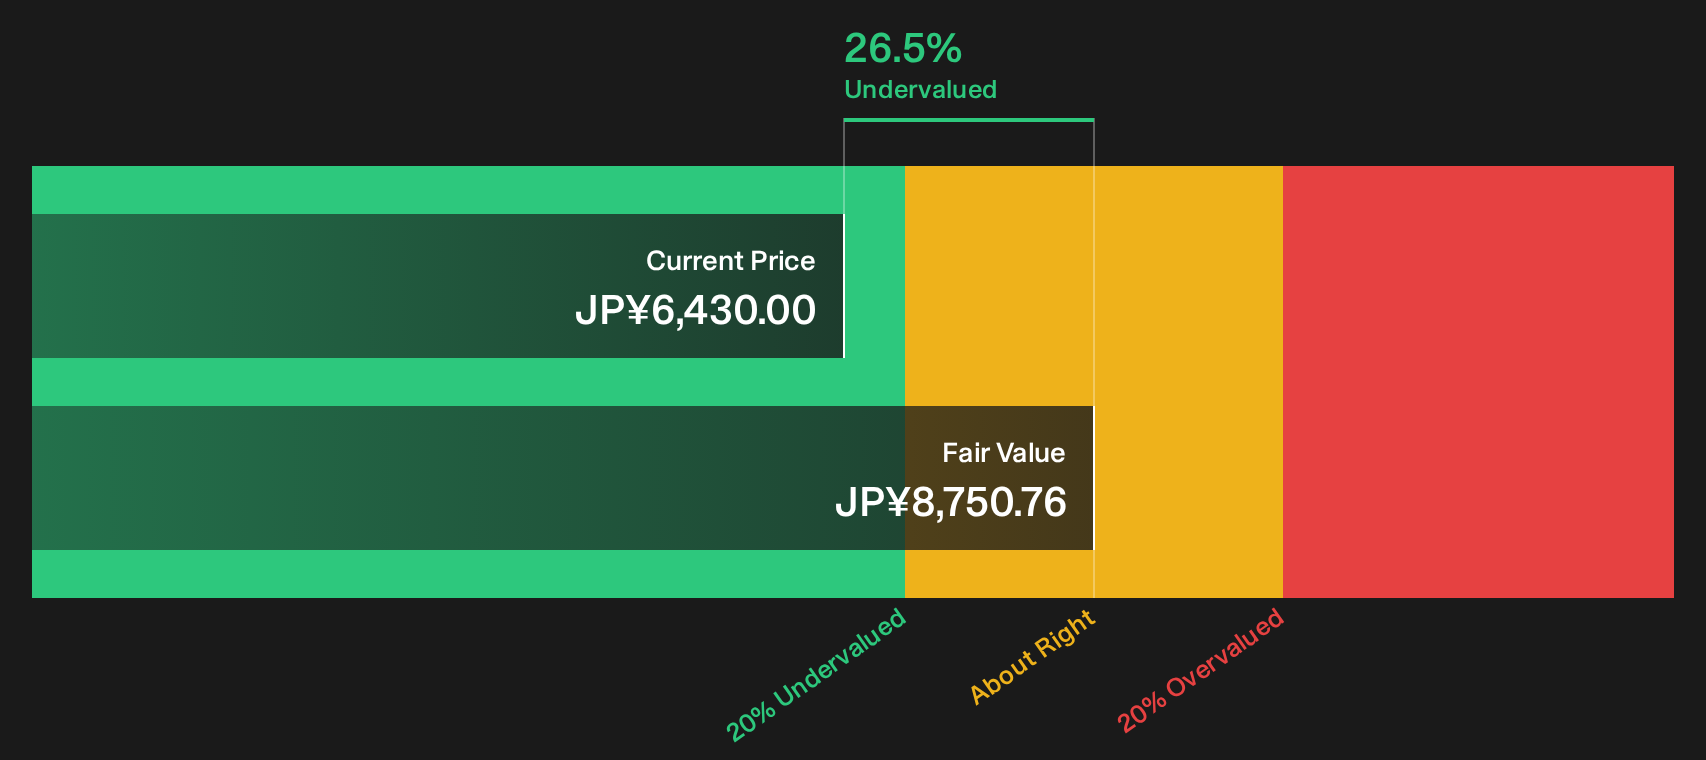
That relative picture sits alongside a different signal from the SWS DCF model, which estimates a future cash flow value of ¥8,750.76 per share for Fukuyama Transporting compared with the current ¥6,430 market price. This 26.5% discount frames the stock as good value on this methodology.
The DCF approach projects the cash Fukuyama Transporting is expected to generate over time and then discounts those flows back to today using a required return, which turns long range estimates into a single present value per share. This style of model often puts more weight on cash generation and longevity of the business than on near term earnings momentum.
For a logistics group with relatively low forecast revenue and earnings growth, but recent 1 year earnings expansion of 96.3% and a large one off gain affecting the last 12 months, the DCF output may appeal to investors who prefer to smooth those temporary items and focus on underlying cash potential across cycles.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of ¥8,750.76 (UNDERVALUED)
Still, if freight volumes soften or the one off securities gain fades from view, Fukuyama Transporting’s premium P/E and DCF gap could compress quickly.
Find out about the key risks to this Fukuyama Transporting narrative.
Another View: Fukuyama Transporting Through A Cash Flow Lens
P/E points to Fukuyama Transporting looking expensive, yet the SWS DCF model paints a different picture. On that cash flow view, estimated value sits at ¥8,750.76 per share, compared with the current ¥6,430 price, which screens as undervalued. Which signal do you trust more when profit quality is clouded by one off gains?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fukuyama Transporting for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Fukuyama Transporting so far. If you want to form your own view, act promptly and consider both perspectives using our breakdown of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Fukuyama Transporting?
If you stop with Fukuyama Transporting, you miss other opportunities the same data-driven tools can highlight, and that is where the screener really earns attention.
- Target resilient opportunities by checking companies in the 23 resilient stocks with low risk scores that aim to balance upside potential with more measured downside exposure.
- Hunt for strong businesses that the market may have overlooked by using the 73 high quality undiscovered gems to spot quality hidden in plain sight.
- Zero in on rock-solid finances by reviewing the list of solid balance sheet and fundamentals (22 results) and focus on businesses built on sturdier foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com