


What Ajinomoto Doubters Overlooked
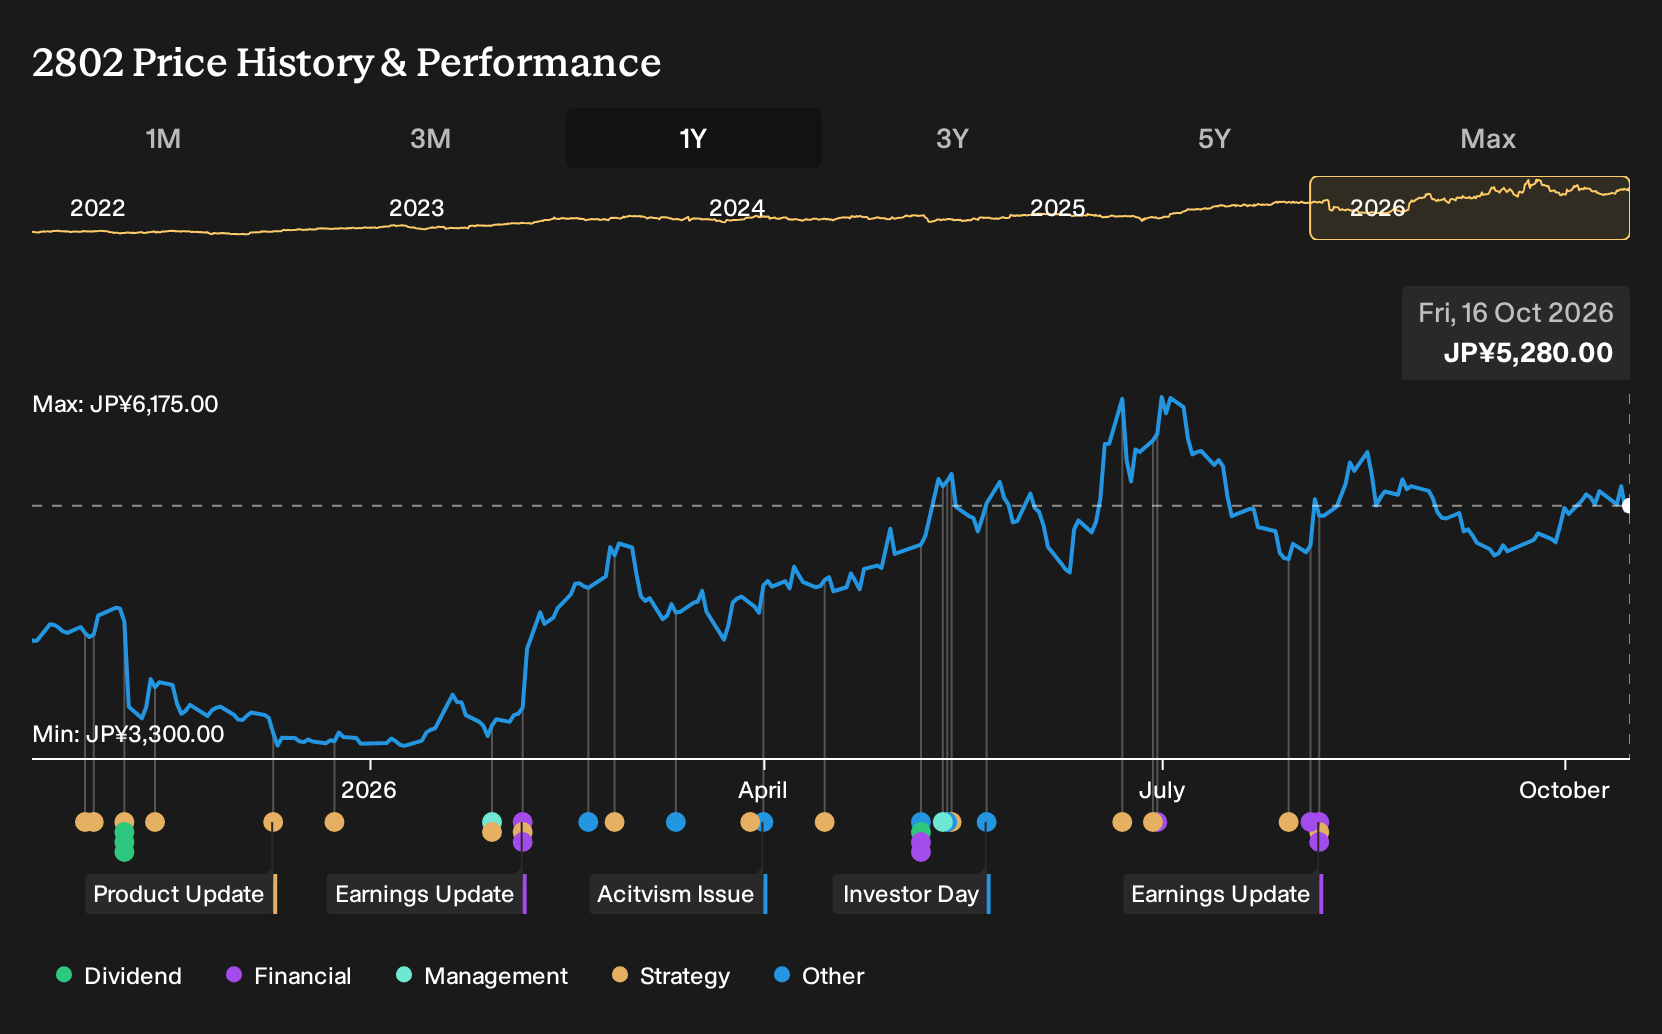
If Ajinomoto was sitting on your watchlist instead of in your portfolio, the past year may feel like a missed shot. For Ajinomoto shareholders, the return over the past year was 28.1%, including dividends. That outcome raises a sharper question than simple regret. Back on 16 October 2025, could a focus on urbanizing Asian demand for healthier convenience foods and the shift toward higher value specialty ingredients have helped you spot this set up earlier?
Ajinomoto is not the only name tied to this theme. Zero in on 10 healthcare AI stocks and compare how each one is priced.
The Two Ajinomoto Stories Investors Had To Weigh
The shares cost ¥4,182 at the start of the period, and anyone eyeing Ajinomoto had to choose which story to trust more.
The bullish narrative pointed to a Fair Value of ¥4,700, a notional price based on expectations that specialty ingredients and wellness products would reshape the portfolio and lift margins through higher value, recurring revenue. Supporters leaned on the idea that urbanizing Asian demand and amino acid technology could support stronger earnings power.
The bearish view anchored on a Fair Value of ¥3,300, a notional level built around concern that clean label trends and tighter food regulation would keep eroding demand for Ajinomoto's legacy MSG based products. Followers of this case worried that slower progress in health focused offerings and rising compliance costs could cap profitability.
What The Results Changed For The Ajinomoto Story
Ajinomoto’s Q1 2027 figures showed revenue at ¥412.0b and net income at ¥36.5b, above the prior year’s ¥364.0b and ¥32.2b. That supported the idea that specialty and higher value activities could lift earnings, although the slight net margin slip from 8.9% to 8.8% kept the profitability part of that thesis only partly backed. Overall the evidence pointed in both positive and negative directions.
The key lesson is to track whether higher value initiatives appear in both profit and margin. When evaluating a similar case elsewhere, compare management’s margin statements with the reported net margin trend rather than focusing only on headline revenue.
What Ajinomoto’s Price Already Bakes In
Ajinomoto now trades at ¥5,280, and the selected Narrative’s Fair Value sits above that level based on its own assessment. The focus has shifted toward high margin ABF materials, biopharma services and premium foods acting as the main profit engines.
The Narrative leans on Ajinomoto’s ability to keep expanding Functional Materials and CDMO capacity while holding pricing power despite ongoing cost pressure. The key question for any buyer is whether high margin ABF profitability can stay resilient enough for that higher figure to make sense.
"The current valuation suggests the market discounts the durability of Ajinomoto’s high margin ABF profitability, its growing Healthcare earnings pillar and its improved ROE and ROIC. Very strong, mix driven growth in Ajinomoto’s ABF materials for high performance AI servers and networks, together with the ramped Gunma plant and the planned third ABF site in Gifu from 2032, points to continued monetisation of high margin Functional Materials capacity that can support revenue and earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Ajinomoto And A Different Kind Of Staple
Ajinomoto points you toward everyday eating habits as an investment clue. Nearby in the pantry, another giant quietly leans on the same idea.
Instead of sauces and seasonings, this business focuses on snacks and drinks. It aims to match dependable demand with regular cash returns to shareholders.
Big brands across cupboards and fridges help that approach feel steady. Scale lets the group spread marketing, production and distribution costs across many products.
If Ajinomoto covers one side of the pantry, this player may cover another. The open question is how that mix of staples fits your long-term plan.
That argument has a Narrative and a number behind it. → See the company one Narrative values 52% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com