


Is Western Digital (WDC) Undervalued After AI Storage Competition Fears?
Western Digital has delivered one of the bigger long term runs in the storage sector, yet a sharp pullback in recent weeks has put fresh focus on whether the current share price lines up with what its earnings can support. With the stock now reacting to shifting expectations around AI infrastructure spending and memory competition, the question is how much of its profit story is already built into today's valuation.
- Over the past 3 years the stock has returned about 9 times an initial investment, which makes it important to ask whether the earnings profile can underpin that kind of rerating.
- Western Digital is leaning heavily on AI driven demand for high capacity hard drives and long term contracts with cloud providers, which can influence how investors think about future margins and the durability of its profit base.
- There is a second opinion on Western Digital worth weighing. See what analysts think Western Digital's shares could be worth.
The issue now is whether the current price of Western Digital shares is adequately supported by the earnings power that the business is generating today and that investors expect it to produce over time.
If you want to stress test this same earnings question across other AI infrastructure plays, compare Western Digital with the companies in the 55 AI infrastructure stocks.
Is Western Digital Still Cheap on Earnings?
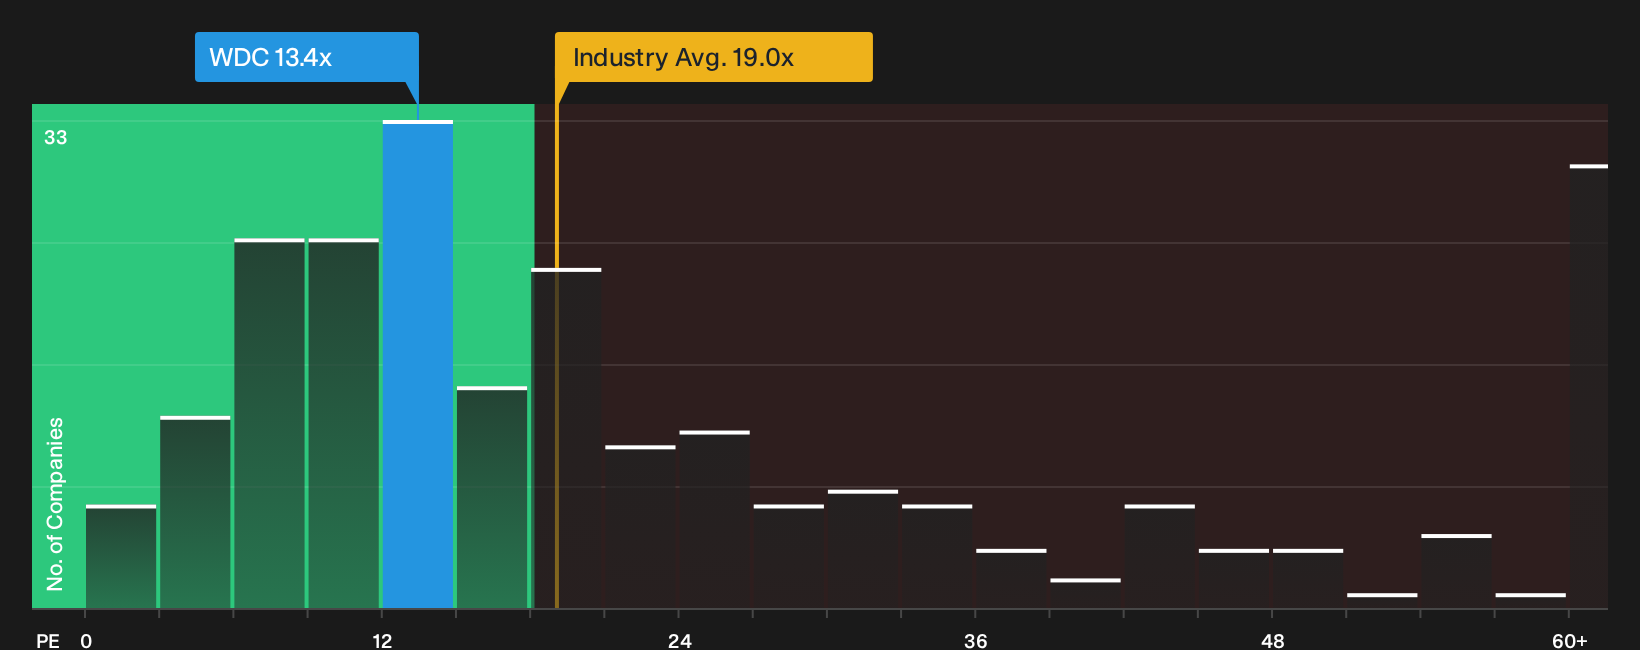
P/E suits Western Digital because earnings are the clearest way investors are now sizing up its AI storage opportunity against the risks of tougher memory competition. On this yardstick, the stock trades on a P/E of 13.4x, which is well below both the peer group average of 28.7x and the broader tech industry at 19.0x. That gap suggests investors are pricing in a meaningful margin of safety relative to other hardware and chipmakers that are also tied to AI infrastructure spending.
Because the current multiple screens below the level implied by a fair P/E for Western Digital's growth profile and risk mix, the shares appear undervalued on this framework. Recent pressure on the stock after Chinese rivals and Toshiba flagged capacity expansions has not closed that discount, so the market is still treating the AI storage story with more caution than it is for many peers. To judge whether that caution is justified, you would need to weigh how durable Western Digital's earnings power really is against that lower P/E. Explore the numbers behind Western Digital's P/E valuation.
The Western Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Western Digital pick up where the P/E puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully mispriced in either direction. Each scenario links its number to a specific view on where Western Digital's expansion, margin profile and key risks might go next, so you can return to those assumptions as new information comes through.
Western Digital attracts two very different readings, with one group seeing plenty left in the AI HDD story and the other far more cautious on how long current economics can last.
Bull case: 50% undervalued
"Higher adoption of Western Digital's larger capacity, high-value ePMR and UltraSMR drives, with 32TB and 40TB products already in high volume and further capacity gains planned, supports a richer product mix that can lift gross margin and net margins..."
Discover why this Narrative puts Western Digital at 50% undervalued.
Bear case: roughly fairly valued
"Here is the tension. That golden hour is priced as if it lasts..."
Explore why this Narrative puts Western Digital at roughly fairly valued.
One more Western Digital angle that could shift your view
You have a sense of what Western Digital looks like on current earnings and competing narratives, but broker models a few years out offer a separate benchmark to compare against the present share price. Explore where analysts expect Western Digital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com