


Why TerraVest Industries (TSX:TVK) Is Back In The Spotlight
Recent commentary has zeroed in on TerraVest Industries (TSX:TVK) trading on a P/E of about 26.3x, sparking questions about whether its long term share performance and cash generation profile support that valuation.
At around CA$114.61 per share, TerraVest Industries has seen a mixed stretch, with the share price return rising 3.92% over the past week but declining 30.34% year to date. At the same time, a very strong 3-year total shareholder return of about 234.42% hints at earlier momentum that contrasts with the recent pullback and sharpens the focus on whether a 26.3x P/E still reflects current sentiment around its earnings and cash generation.
Compare TerraVest Industries' rich P/E with peers that also screen for quality and valuation discipline by scanning our hand-picked 5 high quality undervalued stocks in similar sectors.
Bulls point to TerraVest Industries' 3-year run and diversified equipment footprint, while bears focus on the sharp year-to-date slide and a 26.3x P/E. Which case does the current valuation lean toward?
Price-to-Earnings of 26.5x: Is it justified?
TerraVest Industries is trading on a P/E of about 26.5x, which sits against a last close of CA$114.61 and has sparked debate about whether the market is asking investors to pay a premium for its earnings profile.
The P/E ratio compares TerraVest Industries' share price to its earnings per share, so it effectively shows how much investors are paying today for each dollar of current profit. For a diversified equipment and services group operating across HVAC, compressed gas, processing gear and field services, earnings are a key anchor because cash flows can be influenced by contract timing, capital intensity and one-off items.
TVK is described as expensive against the broader North American Energy Services industry, where the average P/E sits at 18.9x. It is labelled good value relative to a closer peer set with an average of 27.3x. That mix suggests the market is pricing TerraVest Industries at a premium to the wider sector but roughly in line with companies viewed as more directly comparable on business mix and quality.
Result: Price-to-Earnings of 26.5x (ABOUT RIGHT)
See what the numbers say about this price — find out in our valuation breakdown.
Still, TerraVest Industries faces pressure points, including a sharp year-to-date share price decline and reliance on capital intensive equipment markets, which could test sentiment if orders soften.
Find out about the key risks to this TerraVest Industries narrative.
Another view on TerraVest Industries' value
The P/E story for TerraVest Industries looks tight, yet the SWS DCF model paints a very different picture. At around CA$114.61, the stock is flagged as trading about 68.5% below an estimated future cash flow value of roughly CA$363.47. That is a wide gap. Is the market missing something, or is the model too optimistic?
For readers who want to see how a cash flow model gets to such a different answer compared with a simple earnings multiple, Look into how the SWS DCF model arrives at its fair value.
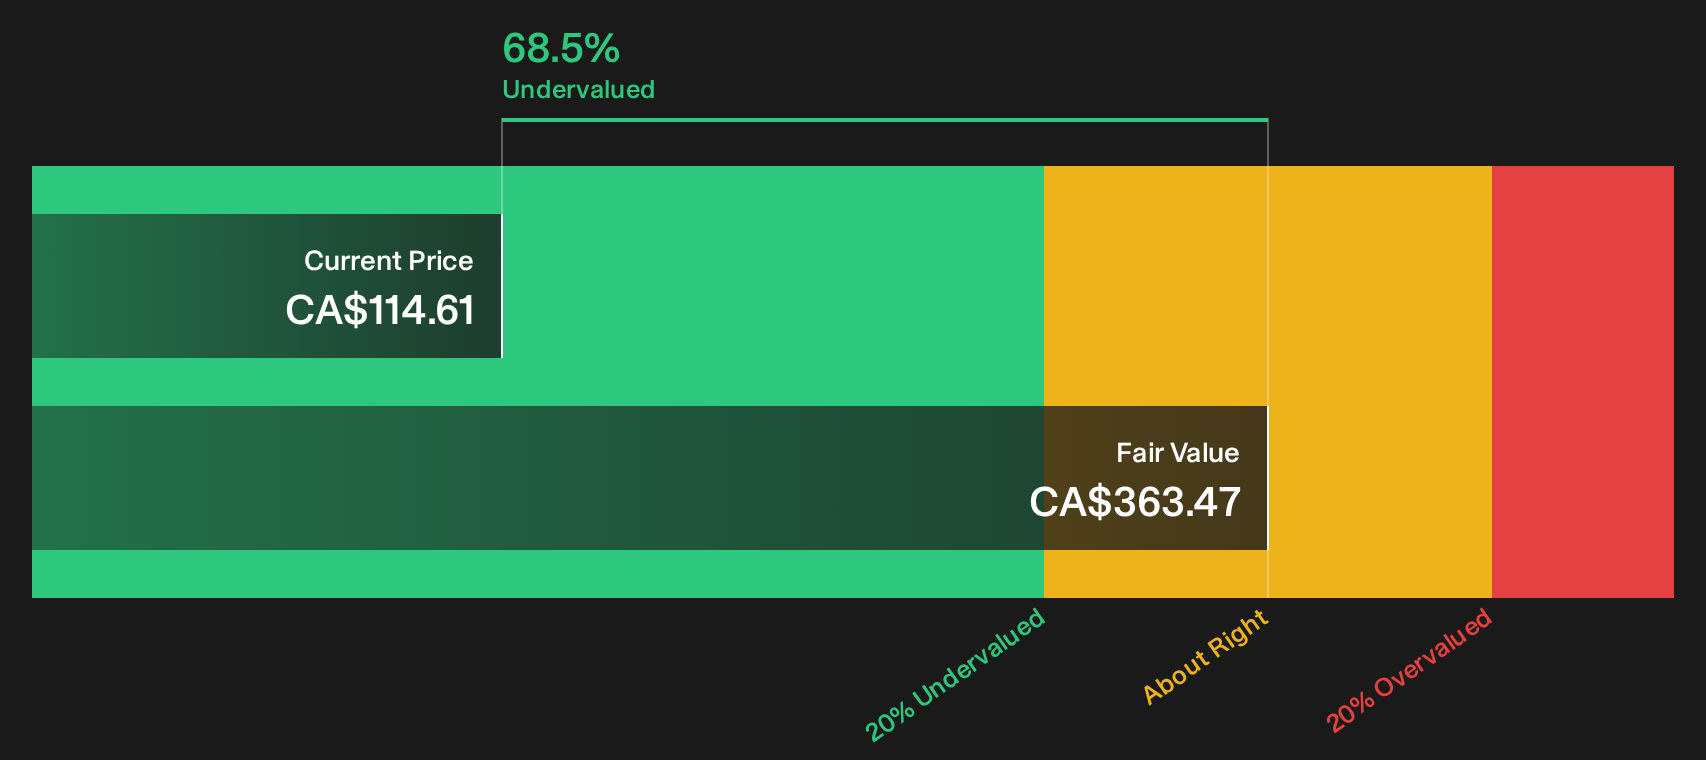
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TerraVest Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Uncertain whether TerraVest Industries' recent pullback and rich P/E signal opportunity or risk, and want your view grounded in hard numbers rather than headlines? Move quickly from curiosity to conviction by weighing both sides of the story with our breakdown of 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond TerraVest Industries?
If TerraVest Industries has sharpened your focus on valuation and quality, do not stop here. Put that momentum to work by scanning a wider field of opportunities.
- Target resilient balance sheets and steady fundamentals by reviewing our list of solid balance sheet and fundamentals (8 results) built to spotlight financially robust businesses.
- Hunt for potential mispricing by checking the 10 high quality undiscovered gems that combine strong fundamentals with limited market attention.
- Zero in on stability and cash returns by using the 3 dividend fortresses focused on higher yielding companies with durable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com