


Regions Financial (RF) Q3 Earnings Beat Meets A Quiet Stock Price
Regions Financial came into its Q3 2026 report with a banking thesis built on solid profitability and a modest valuation. The share price barely flinched, rising about 0.5% to US$27.45 by the latest close. That muted move sits alongside a quarter where basic earnings per share reached US$0.72 and net interest margin, a crucial profitability gauge for lenders, held at 3.68%. The real story sits in the balance sheet. Total loans reached about US$99.8b while non performing loans declined to US$597m, sharpening the expectation gap between a quiet trading day and improving credit quality.
If you like what Regions Financial just reported on profitability and credit quality but want a wider group of lenders with strong balance sheets and fundamentals, compare this quarter with our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
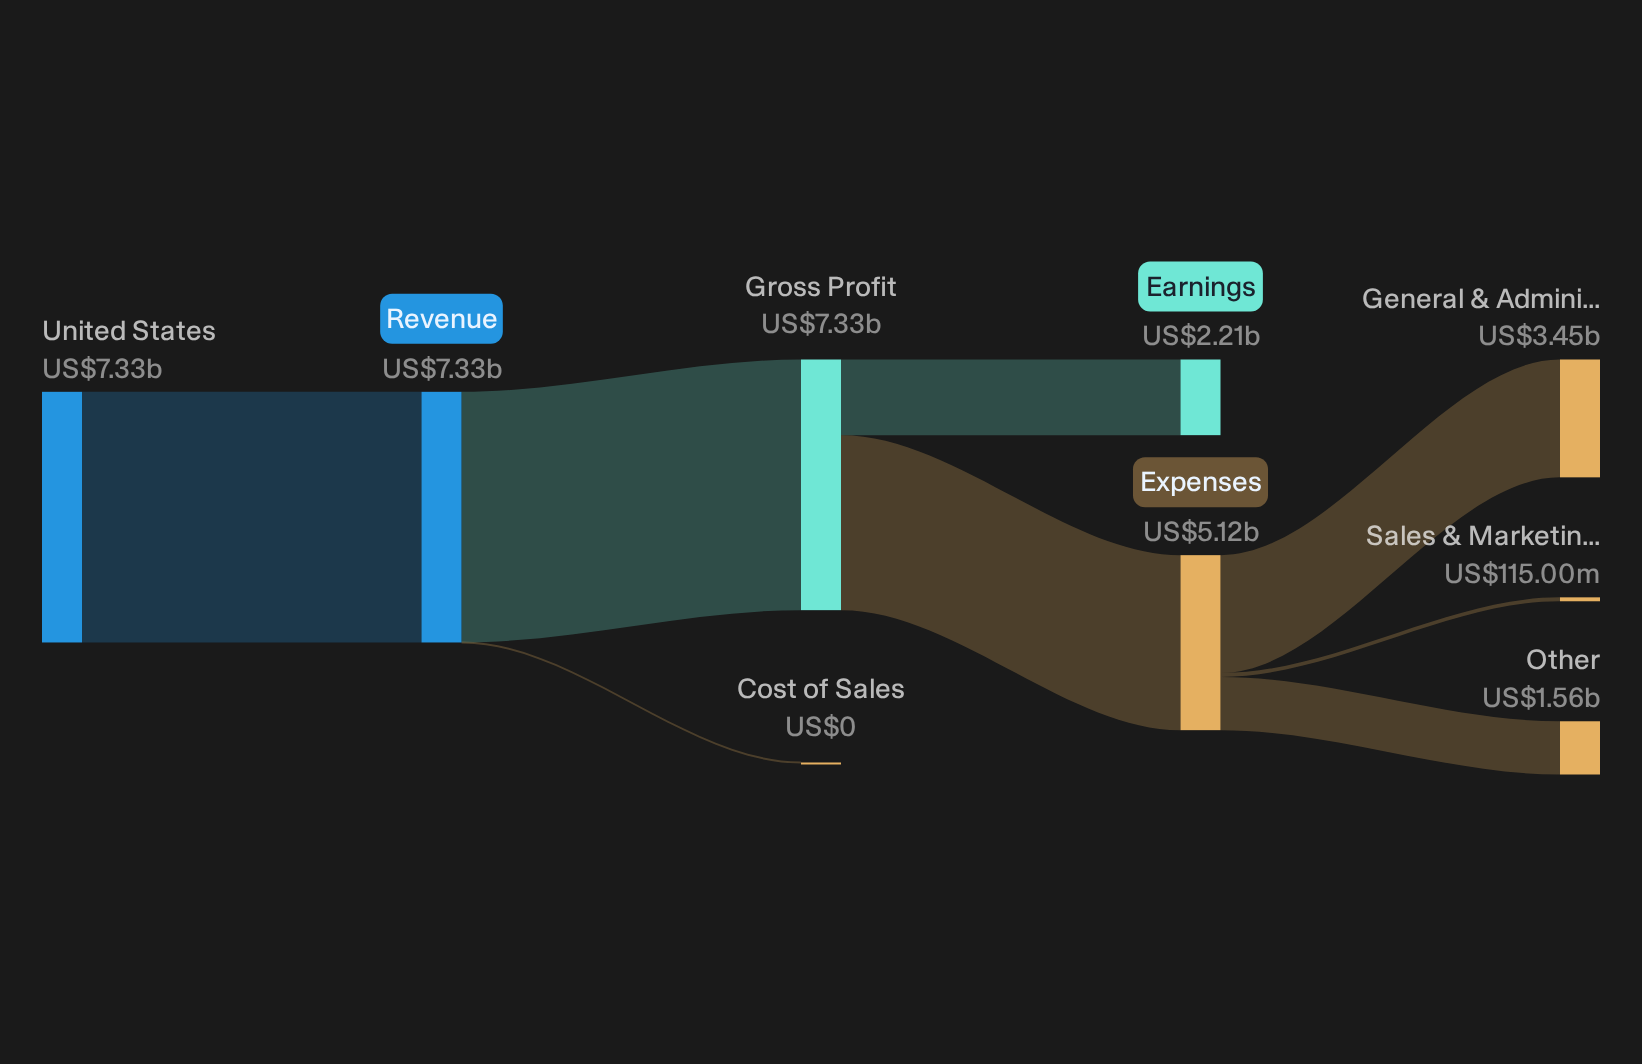
- Total Revenue (Q3 2026 vs. Q3 2025): US$1,905m vs. US$1,811m (up about 5%)
- Net Income ex. Extra Items (Q3 2026 vs. Q3 2025): US$611m vs. US$548m (up about 12%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.72 vs. US$0.62 (up about 16%)
- Net Interest Margin, NIM (Q3 2026 vs. Q3 2025): 3.68% vs. 3.59% (slight improvement in lending profitability)
Skip the 10,000 words. Ask Charlie what Regions Financial revealed about its new cloud platform.
Regions Financial: Testing The Bullish Playbook
The upbeat story says Regions Financial can use tech upgrades and fee businesses to steadily improve earnings quality.
"Early investments in digital banking infrastructure and the current testing and piloting of a cloud-based core deposit platform, alongside the new commercial lending system, point to further potential gains in customer acquisition, operational efficiency and cost control that could support net interest margin and operating leverage."
Q3 results move this from concept to early evidence. Net interest margin held at 3.68% while net interest income rose 2% quarter on quarter. Adjusted noninterest income grew 3%, with record capital markets and strong treasury management revenue. Expenses were roughly flat, so operating leverage is starting to show, even as the core deposit platform remains in pilot phase.
Bear Case: Revenue, Costs And Tech Execution Risk
Bears worry that modernization and fee ambitions will not offset revenue and cost pressure.
"The story assumes Regions Financial can keep improving efficiency through technology and scale. However, the latest efficiency ratio did not meet expectations even with a 3.66% net interest margin and strong pretax pre provision income. If operating costs stay higher than anticipated or technology spending does not translate into leaner operations, this could compress net margins and limit earnings growth."
Recent numbers only partly answer that concern. Adjusted pretax, pre-provision income reached US$870m and EPS beat consensus, yet Q3 revenue of US$1,905m was only modestly above last year and below forecasts. The efficiency ratio miss from earlier quarters still hangs over the story, since Q3 commentary focuses on flat expenses rather than visible cost takeout from the cloud program.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Find Banks The Market Ignores
Regions Financial just showed that earnings strength and balance sheet insight may not shift its share price. The real opportunity is in stocks that could be undervalued before the market updates their pricing.
- Company 1 - 49% below our estimate - uses a digital loan and deposit platform to attract small business relationships while managing credit and expense ratios.
- Company 2 - 46% below our estimate - leans on a relationship-focused banker model as it absorbs a merger and pursues fee-based growth from specialty lending and technology-supported services.
- Company 3 - 39% below our estimate - operates a device trade-in and refurbishment platform that connects to subsidy programs and demand for recycled electronics.
Three companies from the same screener. Open every one of the 33 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com