


Take Two Interactive Software (TTWO) Could Be 26% Undervalued On Earnings Pressure
Take-Two Interactive Software (TTWO) came under pressure after traders focused on its upcoming November 9 earnings release, as expectations for weaker EPS and revenue weighed on sentiment despite the stock’s premium valuation.
At around US$205 per share, Take-Two Interactive Software has given holders a 1-year total shareholder return that declined 21.45%, even though the 3-year total shareholder return is up 46.02%. This points to longer term momentum that has cooled as investors reassess earnings risk and a premium valuation ahead of the November 9 update.
Compare Take-Two Interactive Software’s premium pricing and recent pullback with a hand-picked group of potentially better valued peers using the 32 high quality undervalued stocks.
Bulls point to Take-Two Interactive Software’s long run of shareholder gains and premium status. Bears highlight the recent share price slide and expected earnings drop. Which side does the current valuation actually support next?
Most Popular Narrative: 26% Undervalued
According to the most followed narrative on Take-Two Interactive Software, the stock at $205.28 is trading well below an assessed fair value of $276.97, with that view built on a detailed look at Grand Theft Auto VI and the wider games portfolio.
Much of the thesis around the share price depends heavily, but not totally, on GTA VI. There is a strong reliance in the investment thesis on this one game. It could underperform, it could be delayed again. The gaming landscape in 2026 is far more crowded than it was in 2013 when the previous version was released. Take-Two sits at a genuinely pivotal inflection point. Over many years it has made heavy investment, including strategic acquisitions, and is approaching the moment of payoff. GTA VI could reshape its financial profile for the better half of the next decade.
See why 93 investors see Take-Two Interactive Software as 26% undervalued.
According to Clive_Thompson, who authored the narrative, that fair value uses a revenue growth rate input of 47.09%, a discount rate of 8.98% and a profit margin assumption of 12.31%, which together support a valuation that sits well above both the current share price and the recent 1 year return profile.
That framework also treats Take-Two Interactive Software as a business with meaningful recurring bookings from existing titles and mobile, even though recent reported net income of $320.4m was a loss and the group value score sits at 2 out of 6, which signals that the model is leaning heavily on future profitability rather than current earnings power.
Pulling this together, the most popular narrative frames the recent 21.45% total shareholder return decline over 12 months as a reset inside a longer 3 year gain of 46.02%, with the implied 26% discount_to_fair_value leaving limited room for disappointment if GTA VI or broader execution falls short of those inputs.
Result: Fair Value of $276.97 (UNDERVALUED)
Still, the Take-Two Interactive Software story hinges on GTA VI execution and a return to profitability after the recent net income loss of $320.4m.
Find out about the key risks to this Take-Two Interactive Software narrative.
Another View: Take-Two Interactive Software Looks Expensive On Sales
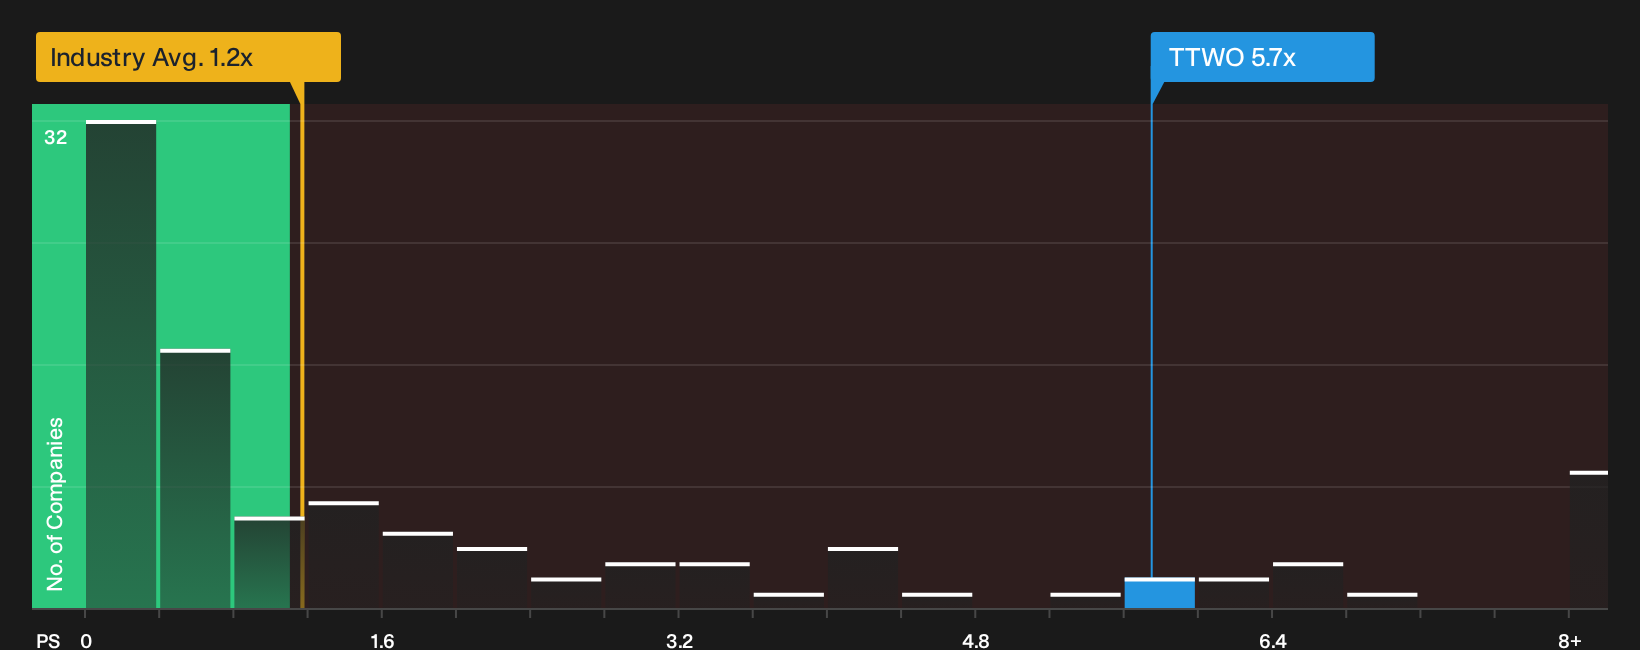
The first narrative leans on a fair value of $276.97, yet the simple sales multiple sends a cooler message. Take-Two Interactive Software trades on a P/S of 5.7x, while peers sit around 2.5x and the fair ratio points nearer 3.5x. That gap suggests investors are paying up, so how comfortable are you with that premium?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Take-Two Interactive Software is split, with one camp focused on risks and another on potential rewards. Consider reviewing both sides of the data and weighing the 3 key rewards and 1 important warning sign carefully.
Looking for more investment ideas beyond Take-Two Interactive Software?
If Take-Two Interactive Software has you rethinking your portfolio balance, now is the moment to scan for other opportunities before the next wave of results lands.
Use these targeted stock lists to pressure test your current positions and spot ideas that fit your risk, income, and quality preferences.
- Target stronger value by comparing Take-Two against a broader pool of potentially mispriced opportunities through the 32 high quality undervalued stocks.
- Seek more predictable cash flows by focusing on companies that make regular payouts, starting with the 8 dividend fortresses.
- Reduce portfolio stress by prioritizing resilient businesses with sturdier finances using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com