


Box (BOX), Why Is The Latest Box Update Drawing Attention?
Box (BOX) just landed a full-bank deployment at The Ogaki Kyoritsu Bank in Japan, where the institution is adopting Box Enterprise Advanced as its AI-ready platform for managing unstructured content.
Recent price action suggests investors are responding to these kinds of AI centric deployments. Box’s share price is at US$39.56, with a 30 day share price return of 14.14% and a 1 year total shareholder return of 21.24%. This points to momentum that has been building rather than fading.
Scan how other AI driven content and infrastructure plays are moving by checking out the hand picked 55 AI infrastructure stocks along with Box’s latest banking win.
Box has rallied hard into this Ogaki Kyoritsu win, yet the shares still trade at roughly a 31% intrinsic discount while sitting almost on top of analyst targets. Is the market’s caution misplaced or earned?
Most Popular Narrative: 2% Overvalued
Box last closed at $39.56, while the most followed narrative pegs fair value at about $38.71 using an 8.9% discount rate. The market price is slightly ahead of that estimate.
Accelerating take up of Box AI units and agentic workflow capabilities, including new guardrails, prompt injection detection and integrations with agents such as Claude, ChatGPT, Gemini and Harvey, can increase usage based monetization and support revenue growth.
Rising demand to migrate content and workflows off older on premises ECM and file server systems that limit AI use, supported by systems integrator partners handling complex replacement projects, can support multi year billings and revenue growth.
See why 7 investors see Box as 2% overvalued.
Result: Fair Value of $38.71 (OVERVALUED)
Still, if bundled productivity suites continue to crowd out Box in core accounts, or if AI features fail to justify premium pricing, this upbeat narrative could unravel.
Find out about the key risks to this Box narrative.
Another View: Box Through The SWS DCF Lens
The analyst narrative frames Box as roughly 2% overvalued versus a US$38.71 fair value, yet the SWS DCF model points in the opposite direction. On that cash flow view, Box at US$39.56 trades about 31% below an estimated US$57.53 future cash flow value. Which yardstick do you trust more when the gap is this wide?
For a closer look at how that cash flow based estimate is built and what assumptions drive it, Look into how the SWS DCF model arrives at its fair value..
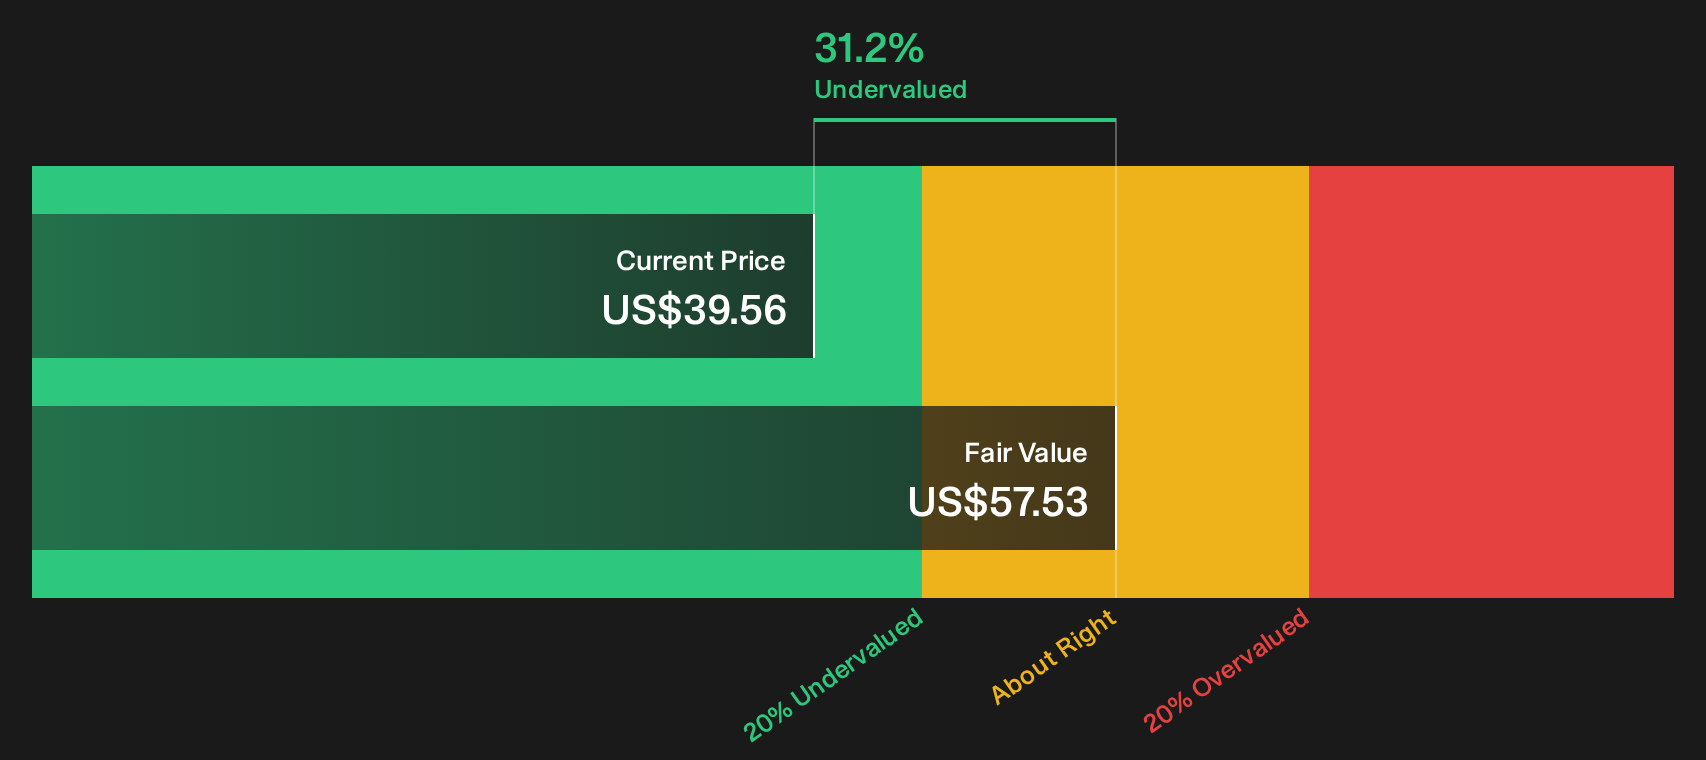
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Box for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Box valuation so far. If you want to move quickly and shape your own view, start with the full picture across 2 key rewards and 2 important warning signs.
Looking for more Box investment ideas?
If Box has sharpened your interest in AI and content platforms, broaden your watchlist now so you do not miss the next opportunity hiding in plain sight.
- Target mispriced quality and scan for financially strong opportunities that still look cheap using the 33 high quality undervalued stocks.
- Prioritize resilience and stress test your holdings against a 32 resilient stocks with low risk scores to see which businesses may better handle shocks.
- Hunt for under-the-radar potential and surface 20 high quality undiscovered gems before they sit on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com