


Aflac’s Q3 2026 Earnings: What to Expect
Aflac Incorporated (AFL) is a leading supplemental health and life insurance provider operating primarily in the United States and Japan. The company offers insurance products covering accidents, cancer, critical illnesses, disability, hospital stays, and other medical expenses not fully covered by primary health insurance. The company has a market cap of $59.2 billion, and it operates mainly in the United States and Japan, with Japan being its largest and most profitable market.
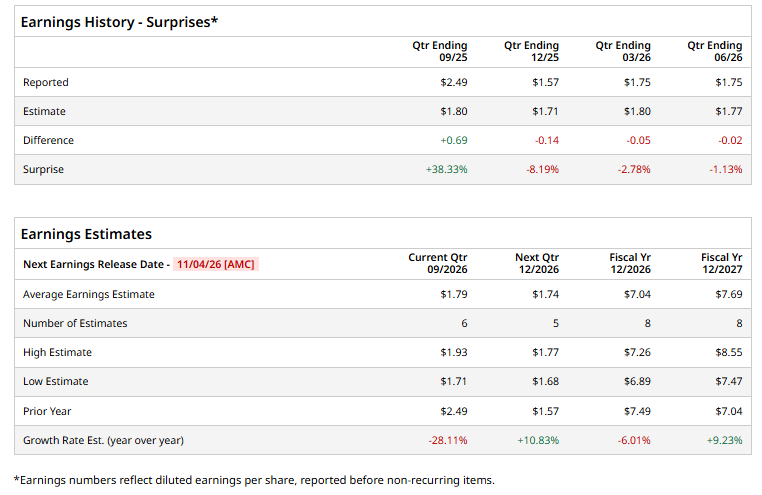
AFL is expected to release its Q3 2026 earnings on Wednesday, Nov. 4, after the market closes. Ahead of this event, analysts anticipate the company will generate earnings of $1.79 per share, representing a drop of 28.1% from $2.49 per share reported in the same quarter last year. The company has surpassed the Street’s bottom-line estimates in three of the past four quarters, while missing on another occasion.
For fiscal 2026, analysts expect the company to report an EPS of $7.04, indicating a 6% decrease from $7.49 reported in fiscal 2025. However, its EPS is expected to rebound and grow 9.2% year over year to $7.69 in fiscal 2027.
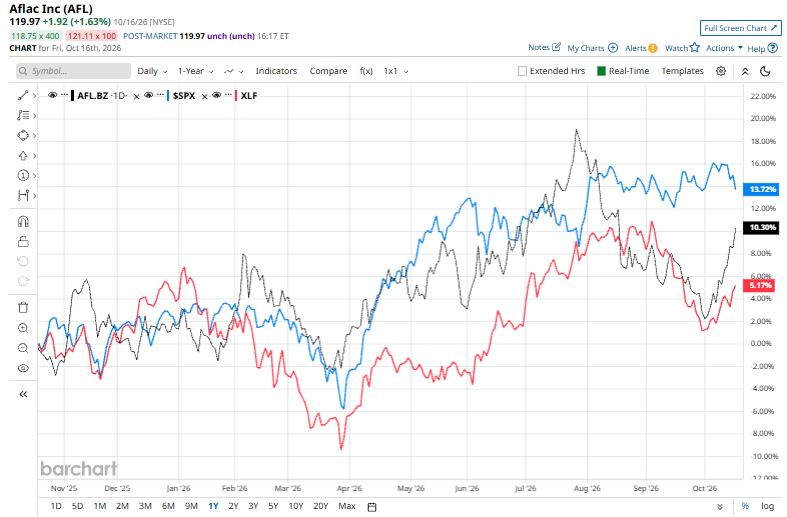
Shares of Aflac have surged 12.4% over the past 52 weeks, trailing the S&P 500 Index’s ($SPX) 15.5% rise but outpacing the State Street Financial Select Sector SPDR ETF’s (XLF) 7.3% return during the same time frame.
Aflac’s weak performance over the past year reflects declining net premiums earned, which fell at an annual rate of 6.3% over the past five years, signaling weakness in its underwriting business. Investor concerns have also been fueled by expectations that book value per share will decline 7.5% over the next 12 months and the company’s elevated debt-to-equity ratio, which highlights potential balance-sheet risks.
Analysts’ consensus view on AFL is neutral, with an overall “Hold” rating. Among 17 analysts covering the stock, two suggest a “Strong Buy,” one suggests a “Moderate Buy,” ten recommend a “Hold,” and four analysts give a “Strong Sell.” It currently trades above the mean price target of $117.50. The Street-high price target of $138 represents a 15% premium from the prevailing market prices.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.