


Zeta Global Holdings (ZETA) Could Be 2% Below Fair Value On Goldman Upgrade
Goldman Sachs’ upgrade of Zeta Global Holdings (ZETA) has pushed the stock back into focus for investors, as the firm pointed to stronger enterprise traction and expanding partnerships that support its longer term outlook.
Recent trading tells a more nuanced story. Zeta Global Holdings’ share price has cooled in the very short term, with a 1-day move down 5.19% and a 7-day decline of 3.87%. At the same time, the 90-day share price return of 46.73% and year-to-date gain of 59.77% point to momentum that has been building over 2026. A 1-year total shareholder return of 78.51% and a 3-year total shareholder return near 3x suggest the latest Goldman Sachs upgrade and product launches like AthenaOS are landing on top of an already strong multi-year rerating.
Spot fresh AI-driven momentum beyond Zeta Global Holdings by scanning our hand picked 37 AI small caps, which are also tying enterprise software to real customer outcomes.After a run that has already delivered a near 3x total return over three years, plus a sharp upgrade driven by AthenaOS and new alliances, how much of Zeta Global Holdings’ upside is still on the table versus already priced in?
Most Popular Narrative: 2% Undervalued
Zeta Global Holdings closed at $31.81 against a widely followed fair value of $32.43, which leaves only a small valuation gap but still hinges heavily on how well its AI driven marketing stack and data assets translate into durable earnings power.
Zeta is benefiting from rapid enterprise adoption of AI-powered marketing automation and omnichannel personalization, which is driving large, multiuse case deployments (like OneZeta) and fueling double-digit revenue growth along with expanded customer lifetime value. The intensifying focus on data privacy and the shift to first-party data (due to regulatory changes and third-party cookie deprecation) position Zeta's proprietary data and integrated platform as a favored, compliant alternative, supporting client retention and differentiated pricing, which positively impacts both revenue and margins.
See why 157 investors see Zeta Global Holdings as 2% undervalued.
The narrative uses an 8.65% discount rate and a fair value of $32.43 to frame that small 2% discount, so it leans on the idea that current growth assumptions, margins and AI adoption already do much of the heavy lifting in the model. A consensus price target of $32.43 that sits close to the latest trade and a forecast revenue growth rate around 17.6% a year mean most of the enthusiasm around Athena, Palantir powered infrastructure, and Senso looks incorporated into expectations rather than ignored.
Given that same storyline assumes profit margins move from roughly breakeven today to about 10.6% over the coming years, while earnings are forecast to reach $270.6 million by around October 2029, the bar for execution is not low. To line up with those projections, investors would also need to be comfortable with the shares trading on a future P/E of 43.8x those earnings, which sits above the 29.5x multiple cited for the wider US Software industry.
Result: Fair Value of $32.43 (UNDERVALUED)
Still, Zeta Global Holdings faces real tripwires if tougher privacy rules curb the usefulness of its data or if larger software rivals compress pricing power in AI marketing tools.
Find out about the key risks to this Zeta Global Holdings narrative.
Another View: What Multiples Say About Zeta Global Holdings
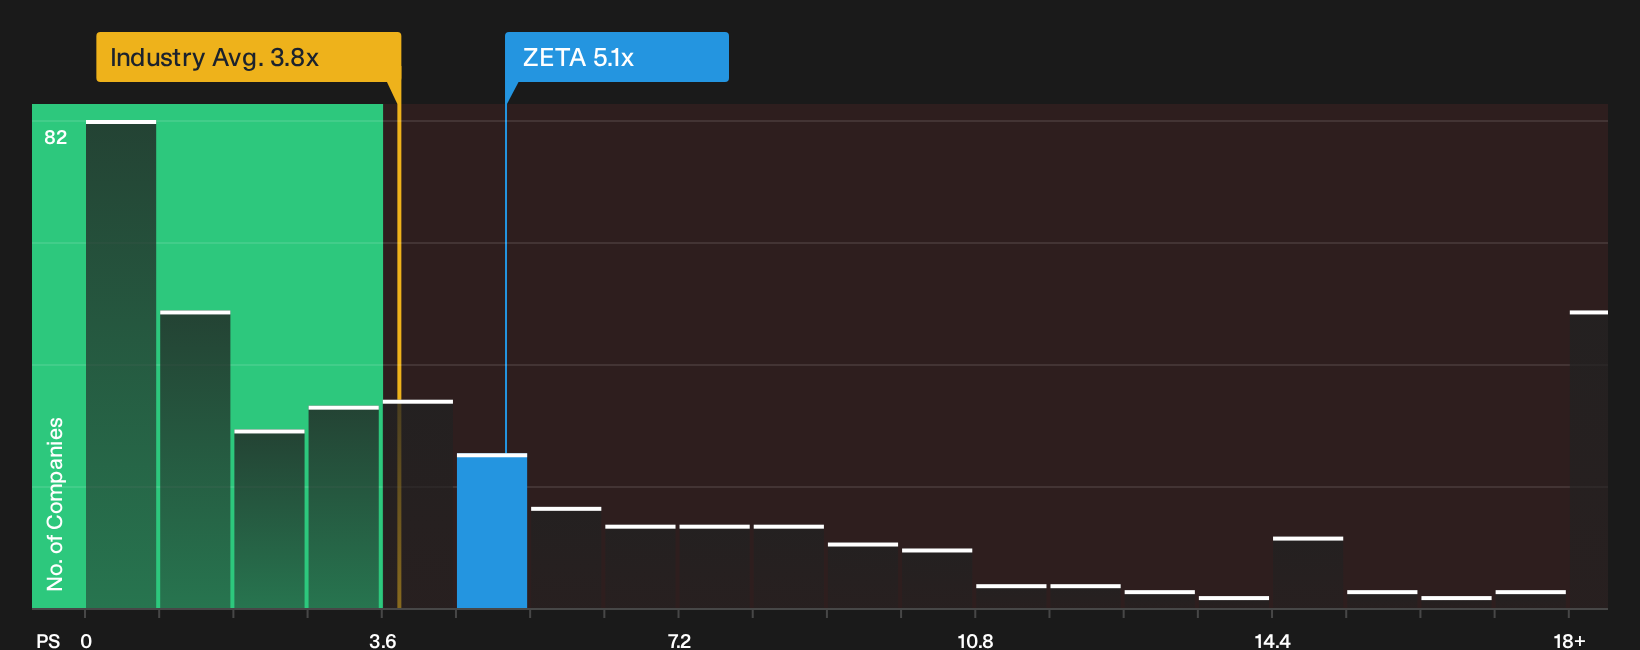
DCF work points to upside for Zeta Global Holdings, yet the simpler P/S lens tells a tighter story. The stock trades on a P/S of 5.1x, which is higher than the US Software industry at 3.8x and above its own fair ratio of 4.8x. That mix suggests investors are already paying a premium for growth, so the key question is whether future execution will fully support that richer tag.
For a closer look at how these valuation checks stack up in practice, including how that P/S premium could cut both ways for future returns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around Zeta Global Holdings leaves you on the fence, consider acting quickly and test the numbers yourself before sentiment shifts. To focus on what the market is already excited about, start with the 3 key rewards
Looking for more investment ideas beyond Zeta Global Holdings?
Zeta Global Holdings may already be on your radar, but you give yourself a real edge when you line it up against other clear, data driven ideas.
- Target potential mispricing by scanning a focussed group of 33 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Build a sturdier income stream by reviewing 8 dividend fortresses that combine higher yields with an emphasis on resilience.
- Reduce portfolio stress by concentrating on 32 resilient stocks with low risk scores that our models flag for steadier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com