


Chevron (CVX) Faces A Valuation Test Following The Oil Spike
Oil at more than US$100 a barrel after attacks near the Strait of Hormuz has pulled renewed attention to Chevron (CVX), where record production and a long dividend track record frame the current debate.
Chevron has ridden this oil spike with clear momentum, with a roughly 44% year to date share price return and a 53% total shareholder return over the past year, which signals that investors are pricing in stronger cash generation and a higher perceived resilience to recent geopolitical shocks.
Scan for other energy players showing similar momentum to Chevron by checking the hand picked 41 power grid technology and infrastructure stocks alongside this oil spike and dividend story.
After a 52 week high and a US$225 share price, Chevron now forces a choice. Do you pay up for the momentum, or wait and risk missing more of the move while you test the valuation maths?
Most Popular Narrative: 1% Undervalued
Chevron’s most followed narrative pegs fair value at about $227.71 a share using a 7.24% discount rate, which sits just above the last close at $224.99 and presents today’s premium oil price in relation to a model that still characterizes the stock as slightly undervalued.
Long duration projects such as the 20 year, 2.67 GW take or pay power agreement with Microsoft and the planned US$7b growth phase in Venezuelan joint ventures are expected to add contracted or low cost production and power sales that can support future revenue, earnings and free cash flow.
See why 471 investors see Chevron as 1% undervalued.
Result: Fair Value of $227.71 (ABOUT RIGHT)
Still, this Chevron story can change quickly if large projects such as Venezuela or Tengiz slip on timing, or if hydrocarbon demand underperforms analyst assumptions.
Find out about the key risks to this Chevron narrative.
Another View: Chevron Through The P/E Lens
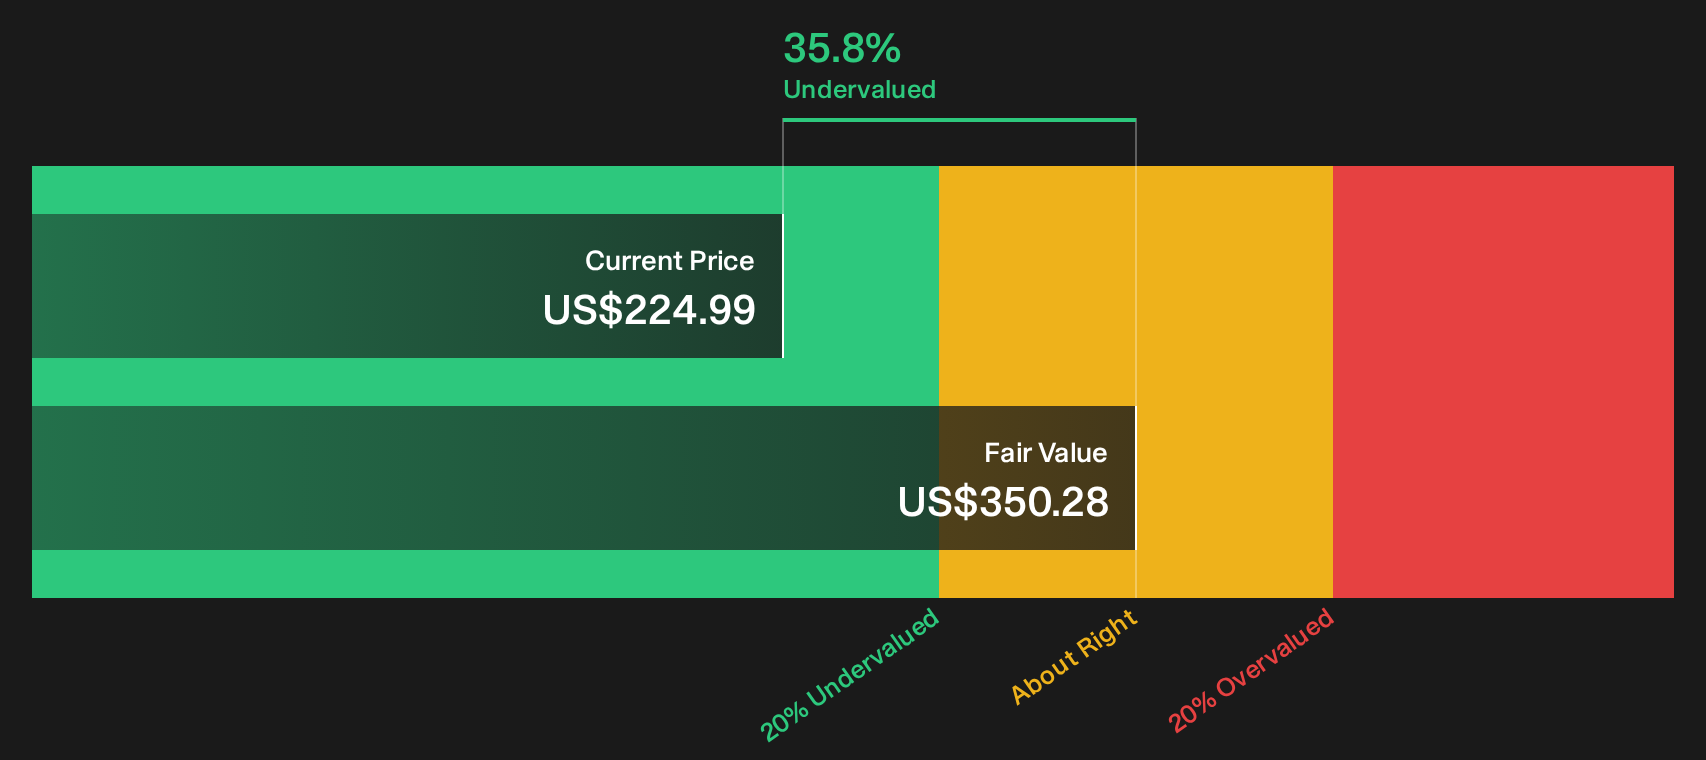
The SWS DCF model presents Chevron as attractive, with the shares trading 35.8% below an estimated future cash flow value of $350.28. In contrast, the P/E perspective is very different. At 21.4x earnings, CVX trades well above the US Oil and Gas industry on 12.5x and peers on 18.9x, and exactly in line with a 21.4x fair ratio. That combination suggests investors are paying a premium multiple for cash flows that the model treats as discounted, so the question becomes which signal to prioritize when oil eventually cools.
Look into how the SWS DCF model arrives at its fair value. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Plenty of investors see Chevron’s current setup as attractive, yet the mix of concerns and bright spots is what really matters for your decision. Take a moment to weigh both sides of the story and ground your own stance in the data with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Chevron?
If Chevron has your attention, do not stop there. Broaden your watchlist with other opportunities that match your risk, income and value preferences.
- Target income resilience with a shortlist of companies screened as potential 8 dividend fortresses that may suit investors focused on regular cash returns.
- Seek better value by scanning the 33 high quality undervalued stocks and spot shares the model flags as trading below estimated intrinsic worth.
- Dial down volatility risk by reviewing the 32 resilient stocks with low risk scores, where the focus is on balance sheet strength and more stable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com