


TRIAL Holdings (TSE:141A), Why Is It Getting Fresh Attention?
TRIAL Holdings (TSE:141A) drew fresh attention after releasing preliminary sales figures for September and the first quarter, showing year-over-year gains in both comparable and all-store sales across its retail network.
Recent trading has been mixed for TRIAL Holdings, with the share price easing over the past month but still showing a 20.3% share price return over 90 days and a 65.3% total shareholder return over the past year. This suggests that investors have been reassessing both its growth prospects and risk profile as the new sales figures land.
Scan how TRIAL Holdings stacks up against other retailers posting broad-based sales gains by checking the hand-picked 14 high quality undervalued stocks that also pair demand with balance sheet strength.
TRIAL Holdings has strong recent gains on the board, yet the share price has cooled over the past month. Is that a sensible pause to wait through, or a chance to lock in exposure before valuations adjust?
Price-to-Earnings of 125x: Is it justified?
Valuation on TRIAL Holdings currently leans heavily on the earnings multiple, with the stock trading on a P/E of 125x at a last close of ¥3,585. That is a rich tag for any retailer, and it raises a straight question for you as a shareholder or prospective buyer about what kind of earnings trajectory is being factored in.
The P/E ratio shows how much investors are paying today for each unit of current profit. For a consumer retail group with exposure to mega centers, hypermarkets, supermarket centers, and a growing Retail AI segment, this metric gives a quick read on how the market is weighing earnings against perceived potential across those activities.
TRIAL Holdings is described as expensive on this measure when set against several reference points. The stock carries a 125x P/E compared with 12.8x for the wider JP Consumer Retailing industry and 20.2x for its peer group. It also trades well above the estimated fair P/E of 21.8x, a level that regression analysis suggests the valuation could move toward if expectations around profit growth and risk were to normalise.
Explore the SWS fair ratio for TRIAL Holdings.
Result: Price-to-Earnings of 125x (OVERVALUED)
Still, the story around TRIAL Holdings can shift quickly if quarterly revenue growth slows from its recent 5.9% pace or if Retail AI execution disappoints expectations.
Find out about the key risks to this TRIAL Holdings narrative.
Another View on TRIAL Holdings: Cash Flows Tell a Different Story
The earnings multiple paints TRIAL Holdings as expensive, yet the SWS DCF model points the other way. At ¥3,585, the stock sits about 57.8% below an estimated future cash flow value of roughly ¥8,494.78, which frames the current quote as a discount rather than a premium.
Both signals cannot be right in the same way. If profits grow as forecast at 31.3% per year while revenue only tracks at 5.9% a year, how long can such a wide gap between a 125x P/E and the DCF estimate really hold?
Look into how the SWS DCF model arrives at its fair value.
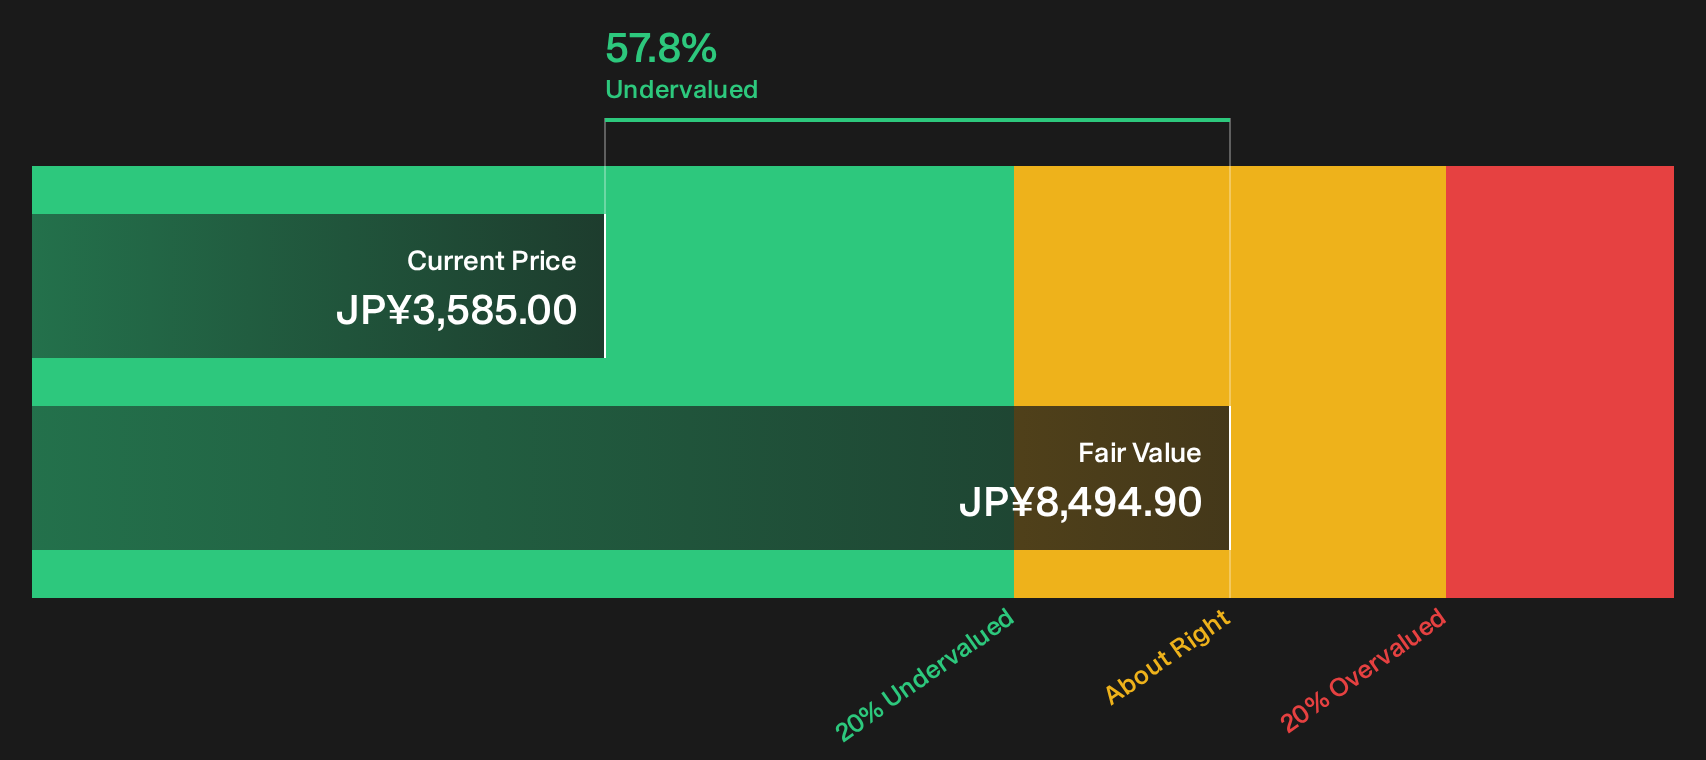
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TRIAL Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early consensus are forming around TRIAL Holdings. If you want to move before the crowd settles on a story, weigh both sides of the ledger with the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond TRIAL Holdings?
If TRIAL Holdings has sharpened your focus on valuation and quality, do not stop here. The wider market holds plenty of opportunities that might fit your goals even better.
- Target potential value opportunities by scanning companies that pair quality fundamentals with attractive pricing through the 14 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (21 results) that can hold up when conditions get tougher.
- Spot future potential early by filtering for 73 high quality undiscovered gems before they draw broader market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com