


Why Broadcom Stock Is a Good Buy Now
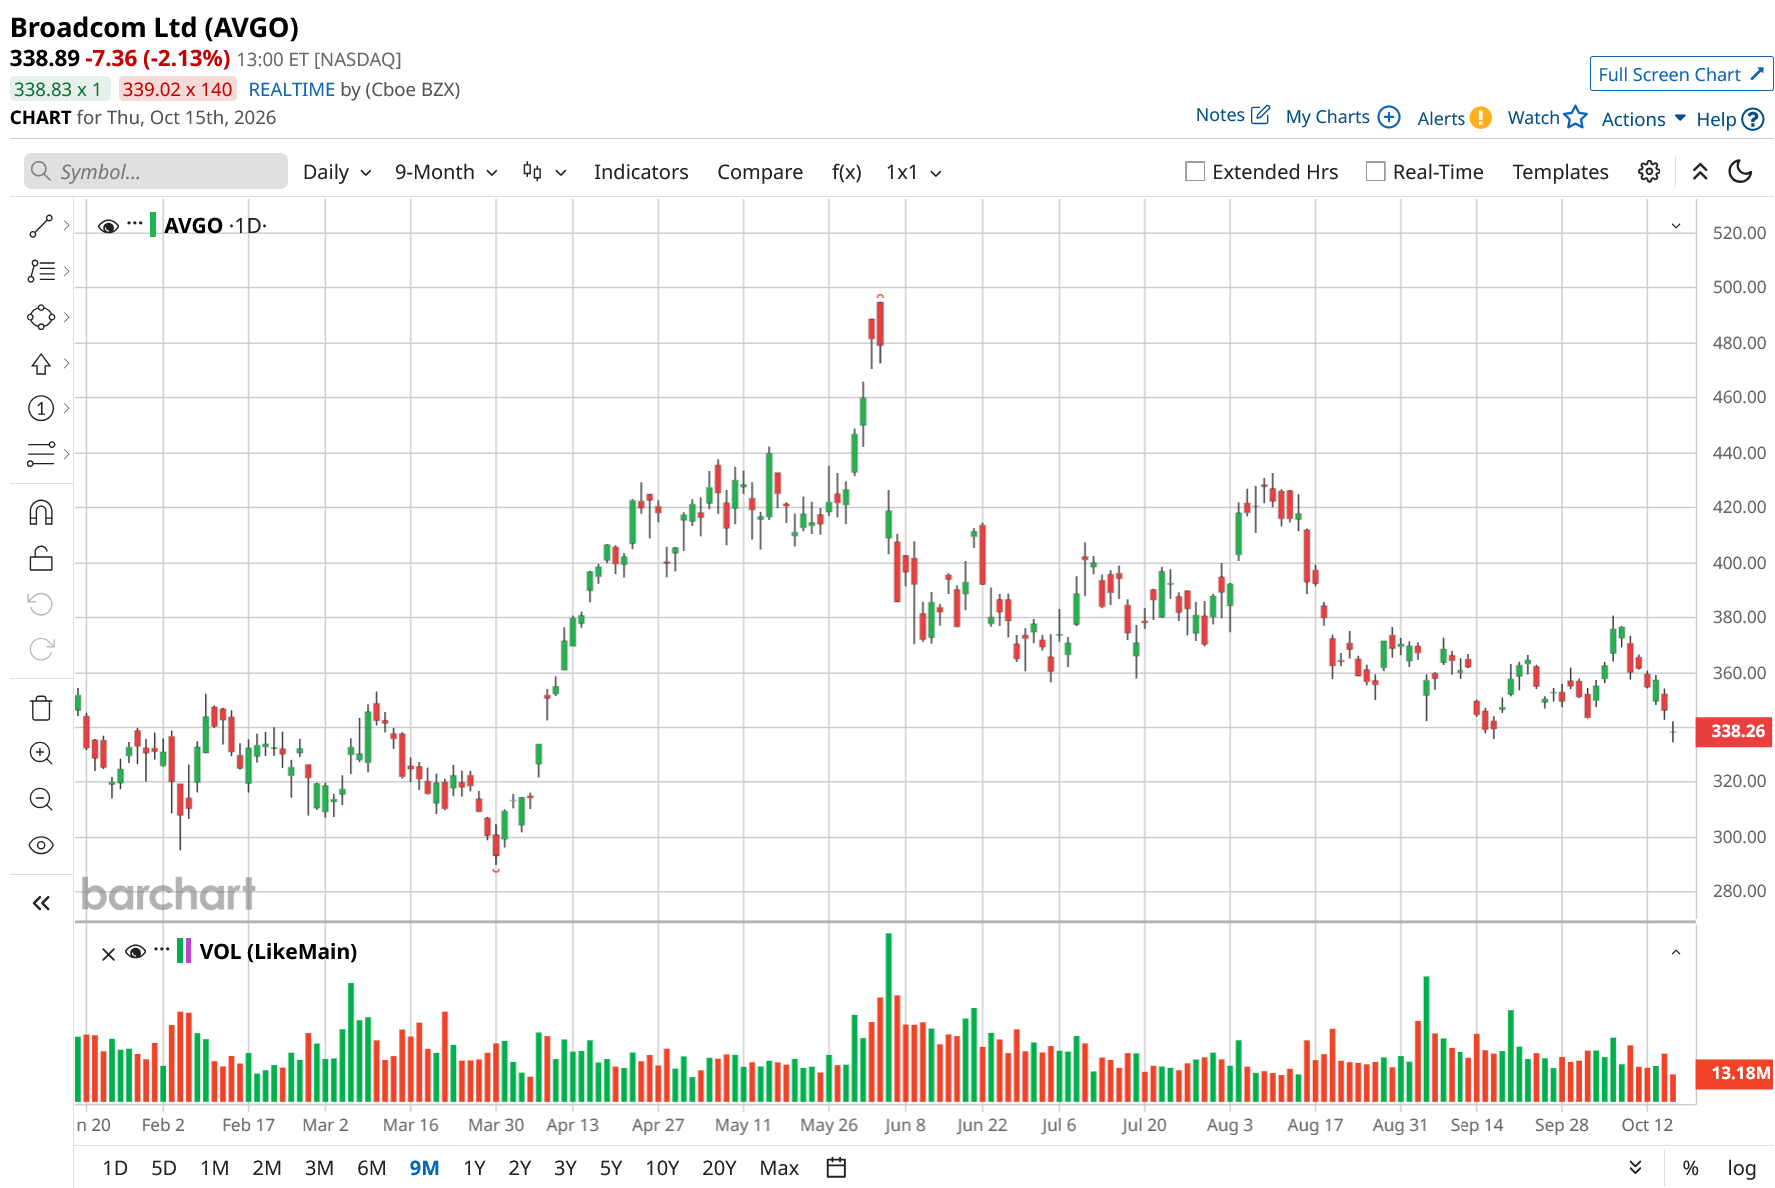
Broadcom (AVGO) stock has fallen more than 30% from its high on concerns about the sustainability of artificial intelligence (AI) spending and intensifying competition in the custom AI chip market. While AVGO stock has pulled back, the company’s growth prospects remain solid.
Broadcom continues to benefit from strong demand for AI infrastructure, expanding relationships with major technology companies, and growing adoption of its custom accelerators and networking solutions. Further, the decline in its share price has made Broadcom’s valuation more attractive.
XPUs to Power Broadcom Higher
Broadcom’s custom AI accelerators, known as XPUs, are emerging as a major driver of its growth.
The company’s latest reported quarterly results and outlook reflect the scale of this opportunity. AI semiconductor revenue rose 221% year-over-year (YoY) and 54% sequentially to $16.7 billion.
Custom accelerators are playing a key role in its growth. Shipments to Broadcom’s six XPU customers rose more than 3.5 times YoY and accounted for about 73% of its AI revenue during the quarter. AI networking revenue also grew more than 2.5 times over the same period, reflecting strong demand for the infrastructure needed to support AI workloads.
The planned product deployments across several major AI and cloud computing companies strengthen Broadcom’s growth outlook. The company expects to increase shipments of Ironwood accelerators to Anthropic, expand high-volume deliveries of its eighth-generation TPU products to Alphabet's (GOOG) (GOOGL) Google, continue shipments of custom chips for OpenAI, and begin production shipments of Meta’s (META) MTIA accelerators for inference and recommendation workloads.
These deployments highlight the breadth of Broadcom’s custom AI opportunity and ease competition concerns.
Broadcom’s product pipeline and expanding deployments suggest that demand remains strong. Management expects both XPU and AI networking revenue to triple YoY in the fourth quarter. Based on this, the company projects quarterly AI revenue of $21.7 billion, representing annual growth of 236%.
Broadcom’s expanding product pipeline and growing customer deployments suggest that demand for its AI solutions remains strong. Management expects both XPU and AI networking revenue to triple YoY in the fourth quarter. As a result, the company projects quarterly AI revenue of $21.7 billion, representing 236% annual growth.
The longer-term outlook points to an even larger opportunity. Management expects AI revenue to reach $58 billion in fiscal 2026, up 186% YoY and above its previous forecast of $56 billion.
Looking further ahead, Broadcom expects AI revenue to double to $115 billion in fiscal 2027 and then double again to $230 billion in fiscal 2028. Continued demand for custom AI accelerators and growing sales of AI networking products are expected to drive this expansion.
Strong AI semiconductor revenue and operating leverage are also expected to support significant earnings growth. Management anticipates that earnings per share (EPS) will exceed $30 in fiscal 2028, marking a substantial increase from current levels.
For context, analysts expect Broadcom to report EPS of $17.45 in fiscal 2027. If Broadcom achieves EPS of $30 in fiscal 2028, that would represent approximately 72% YoY growth. This would be notable given the increasingly challenging comparisons Broadcom faces as its earnings base expands. Analysts already expect EPS to grow by more than 84% in fiscal 2026 and 68% in fiscal 2027.
Overall, solid demand for Broadcom’s custom AI accelerators and AI networking solutions, expanding customer relationships, and operating leverage position the company for substantial revenue and earnings growth over the next several years.
Broadcom’s Valuation Offers Potential Upside
Broadcom is well-positioned to deliver strong earnings growth in the coming years. At the same time, its current valuation appears low and attractive relative to its growth prospects. AVGO shares trade at 34.2 times forward earnings, a relatively modest multiple given the company’s strong earnings growth outlook.
Moreover, Broadcom trades at a significant discount to peers such as Marvell (MRVL), which commands a forward price-to-earnings multiple of 87.2. This valuation gap and solid earnings growth trajectory suggest that Broadcom has upside potential.
Buy AVGO Stock Now
Broadcom’s strong AI revenue growth, expanding XPU deployments, and rising demand for AI networking solutions provide a solid foundation for sustained earnings growth. Its valuation also appears attractive relative to its growth prospects and industry peers, indicating solid upside potential.
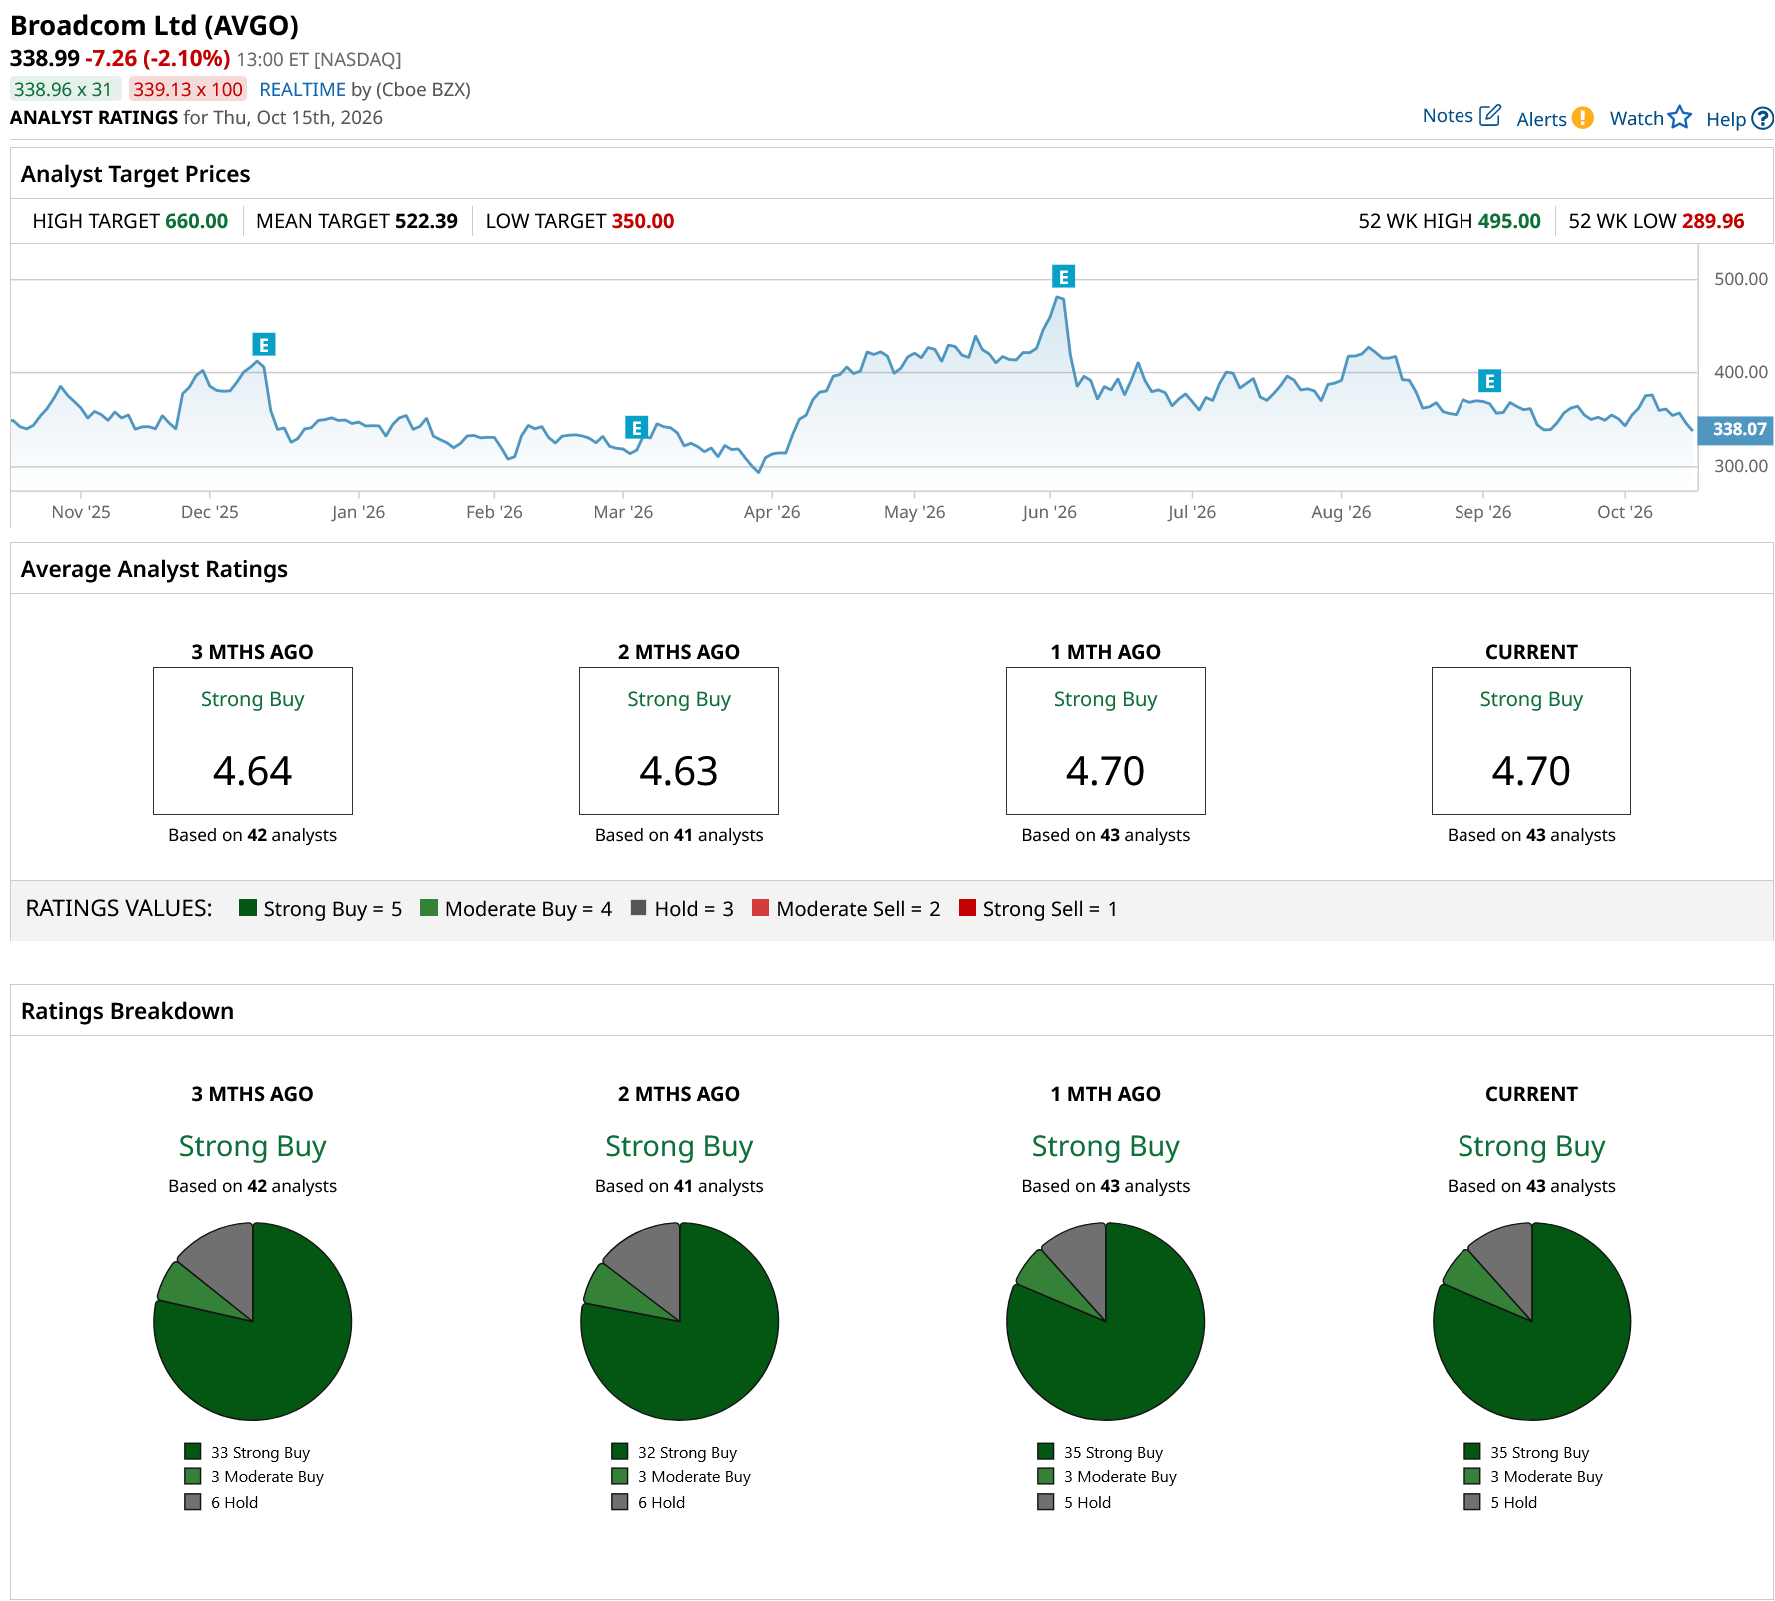
Most analysts covering AVGO stock are bullish and maintain a “Strong Buy” recommendation.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.