


Low Redemptions Could Be A Game Changer For Ashmore Group Stock (LSE:ASHM)
- Ashmore Group reported a quarterly update showing a US$0.50b increase in assets under management, supported by broad-based net inflows and the lowest redemptions in over 15 years. This signals stronger client engagement in its emerging markets funds.
- The unusually low level of investor redemptions highlights how Ashmore Group’s fee-earning base is stabilising around its core emerging markets capabilities, even as management still faces pressure on fee margins and variable performance fees.
- We now consider how Ashmore Group's investment narrative could shift as improved client retention supports its fee-earning base.
Ashmore Group Investment Narrative Recap
To own Ashmore Group, you need to believe its specialist focus on emerging markets, combined with a long operating history and solid balance sheet, can keep client money in its funds even when conditions are choppy. The latest AuM update, with net inflows and very low redemptions, supports that belief by pointing to healthier client activity.
The key near term swing factor is whether this stabilising flow picture feeds into more reliable management fees rather than relying on seed capital gains. Pressure on fee margins and performance fees remains the main operational risk, especially given past revenue, EBITDA and EPS pressure. The new data helps sentiment, but it does not remove that earnings quality question.
The recent commentary around seed capital gains is worth keeping in mind alongside the AuM update. Ashmore Group benefited from these gains, which supported reported profit, yet any moderation here would expose how dependent the business is on its recurring fee engine from emerging market strategies.
For you as a shareholder, the link to catalysts is straightforward. If improving net flows and lower redemptions rebuild the fee base, then reliance on volatile seed gains and performance fees becomes less acute. If flows soften again or margins compress further, the combination of pressured earnings, a high dividend payout and questions around dividend coverage stays front of mind.
What The Current Ashmore Group Forecasts Are Really Asking You To Believe
Ashmore Group's analyst template leans on two big moving parts: a projected 12.4% annual uplift in revenue over the next 3 years and a sharp reset in profitability as margins compress. The same forecasts see earnings today of £113.5 million stepping down to consensus earnings of £54.0 million by 2029, which is a decline of £59.5 million in profit even as the top line is expected to expand.
Ashmore Group's narrative projects £188.1 million revenue and £54.0 million earnings by 2029. This rests on 12.4% yearly revenue growth and a £59.5 million earnings decrease from £113.5 million today.
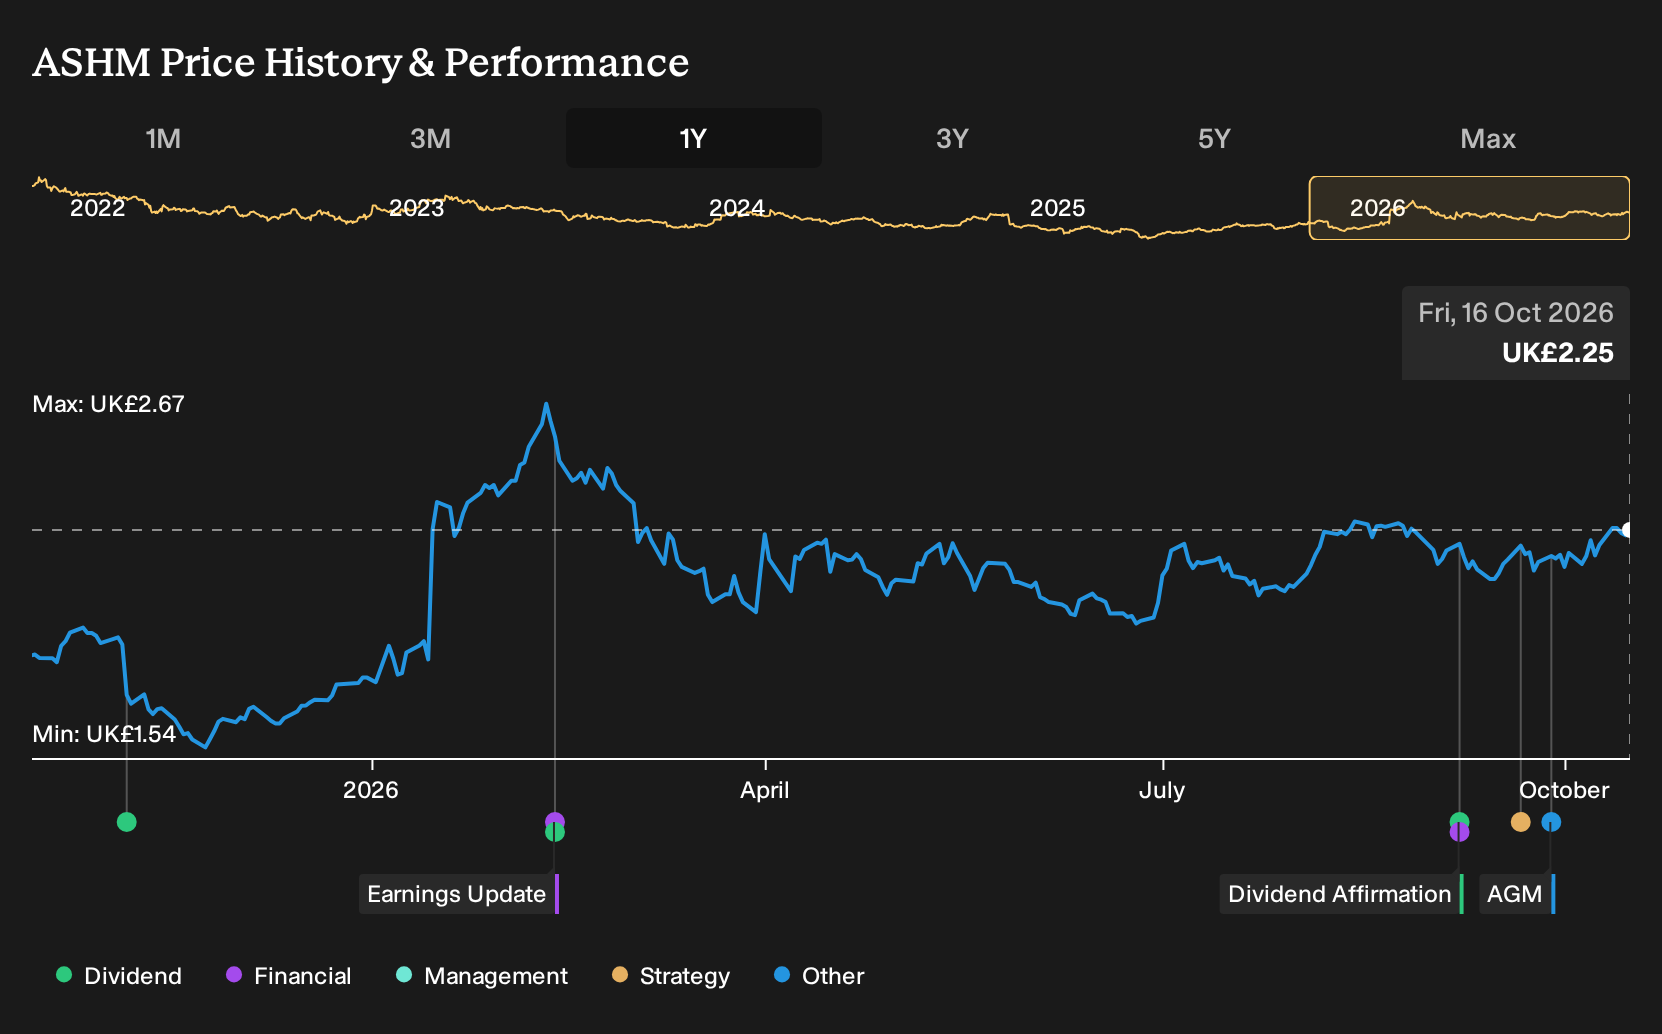
Uncover why Ashmore Group's fair value indicates an 8% potential downside to its current price, a premium that leaves little room for error.
Exploring Other Perspectives
One alternate narrative leans hard on seed capital as a positive catalyst for Ashmore Group. Those bullish analysts were pencilling in revenue of about £202.5 million and earnings of £86.7 million by 2029, compared with the £188.1 million and £54.0 million in the baseline view. That is a far more optimistic stance. Your takeaway is simple: reasonable people can read the same pre update data and reach very different conclusions. It is worth exploring both sets of assumptions and asking how the latest AuM news might eventually push forecasts closer to one side or the other.
Explore 5 other Ashmore Group fair value estimates, including one that suggests as much as 50% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ashmore Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ashmore Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ashmore Group's overall financial health at a glance.
Looking For More Ideas Beyond Ashmore Group?
If the Ashmore Group story has you thinking about where else to put fresh capital to work, casting a wider net with the Simply Wall St Screener can help you compare this investment case with other opportunities that match your risk tolerance and income needs.
- For investors who want value and quality to line up, scan a curated set of 7 high quality undervalued stocks that pair stronger balance sheets with more attractive pricing.
- If capital preservation sits near the top of your priorities, focus on a 4 resilient stocks with low risk scores that filters for resilient businesses with fewer red flags.
- For those who care most about financial strength, build a shortlist from a list of solid balance sheet and fundamentals (9 results) that surfaces companies with sturdier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com