


How Investors May Respond To ADM Stock Feed Amino Acid Venture
- Archer-Daniels-Midland announced a joint venture with CJ CheilJedang to expand U.S. feed-grade amino acid production, targeting stronger cost competitiveness and more resilient supply for food, feed and industrial customers.
- The move deepens Archer-Daniels-Midland's precision fermentation footprint at a time when the business is already preparing for an earnings update and focusing on higher value Nutrition and bio-based ingredients.
- Investors will now be watching how Archer-Daniels-Midland's investment narrative could shift as this amino acid joint venture builds out U.S. capacity.
Archer-Daniels-Midland Investment Narrative Recap
To own Archer-Daniels-Midland, you need to believe the business can keep turning a volatile grain and energy backdrop into relatively steady cash flow from crush, trading, and higher value Nutrition ingredients. The amino acid joint venture fits that story by pushing deeper into specialty, fermentation based inputs that tie up customers on long contracts and lean on ADM’s existing logistics network.
The more immediate swing factor still sits in crush, biofuels policy, and Carbohydrate Solutions margins, while headline risk around litigation and governance lingers in the background. The new FERC intervention filing around pipeline fuel charges looks operationally small, so it does not really change the near term risk reward picture.
The regulatory move with the Federal Energy Regulatory Commission is the freshest data point tied to this theme. ADM is a firm natural gas transportation customer on the Panhandle Eastern Pipe Line system, and its request to intervene one day out of time focuses on changes to the Fuel Reimbursement Adjustment Tracker that could affect delivered energy costs.
For you, the read through is simple. Reliable, reasonably priced gas supply matters for crush plants, fermentation assets, and wet milling sites that underpin ADM’s biofuels and Nutrition catalysts. Any shift in pipeline terms that materially raises input costs or adds volatility would run counter to the margin improvement story management is pursuing.
Archer-Daniels-Midland’s current analyst storyline points to revenues of US$89.2b and earnings of US$2.3b by 2029, anchored on revenue growth of 2.8% per year and an earnings increase of US$0.5b from the US$1.8b reported today.
Uncover why Archer-Daniels-Midland's fair value indicates a 3% potential downside to its current price, suggesting that this premium may not hold.
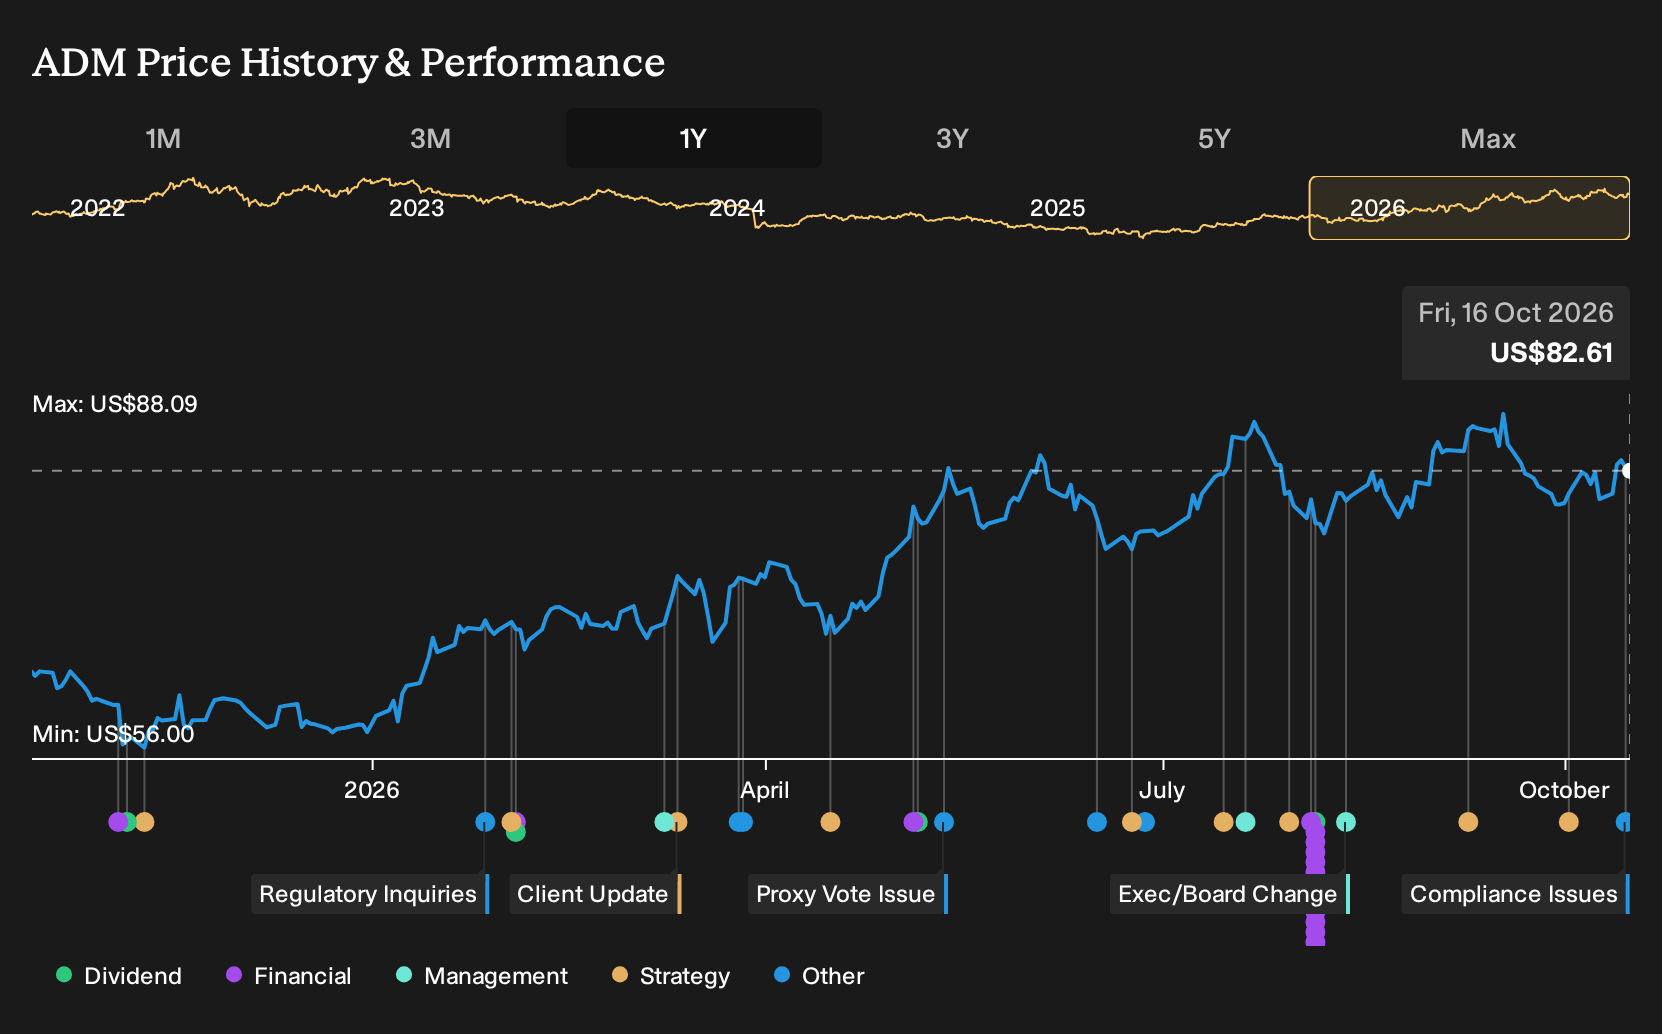
Exploring Other Perspectives
Some of the most optimistic analysts see Archer-Daniels-Midland’s big swing factor in aggressive Nutrition expansion, not in pipeline fuel costs. Before this FERC move, they were modeling revenue of about US$119.0b and earnings of US$2.6b by 2029. That is far above consensus, which shows how widely views can spread. Use this regulatory twist as a prompt to compare those assumptions and decide which version of ADM’s future you find more convincing.
Explore 3 other Archer-Daniels-Midland fair value estimates, including one that suggests as much as 41% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Archer-Daniels-Midland research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Archer-Daniels-Midland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Archer-Daniels-Midland's overall financial health at a glance.
Looking for more Archer-Daniels-Midland style ideas?
If Archer-Daniels-Midland’s mix of real assets, cash generation, and Nutrition exposure appeals to you, it can help to widen the lens and scan for other businesses with similar risk and reward profiles. The Simply Wall St Screener lets you filter for exactly the kind of financial traits, balance sheet strength, and income potential that match your own playbook instead of relying on headlines alone.
- If you want potential value with quality fundamentals, start by reviewing a 33 high quality undervalued stocks that pair solid balance sheets and cash flows with prices that screens flag as appealing.
- For investors who care most about capital preservation and a smoother ride, consider scanning a 32 resilient stocks with low risk scores that screen well on volatility and business risk metrics.
- If a resilient income stream matters to you, focus on a 8 dividend fortresses that currently offer yields above 5% with a focus on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com