


What Hexcel Doubters Overlooked
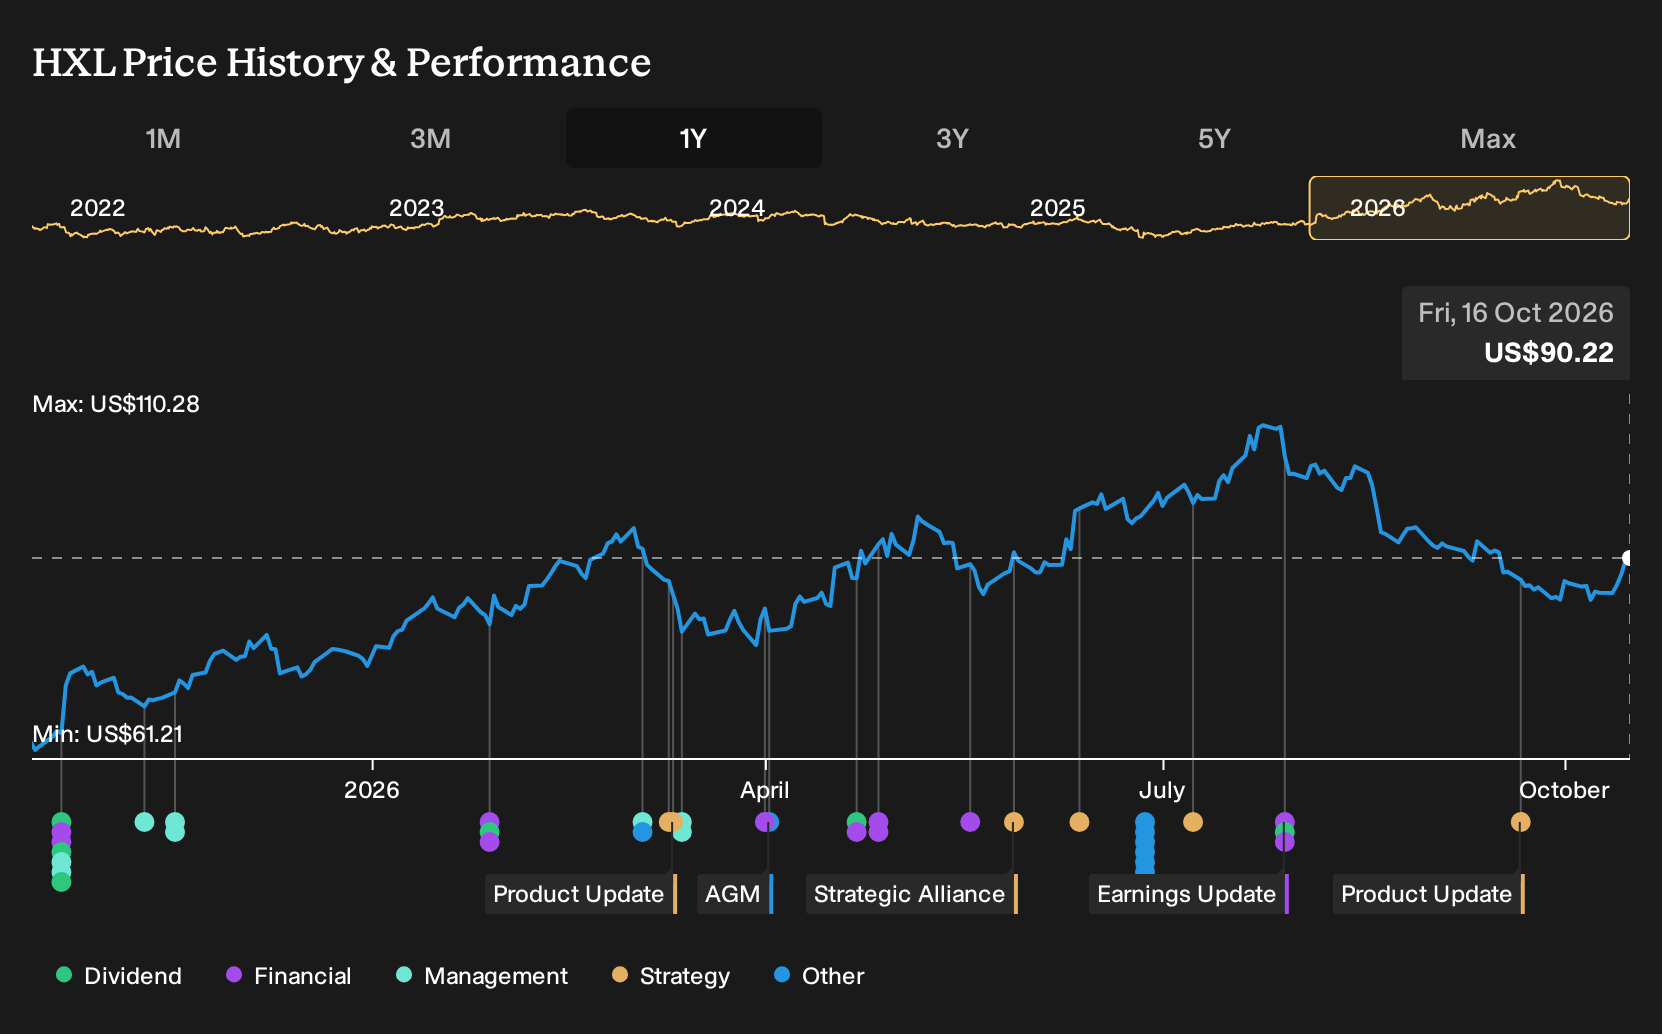
If Hexcel sat on your watchlist instead of in your portfolio, the last twelve months may feel like a missed call. Investors who held Hexcel over the past year are up 47.3%, including dividends. That move arrived after analysts were debating whether rising air travel and defense budgets would translate into real composite demand or get capped by supply chain bottlenecks and fixed price contracts. The key question now is whether earlier conviction about sustained aircraft production increases was the business assumption that mattered most.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Hexcel harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Argument Hexcel Investors Actually Faced
The shares cost US$61.21 at the start of the period, so any view on Hexcel began with the question of whether that entry price already baked in an aerospace and defense upswing or still left room for upside.
The bullish Narrative saw a Fair Value of US$65.33, based on air travel recovery and rising defense budgets feeding composite demand. This view assumed revenue growth of 10.0% a year and profit margins reaching 11.4%.
The bearish case pointed to a Fair Value of US$55, with supply chain delays and tariff uncertainty threatening aircraft production, reduced operating leverage, and slower financial recovery.
What The Results Changed For Hexcel
Hexcel reported Q2 2026 revenue of US$529.3 million and net income of US$49.3 million, with net margin at 9.3% versus 2.8% a year earlier. That margin step moved some way toward the bullish case that expected 11.4%, although it did not reach it, so the evidence cut both ways for the original growth and profitability assumptions.
The episode turned on one forecastable variable: profitability per dollar of sales. For a similar stock, track net margin against the original thesis and check whether higher sales are actually converting into the margin level that was written into the Fair Value story.
What Hexcel's Price Now Asks You To Believe
Hexcel now trades at US$90.22, and the selected Narrative frames this against a Fair Value that sits above the current price. The focus is not just on recovery but on what the existing footprint can earn if demand arrives roughly as outlined.
The Narrative argues that at today’s price you are effectively judging whether Hexcel can convert planned extra aerospace and defense revenue into the margin and cash generation profile management is aiming for.
"The main condition is that Hexcel turns the planned roughly $700 million of incremental commercial and defense revenue and its existing capacity into the higher margin profile management is targeting, while containing inflation and start up costs. The numbers now imply a positive view on Hexcel, with current margins, cash generation targets and external valuation work together suggesting the share price does not fully reflect the projected earnings and free cash flow profile."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Hexcel's Airframes
Hexcel points you toward aircraft demand. One step away, another industrial story tracks rising electricity use instead of flight hours.
AI facilities, electrified transport, and aging grids share a common need. They require dependable power equipment that can run hard and then keep running.
A different business concentrates on that task. It supplies turbines, grid hardware, and software that help heavy users keep electricity flowing.
Service contracts then stretch that relationship over long periods. As power systems work harder for longer, those ongoing agreements may matter more than the initial hardware sale.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 38% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com