


AEON Financial Service (TSE:8570) Could Be 10% Below Fair Value On Higher Half Year Earnings
Why AEON Financial Service’s latest earnings and dividend matter
AEON Financial Service (TSE:8570) has given investors fresh numbers to work with after reporting half year earnings to August 31, 2026, alongside an unchanged interim dividend announcement.
Net interest income came in at ¥98,552 million compared to ¥93,942 million a year earlier, while net income reached ¥10,052 million compared to ¥8,745 million in the prior half year.
Basic and diluted earnings per share from continuing operations were ¥46.56, against ¥40.51 a year ago, and the board confirmed a second quarter end dividend of ¥25 per share, matching last year, payable on November 16, 2026.
Recent trading tells a mixed story. The share price is up 2.1% over the past day and 2.6% over the last week, yet it is down 8.6% over 30 days and has fallen 13.6% year to date, while total shareholder return over one year, three years and five years is 8.0%, 36.4% and 22.9% respectively, suggesting long term holders have still been rewarded even as near term momentum has cooled around AEON Financial Service’s latest earnings and dividend update.
See how AEON Financial Service compares with other financial stocks with resilient balance sheets by reviewing it alongside our hand picked list of solid balance sheet and fundamentals (21 results).
AEON Financial Service shares now sit slightly above analyst targets yet trade at a discount to some fair value estimates. Is the market correctly pricing in the risks, or is it leaning too hard on caution as the valuation work starts?
Price-to-earnings of 14.4x: Is AEON Financial Service’s valuation justified?
AEON Financial Service is changing hands at ¥1,499, and on a P/E of 14.4x it screens more expensive than both its Asian Consumer Finance peers on 11.9x and the selected peer group on 10.5x, even though some models mark the shares at a discount to fair value.
The P/E ratio compares what you pay today to the earnings the business generates per share. For a diversified financial group that spans credit cards, loans, deposits and insurance distribution, this measure quickly tells you how heavily the market is weighing the current profit run rate against the risks around that income stream.
Here the picture is split. Forecasts point to earnings growth of 16.9% per year and revenue growth of 6.7% per year, with earnings up 24% over the past year and profit margins at 4.2% compared with 3.7% previously. This can help support a richer multiple. At the same time, return on equity is 6.3% and is expected to remain low at 6.4% in three years. The board and management bench are relatively new, the dividend track record is described as unstable, and analysts have a price target of ¥1,447.5 that sits below the current price, so the premium P/E carries clear execution expectations.
Stacking AEON Financial Service against its sector sharpens that contrast. The stock trades at a meaningfully higher P/E than both the Asian Consumer Finance industry and the peer average, yet it is described as good value versus an estimated fair P/E of 15.7x and is trading 9.8% below one fair value estimate and below an SWS DCF model future cash flow value of ¥1,662.49. The market is effectively paying up relative to peers but still allowing a gap to a fair ratio level that models suggest it could move towards if the profit and revenue forecasts are delivered.
Explore the SWS fair ratio for AEON Financial Service.
Result: Price-to-earnings of 14.4x (ABOUT RIGHT)
Still, the relatively low 6.3% return on equity and an unstable dividend record could quickly challenge the current AEON Financial Service premium if sentiment cools.
Find out about the key risks to this AEON Financial Service narrative.
Another view on AEON Financial Service’s value
The P/E work paints one picture, yet the SWS DCF model offers a different angle. On that cash flow view, AEON Financial Service at ¥1,499 sits below an estimated future cash flow value of ¥1,662.49, which frames today’s quote as cheaper on earnings but also on longer term cash generation. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
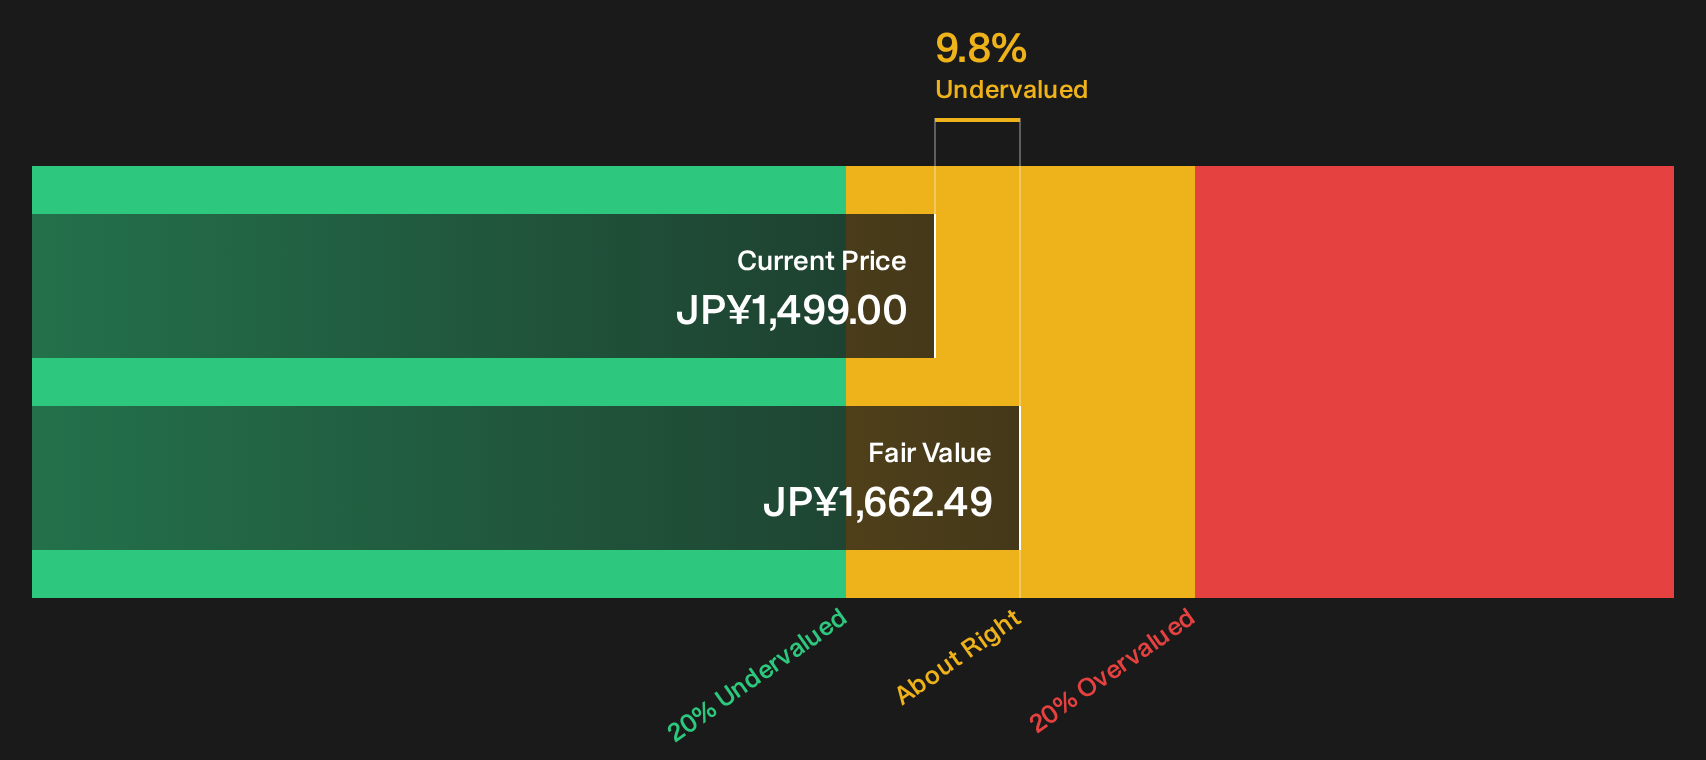
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AEON Financial Service for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or clear message? AEON Financial Service now has both risks on the radar and rewards that keep some investors optimistic, so review the numbers, stress test your own thesis, and then weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond AEON Financial Service?
AEON Financial Service gives useful clues, yet your next strong move probably comes from widening the watchlist with fresh, data backed ideas from the Simply Wall St screener.
- Target resilience first and hunt for steady balance sheets through the 22 resilient stocks with low risk scores.
- Chase value opportunities by scanning companies that combine quality fundamentals with appealing prices using the 14 high quality undervalued stocks.
- Prioritise reliable income streams by reviewing dividend focused candidates inside the 29 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com