


How Glance Checkout Expansion At PayPal Holdings (PYPL) Has Changed Its Investment Story
- Glance announced a U.S. agentic commerce integration with PayPal Holdings, embedding real-time product data and native PayPal checkout for tens of millions of consumers and giving merchants a single connection into AI powered shopping journeys.
- The partnership extends PayPal’s agentic commerce services as an on-ramp for retailers into AI driven storefronts. Its separate financial services deals, including a lending tie up with Amazon in Germany and Austria, highlight a push to deepen revenue sources beyond traditional checkout.
- We will now look at how PayPal Holdings' investment narrative could shift as agentic commerce integration becomes a larger transaction channel.
PayPal Holdings Investment Narrative Recap
To own PayPal Holdings, you need to believe the business can shift more of its transaction margin toward areas like financial services, Venmo and Braintree while keeping branded checkout resilient. The Glance agentic commerce tie up speaks directly to that idea, because it plugs PayPal into AI driven shopping flows that could deepen engagement without adding heavy onboarding friction.
Right now, the key near term swing factor is whether execution on modernization and product rollouts supports earnings, given consensus expectations for slightly declining profit over the next few years. The biggest risk remains margin pressure if volume keeps tilting toward lower take rate products faster than the US$1.5b cost program improves efficiency.
The Glance partnership connects neatly with management’s push into new payment flows such as AI agent checkout and Buy Now Pay Later. By embedding real time product data and native PayPal checkout inside Glance, the company is testing whether AI centric experiences can carry full funnel commerce, from search to payment, on infrastructure PayPal already operates at scale.
That matters for the broader catalyst that financial services and newer flows are already close to 20% of transaction margin. If integrations such as Glance and the Amazon lending arrangement in Europe execute cleanly, they can support that mix shift while also stress testing PayPal’s cost and technology overhaul. The execution risk is that complexity from many new channels slows product delivery or blunts the expected margin lift.
PayPal Holdings' current analyst narrative points to revenues of US$38.7b and earnings of US$4.7b by 2029, based on forecast revenue growth of 4.3% per year and consensus earnings expectations for that same year. This implies a decline in earnings of US$0.2b from US$4.9b today rather than an increase.
Uncover why PayPal Holdings' fair value indicates that PayPal Holdings is in line with its current price.
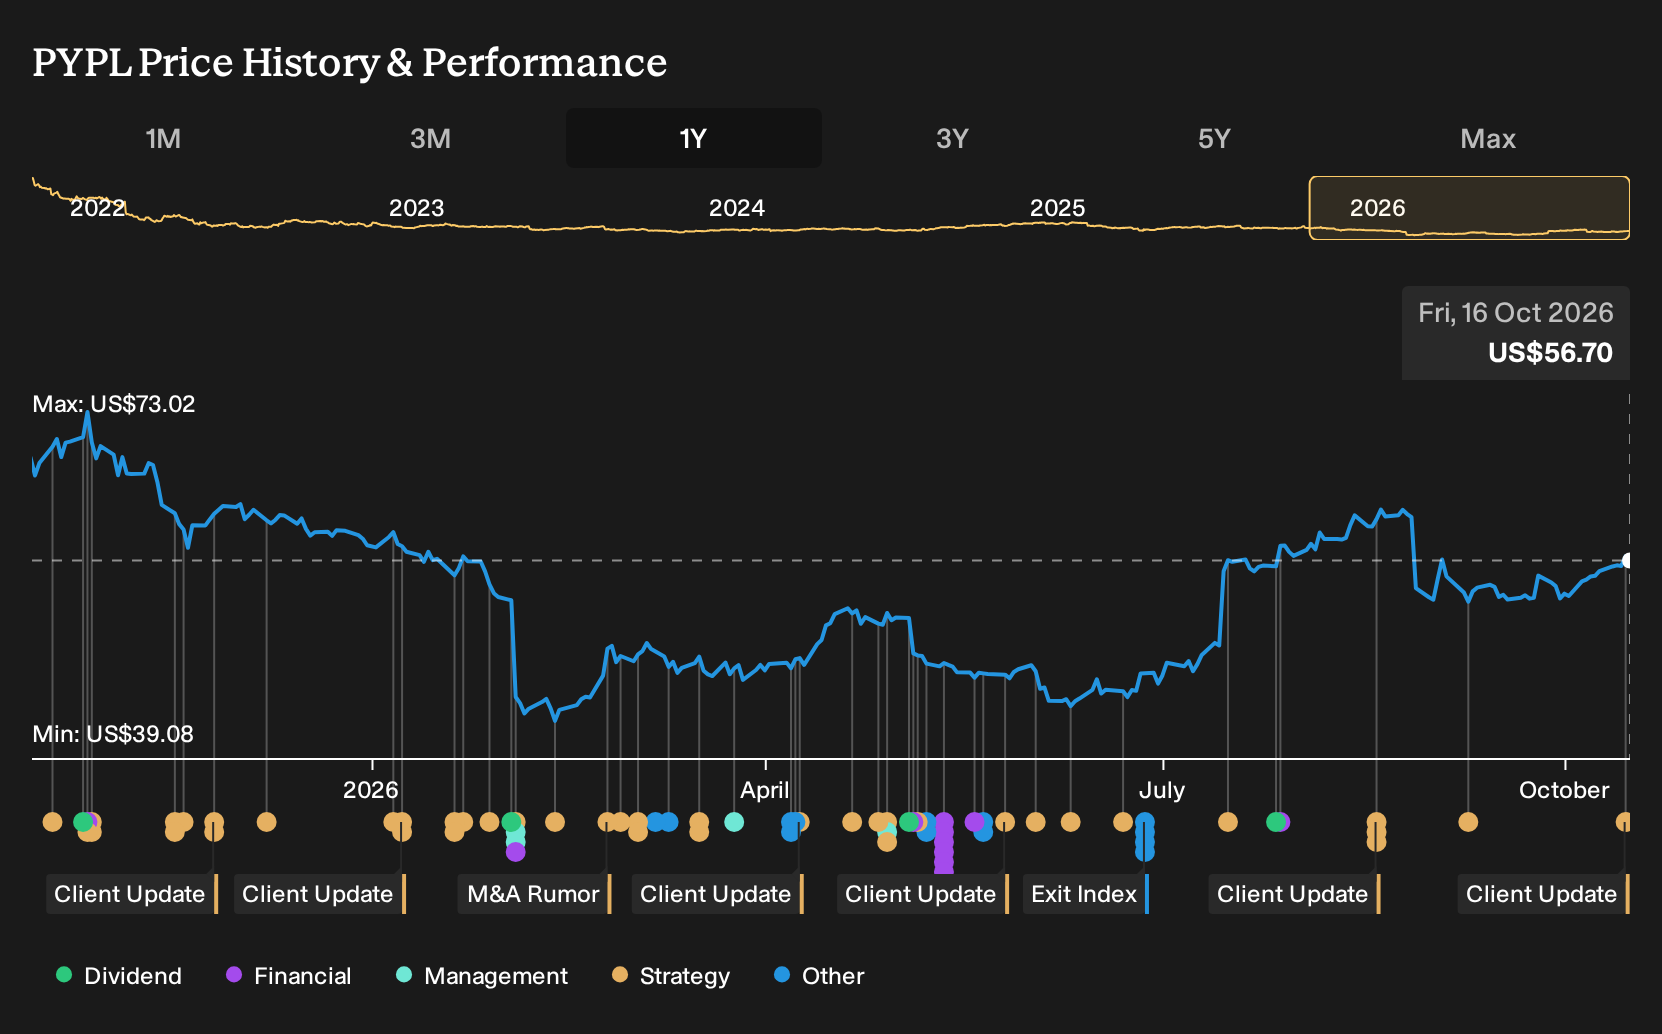
Exploring Other Perspectives
Some of the most optimistic analysts focus on earnings power rather than agentic commerce risk. Before this Glance news, the bullish camp was modelling PayPal Holdings at US$41.5b of revenue and US$6.3b of earnings by 2029, far above consensus. You can treat this new AI checkout channel as a fresh input when weighing those very different views.
Explore 26 other PayPal Holdings fair value estimates, including one that suggests as much as 123% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your PayPal Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate PayPal Holdings' overall financial health at a glance.
Looking for more PayPal Holdings sized investment ideas?
If the PayPal Holdings story has sharpened your thinking about where you want capital to work, you can cast the net wider with a few focused screeners that surface stocks by quality, resilience and upside potential rather than noise.
- If you want potential mispricing in your favour, scan a 33 high quality undervalued stocks that combines solid fundamentals with a price that may not fully reflect its financial profile.
- If capital protection sits near the top of your priorities, filter for 32 resilient stocks with low risk scores that score well on financial strength and business stability.
- If you prefer sturdier balance sheets backing the story, start with a list of solid balance sheet and fundamentals (25 results) that already shows robust finances before any growth thesis even enters the picture.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com