


Is Falling Traveler Demand Altering The Investment Case For AMN Healthcare Services Stock (AMN)?
- AMN Healthcare Services has faced softer demand, with travelers on assignment declining over the past two years and earnings per share shrinking 7.6% annually over five years.
- Diminishing returns on capital suggest earlier profit pools are harder to replicate, which raises questions about how effectively AMN Healthcare Services is deploying its resources.
- We will now see how AMN Healthcare Services' weakening traveler demand reshapes the existing investment narrative that was built on persistent staffing shortages.
Balance the softer outlook at AMN Healthcare Services by scanning a hand picked list of solid balance sheet and fundamentals (25 results) that investors use when they want resilient fundamentals to anchor their portfolios.
AMN Healthcare Services Investment Narrative Recap
For AMN Healthcare Services to fit in your portfolio, you need to believe the healthcare staffing cycle can stabilise enough for its large clinician network and tech platforms to stay meaningfully utilised. Softer traveler demand and shrinking EPS now put more weight on execution in non nurse segments and on tighter cost control across the group.
The most important short term swing factor is how quickly traveler volumes and bill rates find a floor. The biggest risk is that hospital customers lean harder into permanent hiring and internal float pools, which could deepen volume pressure and make the already weakening returns on capital harder to reverse.
There have been no fresh company announcements tied directly to this latest drop in traveler demand. That absence keeps attention squarely on the existing playbook, which relies on AMN Healthcare Services' diversification across Nurse and Allied Solutions, Physician and Leadership Solutions, and Technology and Workforce Solutions.
In this context, the previously highlighted trends matter more. Pressure in language services pricing, softer VMS revenue and slower recovery in physician and leadership staffing all tighten the margin for error because they limit how much other segments can offset weaker traveler assignments if demand softness lingers.
AMN Healthcare Services is projected to reach revenue of US$2.4b and earnings of US$2.6m by 2029, based on analyst assumptions of revenue declining 11.6% per year and earnings falling by about US$102.3m from US$104.9m today. This represents a sharp reset in the profit base rather than a small tweak at the margin.
Uncover why AMN Healthcare Services' fair value indicates an 11% potential downside to its current price that leaves little room for error.
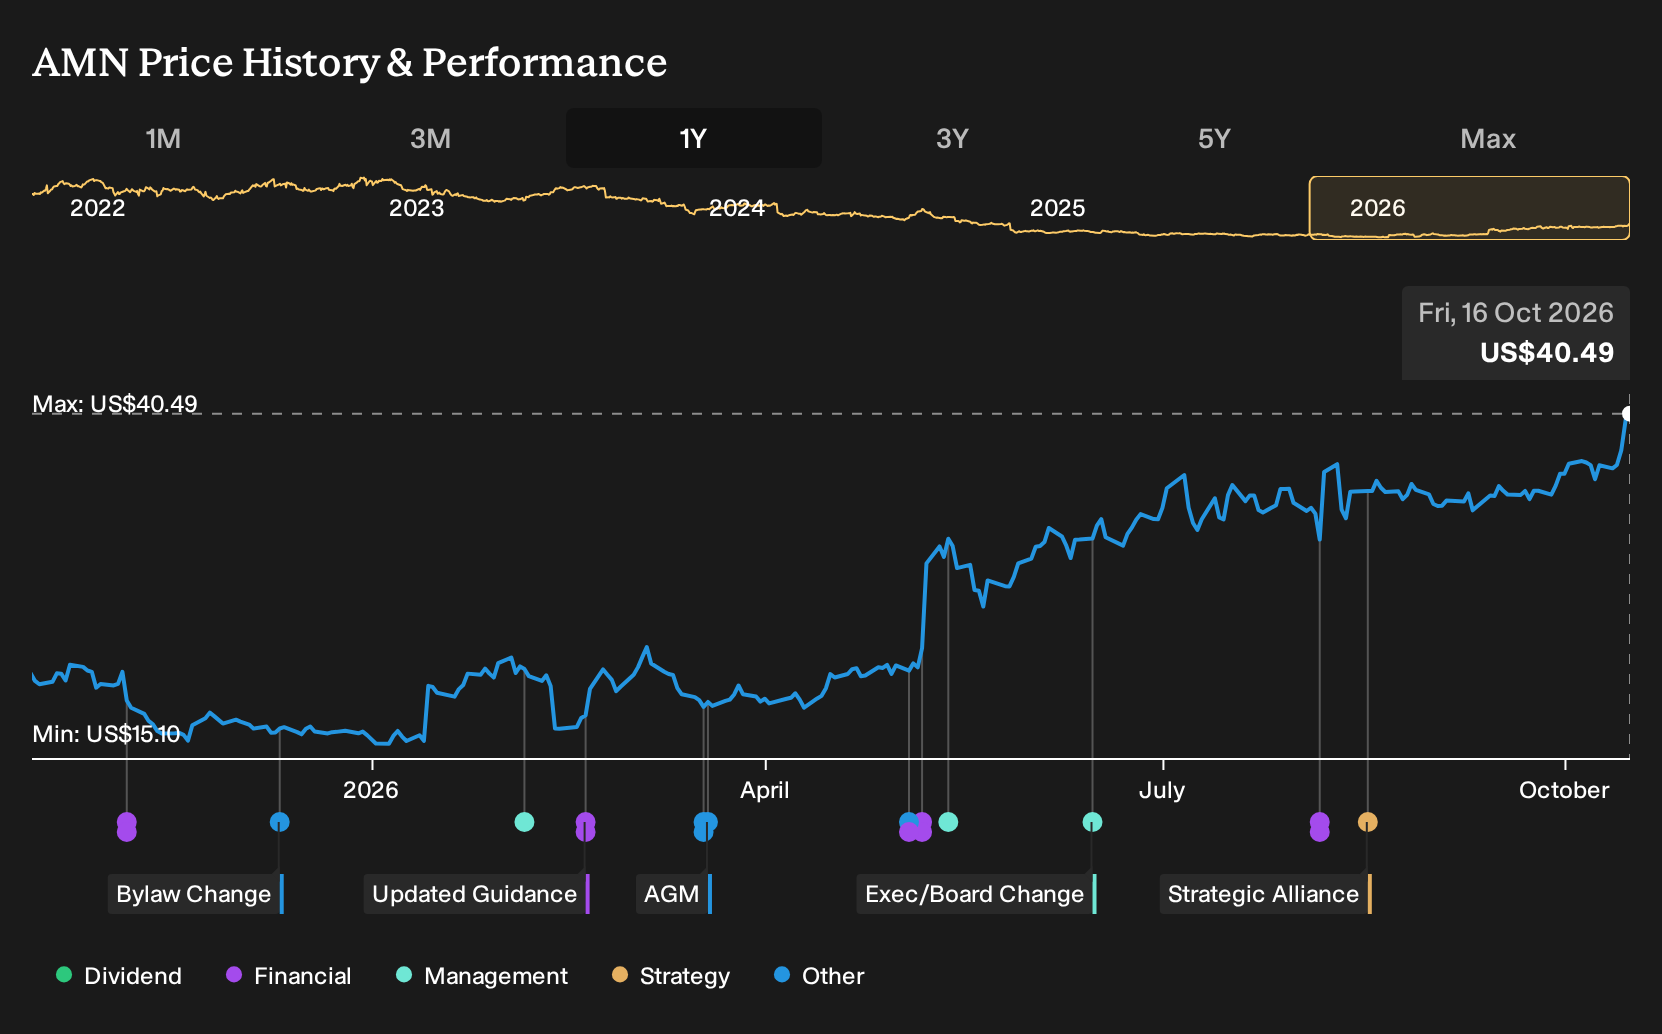
Exploring Other Perspectives
One alternate view on AMN Healthcare Services focuses less on traveler softness and more on the risk that technology and physician segments stay under pressure. The most pessimistic analysts were already modeling revenue falling about 10.8% a year and 2029 earnings near US$153.0m. Those forecasts came before this news, so you should expect opinions to shift and explore several possible updates yourself.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AMN Healthcare Services research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AMN Healthcare Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMN Healthcare Services' overall financial health at a glance.
Looking For More Ideas Beyond AMN Healthcare Services?
If the current setup around AMN Healthcare Services feels finely balanced, it can help to widen the lens and compare it with other opportunities that match different risk and income profiles. The Simply Wall St Screener lets you do exactly that by filtering for fundamentals that line up with how you like to invest.
- If you want potential mispricing with quality fundamentals, scan a carefully filtered group of 33 high quality undervalued stocks that already pass strict balance sheet and cash flow tests.
- If resilience matters more than excitement right now, focus on a curated pool of 32 resilient stocks with low risk scores that aim to keep volatility and financial red flags in check.
- If income is a key part of your plan, start with a focused set of 8 dividend fortresses that offer higher yields while still meeting fundamental quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com