


How Earnings Beat Will Impact Yelp Stock (YELP)
- Yelp has recently outperformed earnings expectations for two consecutive quarters, and analysts now assign the company a positive Earnings ESP of 12.50% alongside a Zacks Rank #3 (Hold) ahead of its next report.
- The consistent pattern of earnings surprises, paired with more optimistic estimate revisions, suggests Yelp’s underlying cost control and monetization efforts are drawing closer investor scrutiny than usual.
- We will now look at how Yelp’s investment narrative could be influenced by these repeated earnings beats and the higher Earnings ESP.
Scan for other potential earnings beaters with similar momentum to Yelp by reviewing our hand picked 20 high quality undiscovered gems.
Yelp Investment Narrative Recap
To own Yelp, you need to believe the platform can offset a sluggish core ad business with higher margin AI tools and data licensing. The recent pattern of earnings beats suggests expense control and monetization are holding up in the near term. That supports the key short term catalyst, execution on AI products and subscriptions, more than it changes the story.
The biggest immediate risk still sits in the ad categories that are under pressure. Services ads are flat and Restaurant, Retail and Other ad revenue is down 10%. If that weakness drags on while Yelp continues to spend on AI, Hatch and marketing, profitability could come under strain.
Without fresh announcements tied directly to this earnings setup, the most relevant thread is Yelp's push into AI driven features such as Yelp Assistant and subscription tools like Yelp Host and Hatch. These products are intended to deepen engagement and add more predictable fee based income alongside advertising.
For you as an investor, the link to the current earnings momentum is straightforward. Better cost control and surprise upside on profits give management more time to keep rolling out AI search APIs, content licensing deals and subscription tools. The key question is whether these newer lines can ramp fast enough if core ad demand stays soft and legal or regulatory costs increase.
What Current Forecasts Assume For Yelp
Yelp's narrative projects US$1.6b revenue and US$157.9m earnings by 2029. This implies 2.1% yearly revenue growth and an earnings increase of about US$31m from the current US$126.5m level.
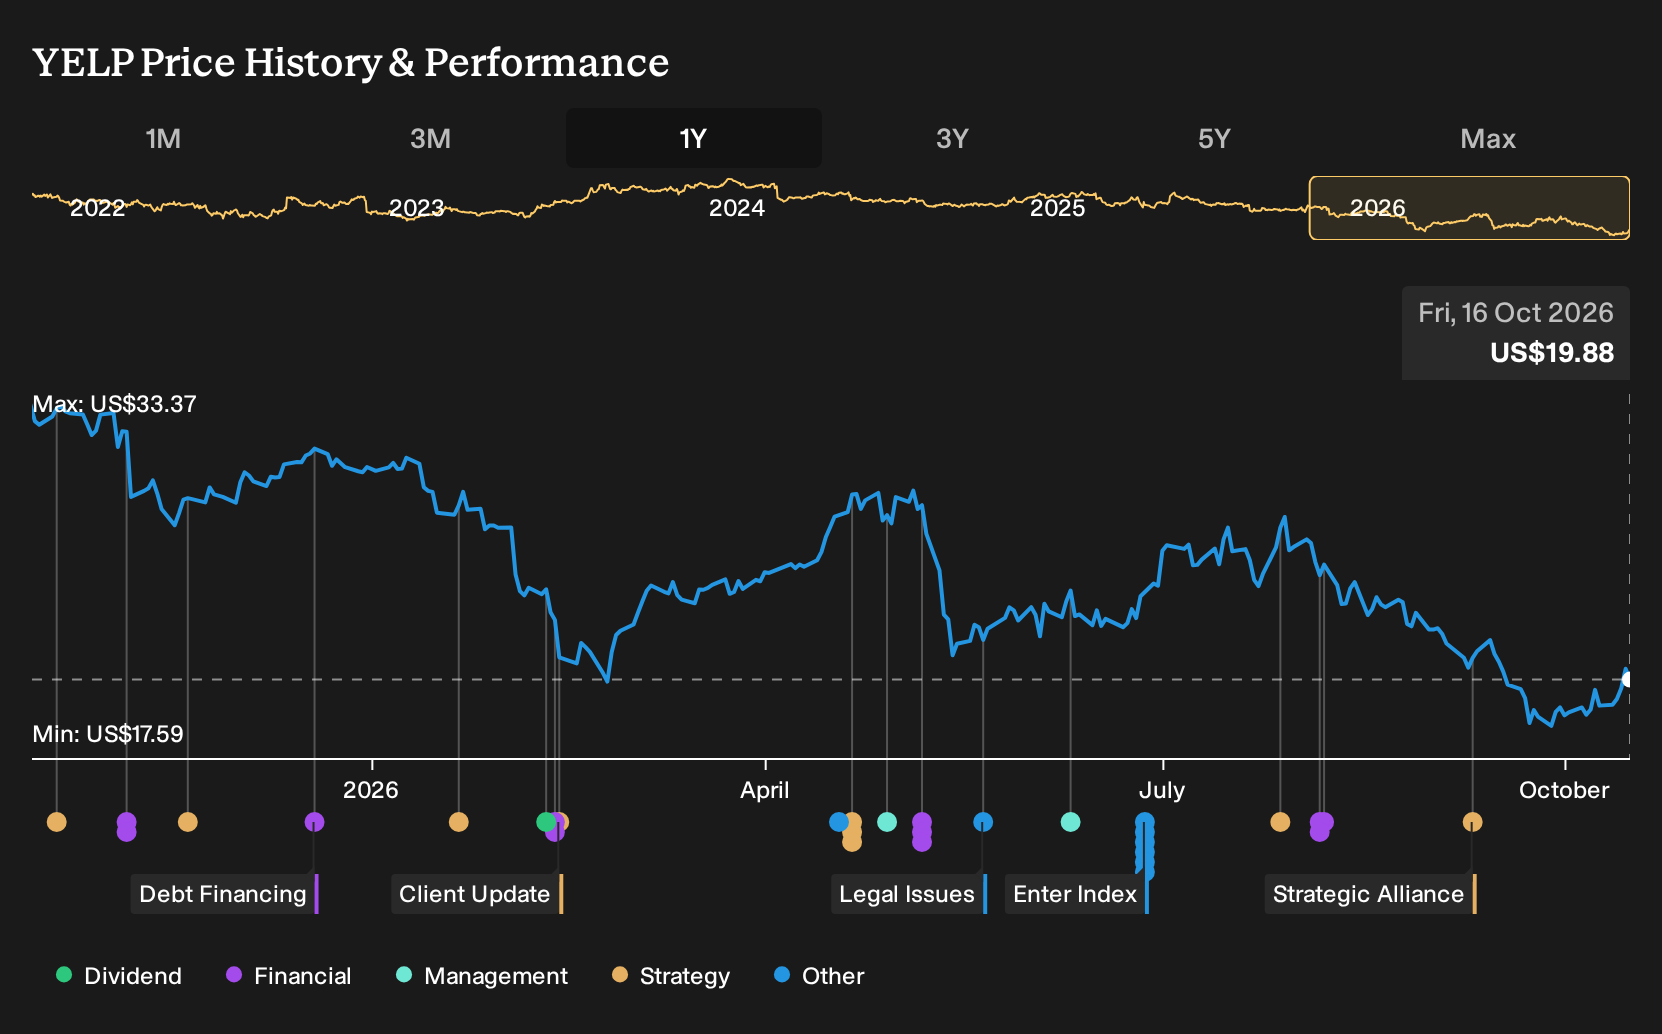
Uncover why Yelp's fair value indicates a 26% potential upside to its current price, which could close quicker than many investors expect.
Exploring Other Perspectives
Another angle on Yelp focuses on how fast Other revenue might scale. The most optimistic analysts were already penciling in US$1.6b of revenue and US$171.9m of earnings by 2029 before this earnings ESP story hit the tape. You can treat this upbeat view as one of several future paths to compare.
Explore 4 other Yelp fair value estimates, including one that suggests potential upside of as much as 229% from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Yelp research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Yelp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yelp's overall financial health at a glance.
Looking For More Yelp-Sized Investment Ideas?
If the setup around Yelp has sharpened your appetite for opportunities with clear data behind them, it can help to zoom out and run the same kind of structured check on a wider watchlist using the Simply Wall St Screener.
- For investors who want potential mispricing backed by fundamentals, take a look at 33 high quality undervalued stocks that currently align with stronger quality metrics and discounted valuations.
- If stability and capital strength matter most to you, filter for companies on the list of solid balance sheet and fundamentals (25 results) and focus on those with cleaner debt profiles and resilient cash positions.
- Income focused readers can narrow in on payouts by scanning the 8 dividend fortresses and concentrating on stocks that pair higher yields with more robust balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com