


How Investors May Respond To Matson (MATX) First LNG Ready Ship
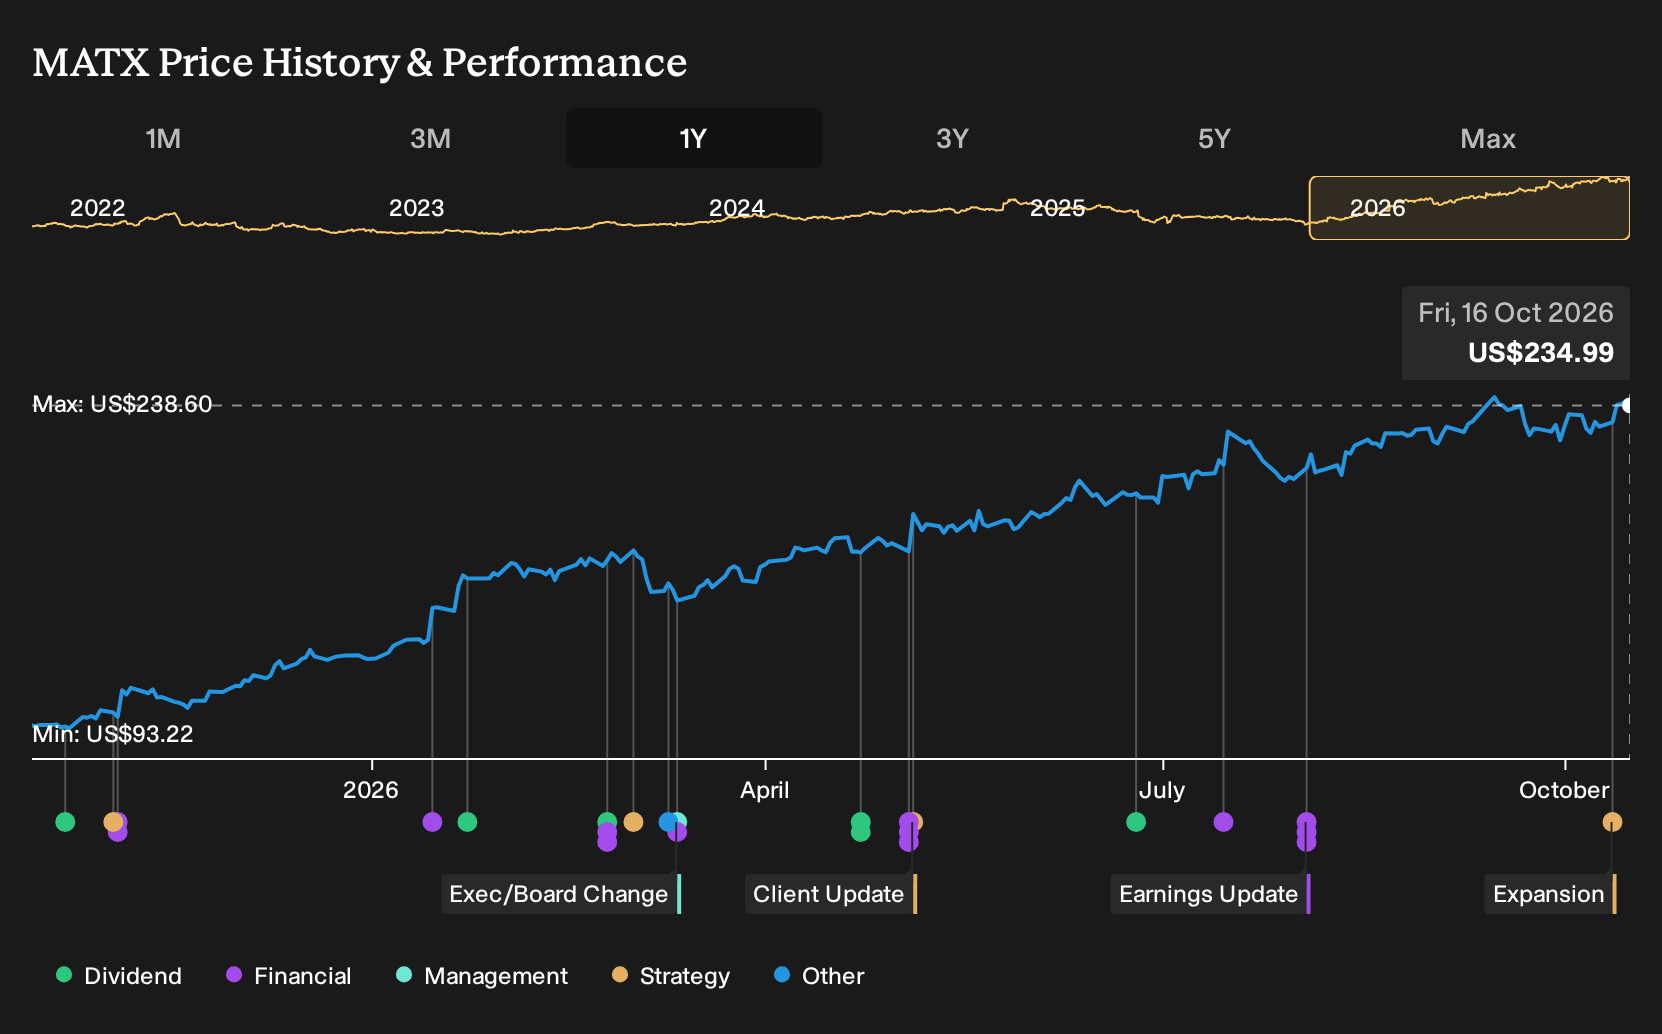
- Matson has christened Makua, the first of three new Jones Act compliant, LNG ready Aloha Class containerships being built at Hanwha Philly Shipyard for its China Long Beach Express and Hawaii services, as part of an approximately US$1b fleet investment.
- The trio of 3,600 TEU, high speed, dual fuel ships is set to replace older vessels, which could reshape Matson’s cost base, service reliability and emissions profile on some of its most important Pacific routes.
- We will look at how Matson’s investment narrative is affected by committing US$1b to LNG ready containerships for core Pacific trades.
Matson Investment Narrative Recap
To own Matson, you need to believe its premium Pacific routes, protected domestic lanes and logistics arm can justify steady reinvestment into the fleet while keeping returns on capital attractive. The christening of Makua fits that story. It makes the heavy US$1b capex program more tangible, but does not change the near term demand or pricing setup on its own.
The near term swing factor still sits in China and Southeast Asia freight volumes and pricing, because small changes there have already moved consolidated operating income. The biggest risk remains that higher capital intensity and LNG focused spend compress free cash flow and margins if trade volumes soften or customers do not consistently fill these higher cost ships.
The LNG ready Aloha Class delivery timeline matters most when set against Matson’s broader fleet modernization plans already flagged to investors. Management has indicated around US$1b is committed to these vessels and related equipment, largely covered by cash and its Capital Construction Fund, which helps limit reliance on extra borrowing for this build cycle.
For you, that makes execution on vessel delivery, entry into the Hawaii and China Long Beach Express services and the retirement of older ships a clear catalyst to watch. Each handover from 2027 to 2028 could start to influence unit fuel costs, schedule reliability and maintenance spend. At the same time, the capex program also keeps the risk of thinner free cash flow margins firmly on the table.
Matson's current analyst narrative points to about US$3.9b in revenue and US$495.1m in earnings by 2029, based on an assumed 4.4% yearly revenue growth rate. This implies an earnings increase of roughly US$31.3m from US$463.8m today to the 2029 consensus figure.
Uncover how Matson's fair value indicates an 11% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate view focuses on valuation risk. The most cautious Matson analysts already saw the stock as fairly priced, even while pencilling in around US$4.0b of 2029 revenue and US$470.4m of earnings before this ship order hit headlines. That sets a more pessimistic tone and leaves plenty of room for forecasts to shift after the Makua news.
Explore 6 other Matson fair value estimates, including one that suggests as much as 53% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Matson research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Matson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Matson's overall financial health at a glance.
Looking for more Matson sized investment ideas?
If the Matson story has you thinking about where else capital could work hard for you, the Simply Wall St Screener can help you sort through the wider market quickly and with clear fundamentals front and center.
- If you want potential value with quality backing it up, start with a curated set of 33 high quality undervalued stocks that pair solid balance sheets with strong cash generation.
- For investors who care about income resilience, focus on dependable payers in the 8 dividend fortresses that combine higher yields with underlying business strength.
- When capital preservation ranks high on your list, filter for stability first using a 32 resilient stocks with low risk scores that screens on financial health and risk scores before anything else.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com