


Missed Isuzu Motors' Rally? Here's What Holders Saw
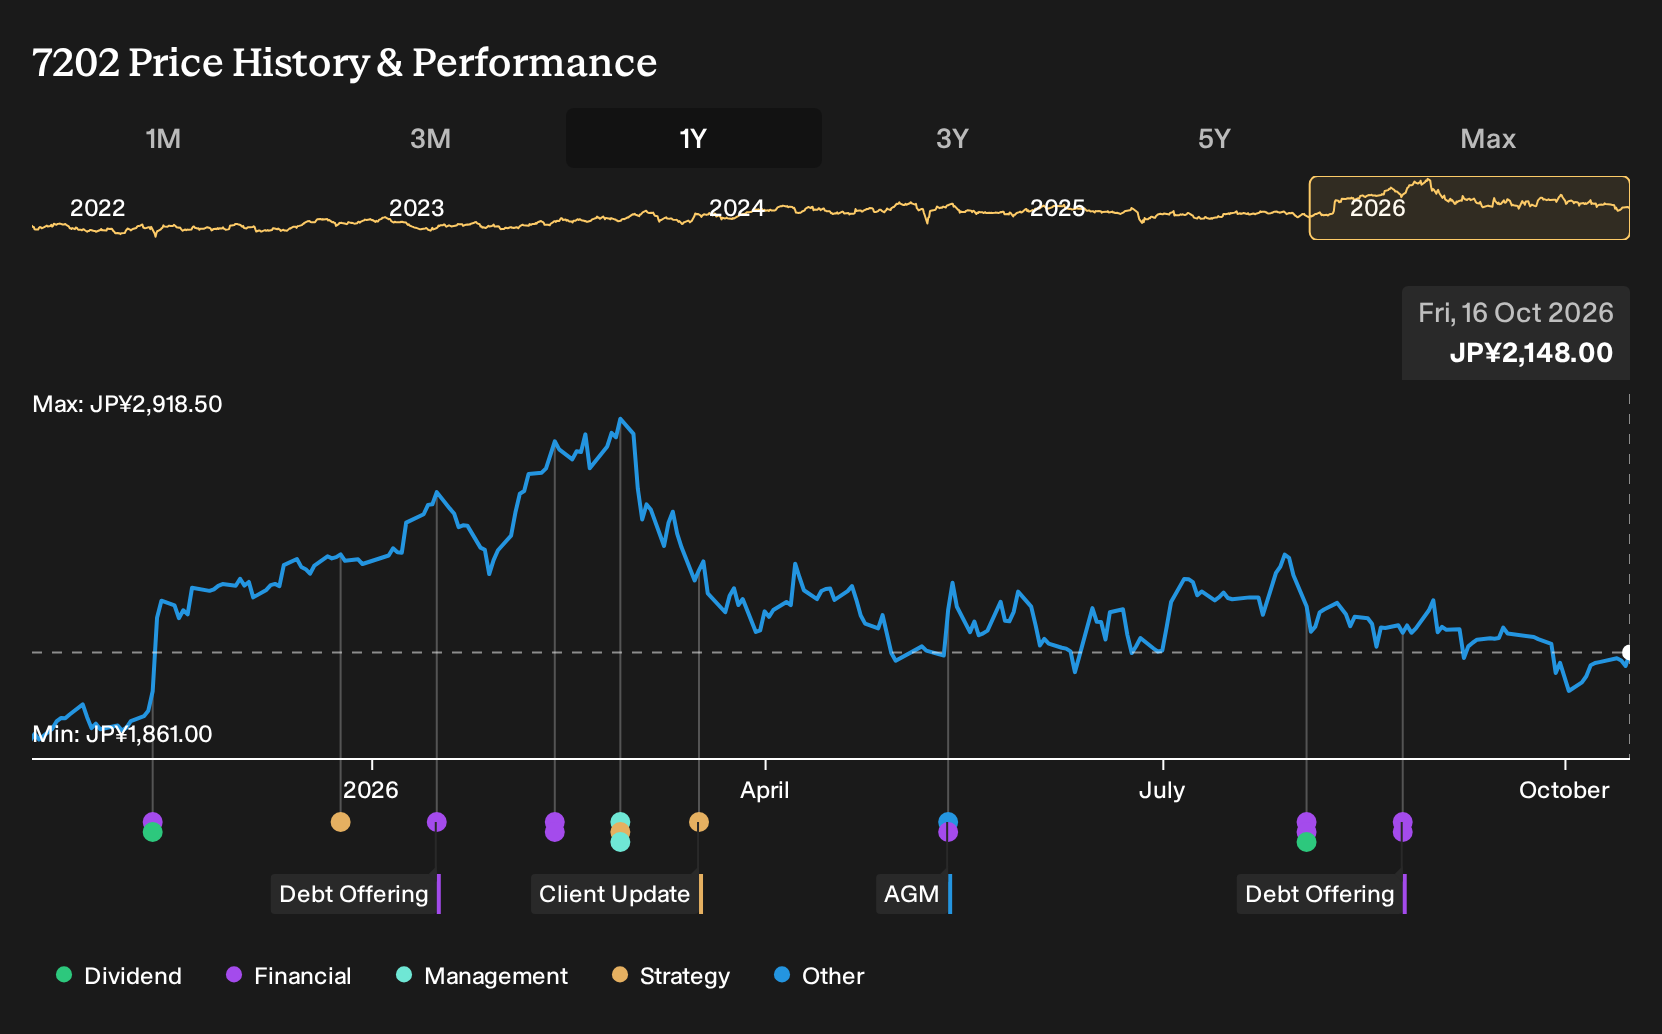
If you had been weighing Isuzu Motors in October 2025, you were staring at a split screen. One side framed a push into commercial vehicle sales, IFRS reporting and buybacks that some thought could broaden its appeal. The other highlighted heavy diesel exposure and rising competitive pressure. For Isuzu Motors shareholders, the return over the past year was 20.4%, including dividends. If you were making that call then, how much weight would you have put on Thailand expansion and a UD Trucks merger review still to come?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Isuzu Motors has already moved. Pinpoint other ways to investigate the theme among 92 robotics and automation stocks.
The Two Stories Investors Had To Hold In Their Heads
The shares cost ¥1,876 at the start of the period, and anyone looking at Isuzu Motors had to choose which storyline felt more reasonable.
On the bullish side, one narrative put Fair Value at ¥2,164 and leaned on 5.4% assumed annual revenue growth plus a 4.8% profit margin in three years, supported by CV sales expansion and IFRS adoption.
The bearish view pointed to a Fair Value of ¥1,600, arguing that heavy diesel dependence and slower electrification could leave Isuzu Motors exposed to tighter emissions rules and fiercer competition.
What The Results Changed For Isuzu Motors
Thailand approved a US$468m plan for Isuzu Motors to automate plants, upgrade pickup technology to Euro 6 standards and increase clean energy use. This supported the optimistic case built around commercial vehicle expansion and IFRS-era efficiency. At the same time, Q1 2027 figures showed revenue at ¥832,519m and net income at ¥50,938m, with net margin at 6.1%. The evidence cut both ways on how durable that profitability might be.
The decision in 2025 really hinged on whether operational upgrades would show up in margins. When you assess another manufacturer, track whether promised capacity, technology or integration projects appear later in reported revenue, absolute profit and net margin rather than remaining only in presentations.
What Today's Isuzu Motors Price Already Assumes
Today Isuzu Motors trades at ¥2,148 after a 20.4% gain over the past year. The selected Narrative places its Fair Value below that market level, framing the gap around how reliably cash generation and execution can support this higher entry point.
The Narrative focuses less on powertrain risk and more on supply chain friction, cost pressure and heavy Thai investment. Anyone paying today’s price is effectively assuming margins and cash flow stay resilient. How does that square with the source’s concern over logistics disruptions and working capital strain?
"The current valuation, which treats Isuzu Motors as fairly valued to bullish, implies that the share price already reflects resilient margins despite volume volatility, successful delivery on planned operating income and meaningful long-term benefits from manufacturing upgrades and possible consolidation."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Isuzu Motors
Isuzu Motors puts the spotlight on trucks and diesel efficiency. You could also explore where transport meets physical AI innovation.
One specialist is reusing its own chips and software across electric cars, self driving taxis and humanoid machines. The same technology stack supports very different tasks.
Your question moves from engines and factories to code, models and robotics hardware. The unresolved issue is whether heavy development spending can support higher margin services.
If that shift toward software, autonomy and subscription style income succeeds, the role of a vehicle maker could eventually look very different from Isuzu Motors today.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 100% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com