


USA Compression Partners (USAC) Could Be 15% Undervalued On Q3 Distribution News
Dividend affirmation puts income in focus
USA Compression Partners (USAC) has reaffirmed its income pitch, declaring a third quarter 2026 cash distribution of $0.525 per common unit, or $2.10 on an annualized basis.
The payout goes to unitholders of record at the close on October 26, 2026, with cash scheduled to hit accounts on November 6. Income focused investors now turn to the upcoming earnings release and conference call for added context.
USA Compression Partners units now trade at $25.42, with a 1-year total shareholder return of 17.99% and a 5-year total shareholder return of 138.13%. However, recent 30 day and 90 day share price returns have eased, suggesting that momentum has cooled despite a positive income story.
Spot income focused opportunities with similar profiles to USA Compression Partners by scanning our hand picked 8 dividend fortresses before the next round of payout headlines lands.USA Compression Partners now offers a steady distribution but sits off recent highs after a softer 30 and 90 day run. Does that pullback present a fair entry today, or does it argue for patience and a better mark later?
Most Popular Narrative: 15% Undervalued
USA Compression Partners is priced at $25.42 against a narrative fair value of $30. This frames a modest valuation gap that hinges on demand visibility and execution on recent investments.
Ongoing tightness in large horsepower compression, reflected in engine lead times that have extended to about 200 weeks and customers contracting capacity several years ahead, gives USA Compression Partners multi year visibility on deployments and underpins revenue and cash flow. Integration of the J-W acquisition, which added roughly 850,000 active horsepower plus manufacturing and aftermarket capabilities, gives USA Compression Partners additional scale and vertical integration to support fleet growth, manage equipment costs, and influence net margins.
See why 6 investors see USA Compression Partners as 15% undervalued.
Result: Fair Value of $30 (UNDERVALUED)
Still, USA Compression Partners faces two pressure points that could flip this script if they worsen: higher leverage tied to its payout policy and ongoing cost inflation, including lube oil and labor.
Find out about the key risks to this USA Compression Partners narrative.
Another View on USA Compression Partners Valuation
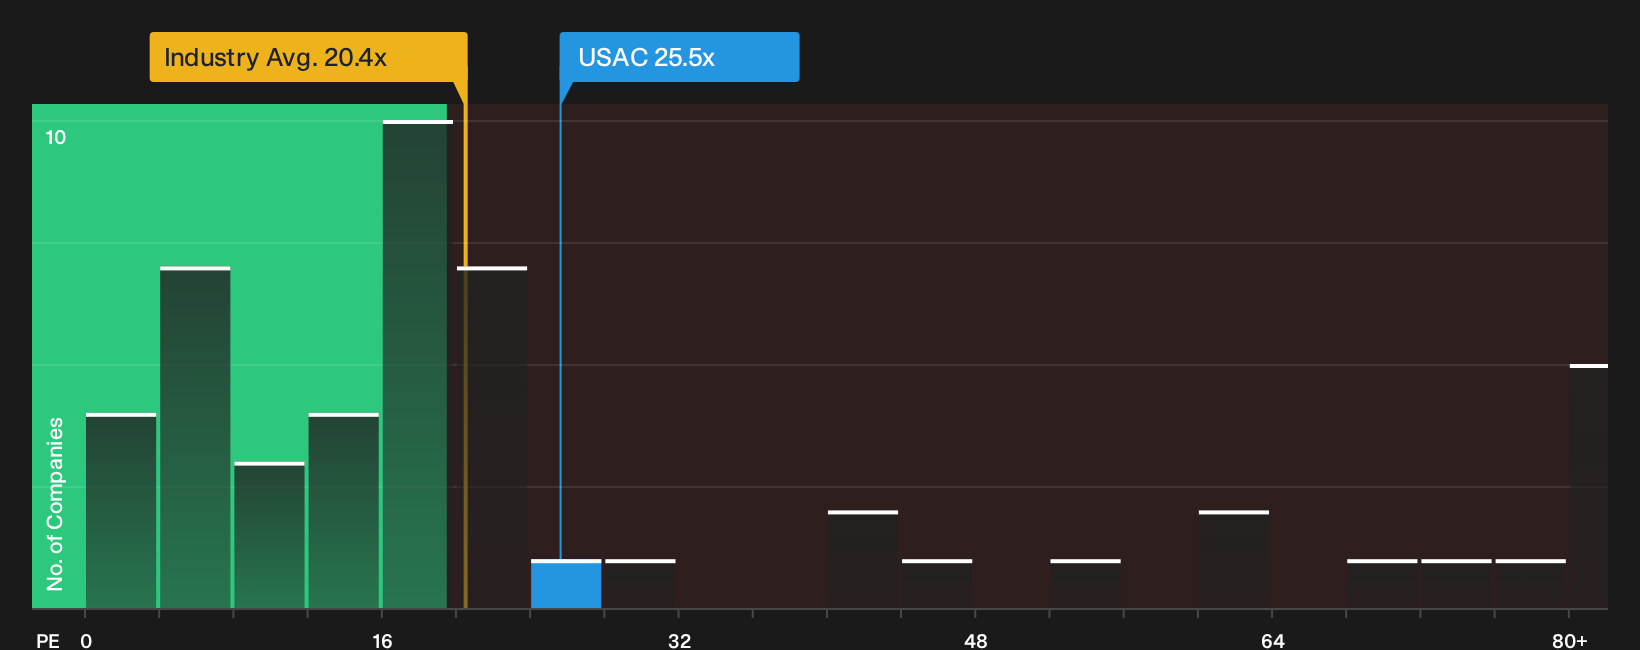
Multiples tell a different story. USA Compression Partners trades on a P/E of 25.5x, while the US Energy Services group sits at 23.1x and the fair ratio is 19.5x. That premium hints at less margin for error. Are you comfortable paying up for this earnings profile?
To see how that price stacks up against the underlying numbers, look into our valuation breakdown, then weigh how much multiple risk you want to carry at this stage.See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how USA Compression Partners compares to sector peers on earnings, review the latest ratio snapshot.
Next Steps
Mixed signals on USA Compression Partners valuation and income profile can feel messy, so move quickly, test the data yourself, and pressure test both sides of the story. A good place to start is with a clear rundown of the 3 key rewards and 3 important warning signs.
Looking for more USA Compression Partners style ideas?
Do not stop your research at USA Compression Partners. Broaden your watchlist now, or you risk missing income, value, and balance sheet ideas that could shape the next phase of your portfolio.
- Target value first and look for companies that combine strong fundamentals with attractive pricing through the 20 high quality undiscovered gems.
- Prioritise resilience and focus on businesses with sturdier finances by scanning the list of solid balance sheet and fundamentals (25 results).
- Dial down risk and filter for steadier performers using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com