


ALS (ASX:ALQ) Faces A Fresh Valuation Test On Margin And Cash Flow Debate
Debate around ALS (ASX:ALQ) has intensified as fresh commentary weighs optimism about long term free cash flow and growth prospects against concerns over margin pressure from rising technology and cyber security spending.
ALS shares closed at A$20.25 after a 1-day share price return of 3.47%, although the 90-day share price return is down 7.79% and the year to date share price return is down 8.20%. However, the 3-year total shareholder return of 97.05% keeps the longer term story firmly in positive territory and suggests sentiment has cooled recently rather than reversed outright.
Scan beyond ALS and see how other high quality cash generative businesses with solid balance sheets are priced right now with our hand picked list of solid balance sheet and fundamentals (12 results).
ALS now trades at a clear discount to both analyst targets and some intrinsic value estimates after a sharp multi year run. Is that caution around future cash flows and margins misplaced, or exactly the point?
Most Popular Narrative: 16% Undervalued
ALS is framed as undervalued by the most followed narrative, with a fair value of A$24.12 against the last close at A$20.25. The gap rests on whether cash flows and margins hold up against execution and cyber risk.
The continued build out of ALS’s global environmental platform, now 35% of group revenue with PFAS work accounting for 6% of that segment, is positioned to benefit from tighter environmental regulations and can support revenue and margins.
See why 15 investors see ALS as 16% undervalued.
Result: Fair Value of A$24.12 (UNDERVALUED)
Still, the narrative around ALS could be tested if the recent cyber incident leads to lasting client or cost fallout, or if Environmental integrations underdeliver again.
Find out about the key risks to this ALS narrative.
Another View: ALS On Earnings Multiples
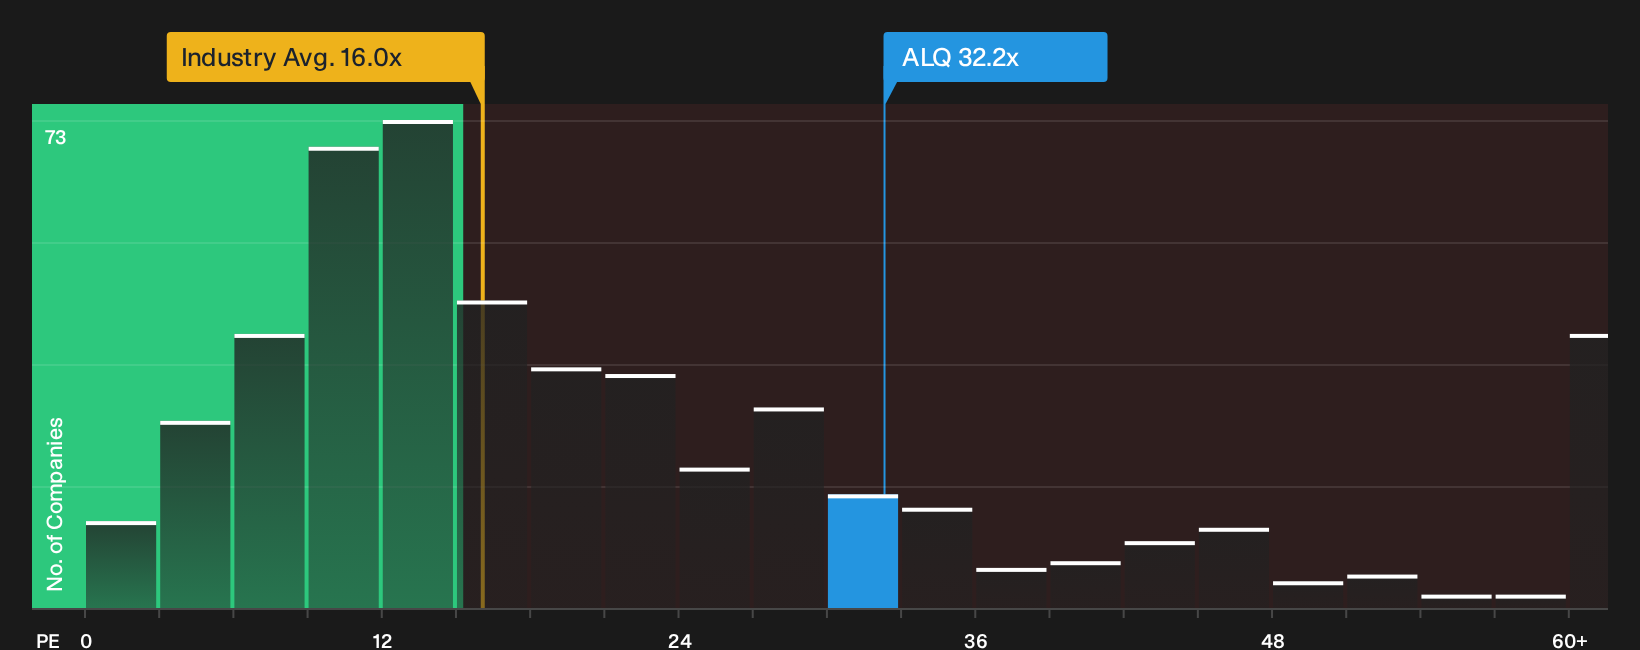
On earnings, ALS looks anything but cheap. The shares trade on a P/E of 32.2x, compared with 28x for peers and 16.2x for the wider Global Professional Services industry. Even against a fair ratio of 25.8x, the current multiple sits high. Is that premium cushioning risk or adding it?
For a closer look at how the current pricing stacks up against those earnings benchmarks, including where the fair ratio suggests the P/E could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ALS can either paralyze decisions or sharpen them, so move quickly, pull up the full picture yourself and weigh the 3 key rewards and 2 important warning signs.
Looking for more ALS investment ideas?
If ALS has sharpened your thinking, do not stop here. Broaden your watchlist now so you can spot opportunities before the crowd does.
- Target potential mispricings by scanning companies that combine quality metrics with attractive entry points through the 4 high quality undervalued stocks.
- Strengthen your income stream by checking out businesses that aim to deliver robust payouts inside the 4 dividend fortresses.
- Sleep easier at night by focusing on resilient businesses with steadier risk profiles using the 6 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com