


Learn Why The Bull Case For Global Payments Stock Could Change Following Coverage Reinstatement
- Bank of America recently reinstated coverage on Global Payments after its asset swaps, highlighting a clearer focus on distinct end markets and core payment technology services.
- The renewed attention underscores how Global Payments’ tighter business scope and cleaner merchant centric model could influence execution on integration and synergy plans.
- Next, the focus turns to how Global Payments’ sharpened end market focus underpins its broader investment narrative and execution track record.
Scan how Global Payments fits into the broader payments reset and evaluate other processors that screens flag as potential breakouts by reviewing 33 high quality undervalued stocks in the same space.
Global Payments Investment Narrative Recap
To own Global Payments, you need to be comfortable with a focused merchant centric model where the real swing factors are execution on Worldpay integration, scaling AI tools and keeping compliance costs in check. The recent Bank of America coverage restart shines a light on this simplified setup but does not change the near term work required inside the business.
Right now, the key short term catalyst is delivering on Worldpay cost and revenue synergy milestones while extending Genius and software led bundles across more merchants. The biggest risk remains integration and regulatory friction that could pressure already compressed net margins and make interest costs more uncomfortable, given earnings coverage signals.
The most relevant development around this news is the clearer split of end markets after Global Payments’ asset swaps. With issuer and payroll solutions carved away, investors can focus more directly on merchant acquiring, payment technology and associated software, which ties cleanly into themes Bank of America is highlighting across the group.
This sharper perimeter sets a firmer backdrop for monitoring catalysts such as Genius rollout, AI decisioning tools like Revenue Boost and FraudSight, and the multi year Worldpay synergy plan that targets US$600m of cost and US$200m of revenue benefits by the end of 2028. Execution against those markers, alongside travel related headwinds and regulatory costs, is likely to shape how the story evolves from here.
Global Payments’ current analyst playbook points to US$13.9b in revenue and US$2.1b in earnings by 2029, based on a projected 10.8% yearly top line expansion and an earnings increase of about US$1.6b from US$494.2m today.
Uncover how Global Payments' fair value indicates a 25% potential upside to its current price before the market closes the gap.
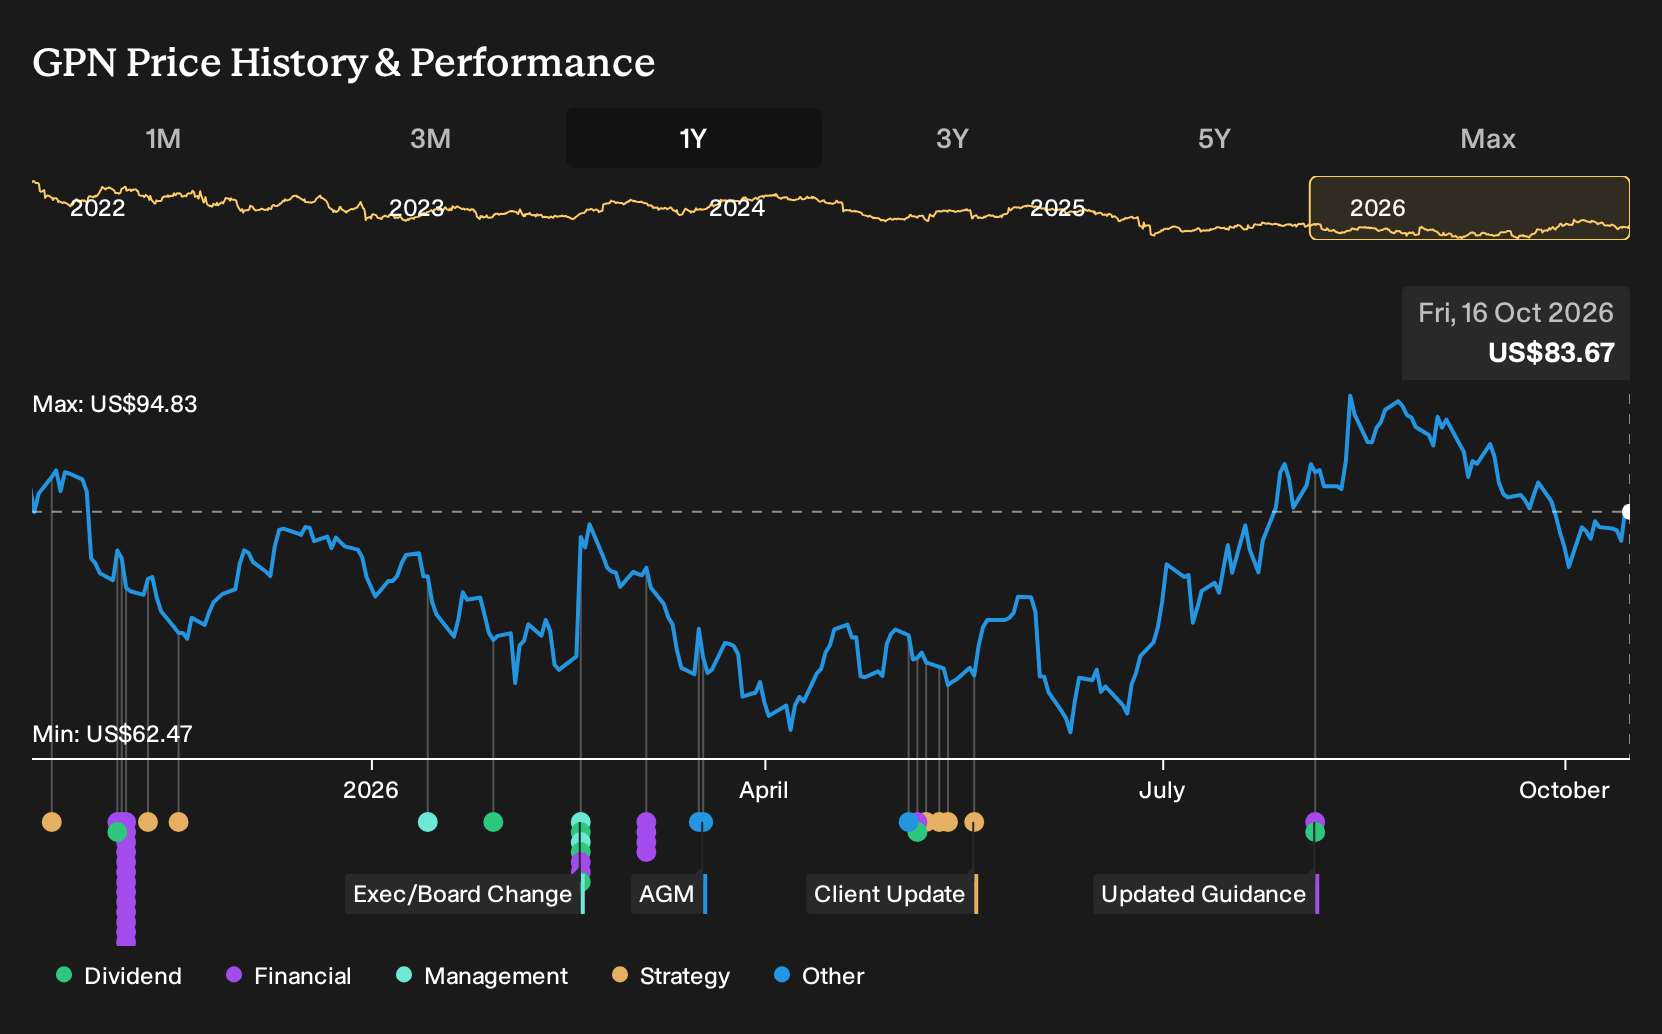
Exploring Other Perspectives
One sharp point of disagreement is travel exposure. The most bearish analysts worry that weaker airline routes could keep a 100 basis point drag on Global Payments’ volumes and leave earnings nearer US$1.1b by 2029 on about US$13.5b of revenue. That is far below consensus, so use this as a cue to compare several viewpoints and decide which story feels more realistic to you.
Explore 3 other Global Payments fair value estimates, including one that suggests it could be worth just $105.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Global Payments research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Global Payments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Payments' overall financial health at a glance.
Looking For More Ideas Beyond Global Payments?
If the Global Payments story has sharpened your thinking, use that momentum to scan a wider field of opportunities where the numbers and narrative line up more cleanly with your own risk profile.
- For investors who want resilient balance sheets and healthier fundamentals, review the list of solid balance sheet and fundamentals (25 results) and see which businesses match that preference.
- If the goal is steadier income from payouts, take a look at the 8 dividend fortresses that could help you focus on stronger yield candidates.
- When the priority is keeping downside risk tighter, filter the market using the 32 resilient stocks with low risk scores and compare how each stock stacks up against your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com