


Black Hills (BKH) Lands Google Data Center Deal, Is The Stock Still Cheap?
New Google data center deal puts Black Hills in the AI power conversation
Black Hills (BKH) has moved into the AI data center spotlight after disclosing long-term agreements to serve a planned Google facility in Cheyenne, Wyoming, which ties the utility directly to rising hyperscale power demand.
Recent trading has been strong, with Black Hills posting a 1-month share price return of 8.7% and a year-to-date share price gain of 10.0%. Total shareholder return of 26.2% over the past year and 78.5% over three years points to building momentum as investors react to the Google data center deal and fresh Arkansas rate approval.
Scan other utilities benefiting from the AI data center buildout by reviewing our curated list of 41 power grid technology and infrastructure stocks alongside the Black Hills story taking shape in Wyoming.
Black Hills has just rallied on concrete deals and fresh rate approval, not hype alone. Are investors now simply paying up for stronger fundamentals, or leaning too hard into the AI story?
Most Popular Narrative: 8% Undervalued
Black Hills closed at $76.63 compared with a widely followed fair value estimate of $83.17. This helps put the current enthusiasm in context and links the recent Google data center catalyst to longer term earnings expectations.
The prospective 1.8 GW Cheyenne data center project has advanced, with the hyperscale customer now providing up to US$377 million of refundable construction contributions to fund long lead generation equipment. This creates a clearer route to additional rate base and future earnings once assets are in service and begin contributing to revenue.
See why 18 investors see Black Hills as 8% undervalued.
Result: Fair Value of $83.17 (UNDERVALUED)
Still, this upbeat Black Hills narrative leans heavily on regulators backing a US$4.7b capital plan and on hyperscale data center clients actually building out that 3 GW pipeline.
Find out about the key risks to this Black Hills narrative.
Another View: Our DCF Model Sees Less Upside
The first take framed Black Hills as about 8% undervalued versus an $83.17 fair value. A different lens tells a cooler story. The Simply Wall St DCF model points to a future cash flow value of $66.88 per share, which sits below the current $76.63 price and signals an overvalued result instead.
That split between earnings based fair value near $83 and a DCF outcome under $67 leaves a meaningful gap. It raises a simple question for anyone looking at Black Hills right now: Which set of assumptions feels closer to how cash flows will actually show up over time, and are you comfortable picking a side or waiting for more evidence before acting on either signal?
Look into how the SWS DCF model arrives at its fair value.
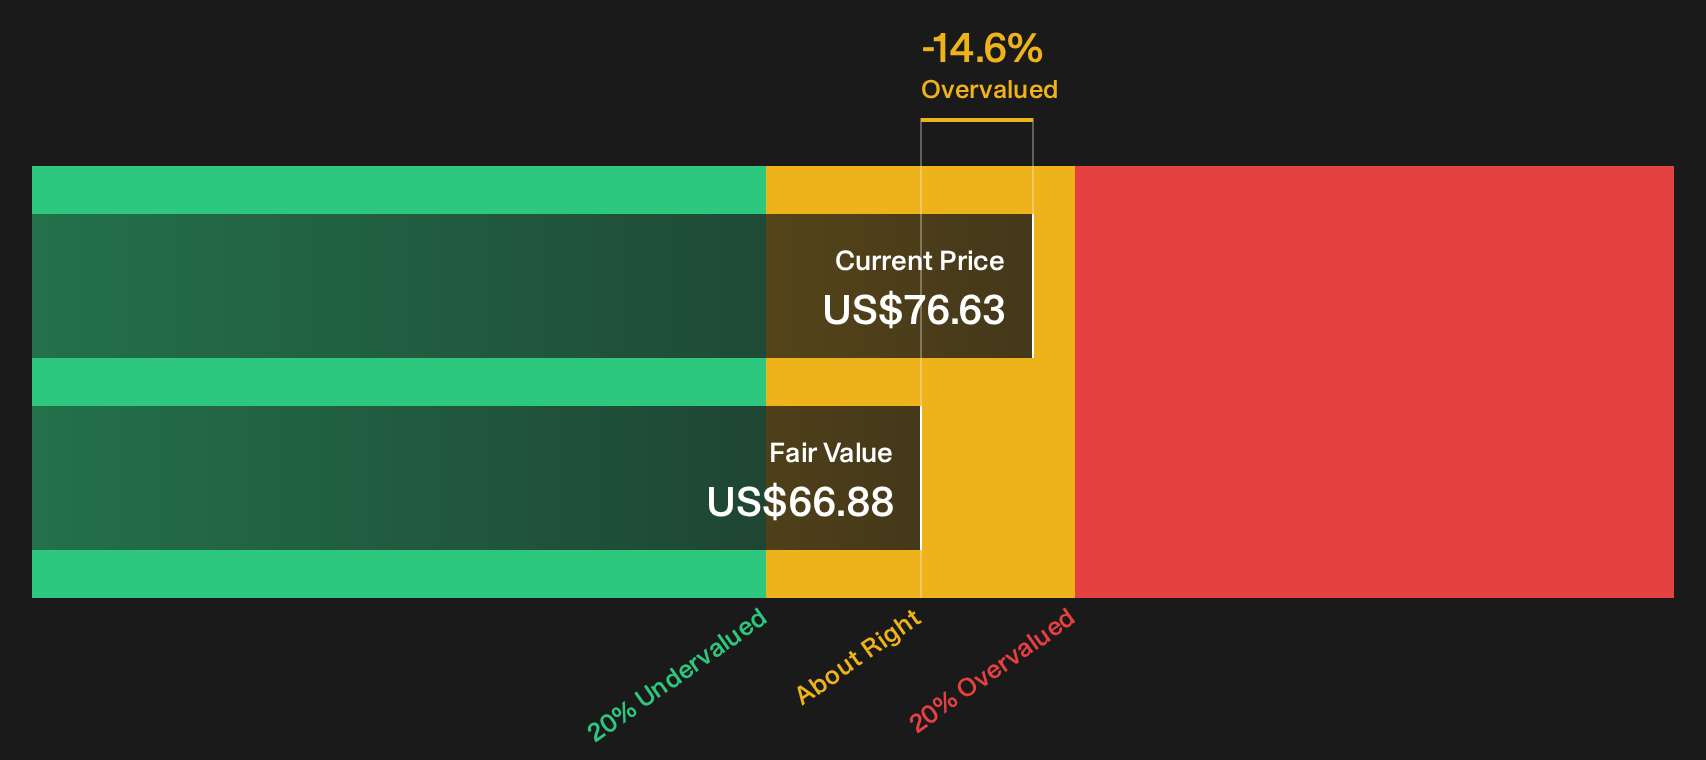
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Black Hills for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this Black Hills story can feel encouraging, yet the mix of positives and concerns is real, not theoretical. Consider moving quickly to review the underlying figures and decide where you land on 3 key rewards and 2 important warning signs.
Looking for more Black Hills style investment ideas?
If Black Hills has sharpened your focus on what you own, do not stop here. Broaden your watchlist and pressure test your next moves with targeted screeners.
- Target resilient compounding potential by scanning companies that pass tight value and quality filters through the 33 high quality undervalued stocks.
- Anchor your portfolio with reliable income candidates by reviewing the 8 dividend fortresses.
- Dial back risk without stepping away from opportunities by working through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com